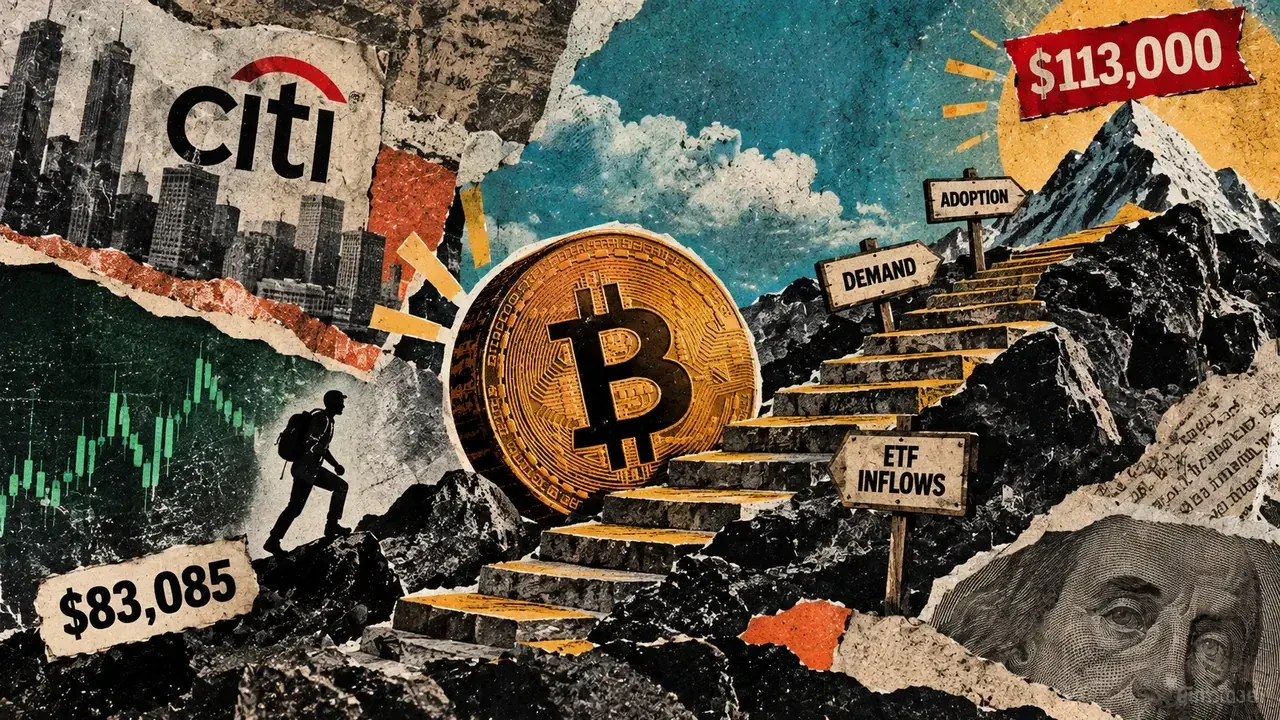
Citigroup has revised its twelve-month Bitcoin forecast upward, setting a bold target of $113,000 for the leading cryptocurrency. The adjustment, which follows a previous forecast of $82,000 announced on October 1, is underpinned by strengthening market activity, increasingly supportive macroeconomic conditions, and renewed inflows into spot exchange-traded funds (ETFs). However, while the projected price level points to a significant recovery, financial analysts emphasize that the central question facing the market is whether sustained buying pressure can actually maintain this upward trajectory in an environment characterized by unusually thin trading volumes.
The newly established $113,000 price target requires a roughly 36% increase from a reference price of $83,085 recorded on October 7. Even with this substantial upward movement, the projected figure would keep Bitcoin comfortably below its previous all-time high of $126,198.07, representing a recovery well within a previously traded historical price range rather than uncharted territory.
How large is the required move?
Evaluating the mechanics of the projected price surge reveals specific mathematical parameters. Starting from the October 7 quote of $83,085, reaching the $113,000 milestone demands a 36% gain, which translates to approximately 2.6% compounded monthly over the course of a twelve-month horizon, pointing toward an autumn 2027 timeline.
Because the target sits roughly 10.5% below Bitcoin’s prior record peak, it functions as a recovery metric. Keeping the circulating supply fixed at approximately 20.09 million BTC, the $113,000 target implies a quoted market capitalization of about $2.27 trillion. This represents an increase of approximately $601 billion in valuation, a figure that accounts for the revaluation of existing coins remaining in holders’ wallets rather than fresh capital injections alone. The actual cash required to move market prices, by contrast, depends heavily on active trading dynamics and liquidity conditions.
Historical volatility offers an additional scale for comparison. Data from onchain analytics firm Glassnode put Bitcoin’s one-year annualized realized volatility at 43.97% as of October 6. Utilizing logarithmic returns to align with this volatility measure, the required gain calculates to roughly 30.8%, or about 0.70 times the annualized scale. Generating precise probability or directional forecasts, however, would necessitate additional macroeconomic assumptions.
What the ETF assumption can establish
Citi’s revised outlook builds upon historical correlations observed in its broader digital asset research. In its January 2025 outlook report, the financial institution published a historical association suggesting roughly 4.7% Bitcoin returns associated with each $1 billion of net ETF inflows. According to that analysis, institutional flows accounted for approximately 46% of price-action variance.
However, public summaries of the research leave the observation frequency and the complete regression equation undisclosed. Furthermore, Reuters’ recent reporting did not specify the exact composition of the newly projected $5 billion crypto inflow category over the coming year, as advisers and brokerages gradually expand their portfolio allocations. These informational gaps mean that any calculations must rely on arithmetic illustrations rather than replicating Citi’s proprietary predictive models.
If an assumption is made that the entire reported $5 billion enters Bitcoin ETFs as net inflows, applying the historical linear association to the October 7 reference price yields a 23.5% upside, pushing the asset toward a price near $102,600. While illustrative, this linear application cannot definitively prove whether a $5 billion inflow is insufficient or identify an exact annual inflow threshold necessary to reach the bank’s target. Broader macroeconomic conditions and the willingness of long-term holders to sell ultimately dictate how effectively any given volume of buying pressure translates into price appreciation.
What the current data show
While institutional forecasts point to long-term gains, immediate market data paint a more nuanced picture of liquidity and participation. Glassnode’s October 7 report estimated that combined Bitcoin spot exchange and US spot ETF trading volume hovered at approximately $6.8 billion per day on a seven-day average. This level of activity remains exceptionally subdued, sitting below the volume recorded on nine out of every ten days since January 2024. While trading volume measures overall market activity, net flows measure the precise balance of capital entering and leaving investment vehicles.
Over the thirty days leading up to October 5, Glassnode estimated that roughly $4.9 billion in new capital entered the ecosystem via ETF flows, stablecoin expansion, and corporate treasury acquisitions. During the same period, Bitcoin’s realized capitalization climbed by approximately $12.8 billion. Realized capitalization values individual coins based on the specific prices at which they last moved onchain, meaning its aggregate increase reflects changes in the market’s collective cost basis rather than nominal market capitalization growth.
Short-term institutional flows have also displayed typical volatility. US spot Bitcoin ETFs registered net inflows of $118.8 million on October 6, only to be followed by net outflows of $484.9 million on October 7, according to data compiled by Farside.
Macroeconomic indicators provide further context for the broader financial environment. The Federal Reserve’s broad dollar index edged upward by about 0.34% between September 30 and October 2, while the benchmark ten-year US Treasury yield increased by seven basis points, moving from 5.24% on October 1 to 5.31% on October 5. Meanwhile, stablecoin capitalization stood at approximately $308 billion with modest growth of about 1% over a thirty-day period, though the ultimate impact of these digital tokens on Bitcoin prices depends heavily on how holders choose to deploy them.
Ultimately, recurring net ETF purchases paired with a revival in broader spot market activity would significantly reinforce the market demand required to achieve Citi’s $113,000 target. Conversely, sustained fund redemptions would undermine the evidence of durable buying support. Glassnode’s composite metrics confirm that new capital is indeed finding its way into the market, but the presence of thin daily turnover leaves broader retail and institutional participation an open question. The price movement required to reach the bank’s target has ample historical precedent, but whether buyers possess the momentum to sustain it remains the central challenge for the market ahead.