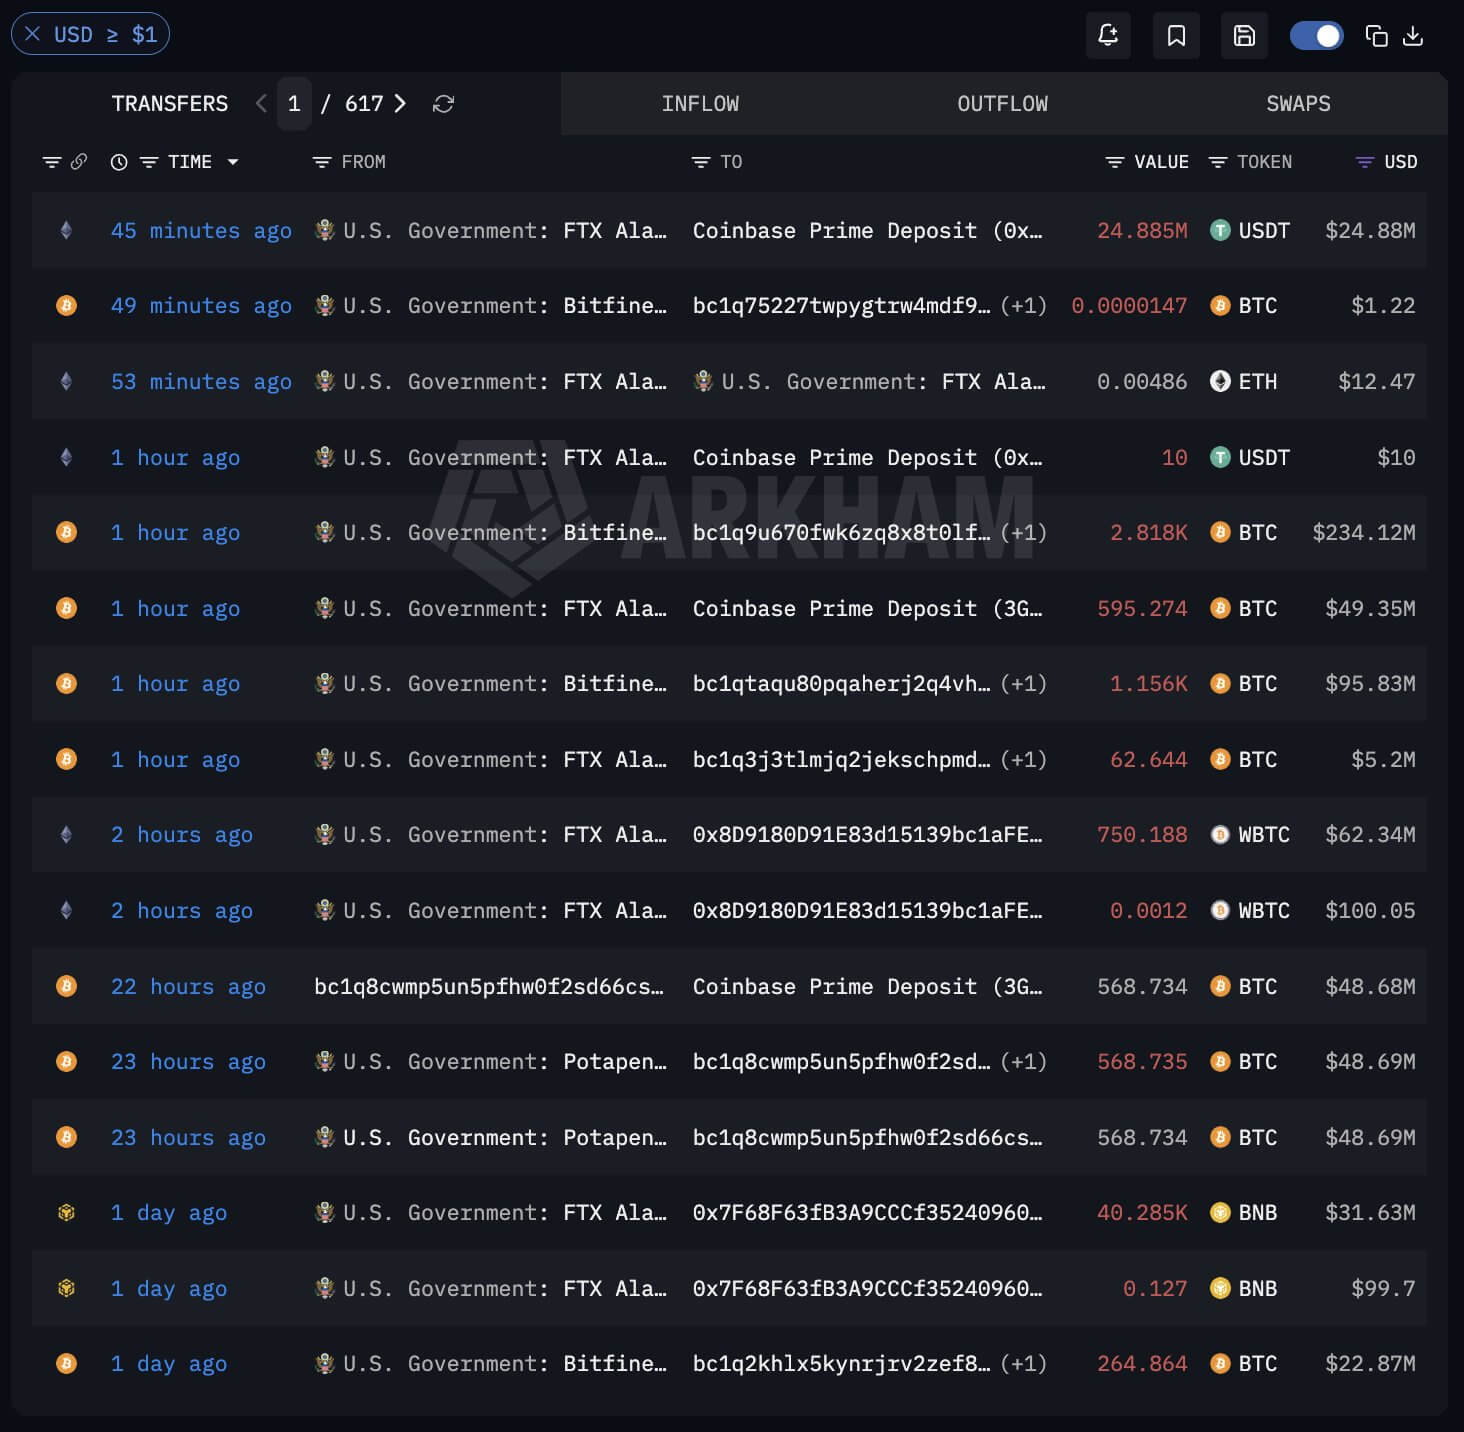
The United States government has transferred approximately $470 million worth of seized digital assets to addresses identified as likely belonging to Coinbase Prime, according to on-chain data from blockchain analytics firm Arkham Intelligence. The substantial movement of funds has once again sparked intense discussions across the cryptocurrency market regarding whether federal authorities are preparing to liquidate a portion of the nation’s massive digital asset holdings, or if the transaction is simply a matter of administrative housekeeping and internal wallet management.
On October 7, Arkham Intelligence reported the notable transfer across public blockchain networks, revealing that the digital assets involved included Bitcoin, wrapped Bitcoin, and USDT. According to the blockchain intelligence platform, these transferred assets have been directly linked to previous federal seizures involving two of the most high-profile criminal investigations in the history of the digital asset industry: the 2016 Bitfinex exchange hack and Alameda Research, the prominent digital asset trading firm that was formerly controlled by FTX founder Sam Bankman-Fried.
While the destination of the funds has caught the attention of traders, analysts, and blockchain observers, the ultimate intent behind the transaction remains unconfirmed. Market participants immediately raised questions about a potential impending asset sale, given that large institutional custody platforms like Coinbase Prime are frequently utilized by institutional entities to execute large-scale market orders. However, industry experts note that it is equally plausible that the federal government is merely performing routine internal wallet hygiene, upgrading its custody infrastructure, or consolidating administrative work across various law enforcement agencies.
Still, the choice of destination places the transaction under much greater regulatory and political scrutiny. This heightened attention comes on the heels of repeated pledges by the Trump administration to retain Bitcoin placed within the official US Strategic Bitcoin Reserve. Furthermore, it follows federal officials pushing back earlier this year against claims that previously seized coins had been quietly sold off by the government without public transparency.
A Previous Sale Claim Ended in a Government Denial
The latest movement of funds lands approximately nine months after the US Marshals Service was forced to push back publicly against circulating reports that Washington had quietly disposed of Bitcoin surrendered during the course of the Samourai Wallet criminal case.
Back in January, Bitcoin Magazine reported that roughly $6.3 million worth of Bitcoin—which had been paid to the US Department of Justice as part of formal guilty pleas—appeared to have been liquidated. The report immediately drew concern from lawmakers on Capitol Hill, most notably Senator Cynthia Lummis, who stands out as one of the United States Congress’s most prominent and vocal Bitcoin advocates. Lummis publicly questioned why federal authorities would liquidate the asset shortly after President Donald Trump had issued explicit directives instructing officials to preserve and accumulate Bitcoin for the national reserve.
In response to the mounting public pressure and legislative inquiry, the US Marshals Service told DL News that it had not sold those specific bitcoins. The agency further clarified that its digital asset liquidations are subject to a rigorous, multi-level approval process before any forfeited properties can officially be disposed of.
The sensitivity surrounding government-held digital assets intensified significantly after President Trump established the Strategic Bitcoin Reserve in March 2025. The official presidential executive order explicitly mandated that any Bitcoin deposited into the newly formed reserve "shall not be sold" and must instead be maintained as a permanent US reserve asset for the benefit of the nation. At the time of the announcement, the White House argued forcefully that premature government Bitcoin sales carried out by previous administrations had already cost American taxpayers more than $17 billion in foregone long-term value.
Seized Bitcoin Does Not Automatically Mean Reserve Bitcoin
Despite the strict rules governing the Strategic Bitcoin Reserve, the foundational policy leaves certain legal pathways open for specific categories of government-controlled crypto to move out of federal custody.
President Trump’s executive order explicitly permits digital assets to be disposed of under specific circumstances, such as when required by a court order or applicable law. Disposals are also authorized when federal officials determine that the assets—or the financial proceeds generated from them—should be returned to verified crime victims, utilized for essential law enforcement operations, or applied toward other statutory forfeiture obligations mandated by the courts.
This crucial legal distinction could prove particularly important for understanding the context behind these latest transfers. The federal government originally seized approximately 95,000 Bitcoin back in 2022 from digital wallets controlled by Ilya Lichtenstein and Heather Morgan as part of the sprawling federal investigation into the massive Bitfinex hack. Lichtenstein later stood before a federal court and admitted to executing the cyberattack on the exchange, during which roughly 119,754 Bitcoin were originally stolen in 2016. In the wake of those admissions, authorities successfully seized hundreds of millions of dollars in additional assets tied directly to the recovery of the historic theft.
Because those particular assets have faced a labyrinth of competing forfeiture claims, legal restitution demands, and creditor disputes, their ultimate legal treatment differs fundamentally from clean Bitcoin that has already been officially transferred into the Strategic Bitcoin Reserve. Bitfinex and its stakeholders have continuously pursued the recovery of their stolen property, leading to complex legal frameworks governing how the seized funds must eventually be handled.
Similarly, the catastrophic collapse of the FTX exchange and its sister trading firm, Alameda Research, triggered extensive criminal forfeiture proceedings across the federal court system. The presiding federal judge in Sam Bankman-Fried’s criminal case formally authorized recovered forfeiture funds to be dedicated toward compensating victims who suffered devastating financial losses during the platform’s sudden implosion. This adds another distinct victim-repayment dimension to the latest asset movements, reminding market participants that not all government-held crypto is destined for a national stockpile.
As a result, the substantial transaction flagged by Arkham Intelligence serves as a real-world test of how much accurate insight can actually be inferred simply by monitoring public government-controlled wallet addresses on the blockchain.
A confirmed sale of Bitcoin that had already been formally deposited into the Strategic Bitcoin Reserve—carried out outside of the narrow exceptions outlined in the executive order—would immediately reopen intense questions over whether federal agencies are faithfully executing the administration’s stated accumulation policy. Conversely, a transfer executed primarily for institutional custody management, court-ordered victim restitution, or another permitted forfeiture purpose would fall squarely into a completely different operational category.
For the time being, blockchain monitoring tools show hundreds of millions of dollars leaving sovereign US government wallets and arriving at addresses associated with Coinbase Prime. Whether those digital assets ultimately remain parked there, migrate into alternative long-term custody arrangements, or are systematically converted into fiat currency will ultimately determine whether this latest transaction goes down as another false alarm over federal Bitcoin sales or becomes the first clear sign of a significant new round of asset disposals.