Global financial markets are quietly adjusting as institutional investors pull back from one of the most popular, yet heavily leveraged, strategies in the fixed-income ecosystem: the Treasury cash-futures basis trade.
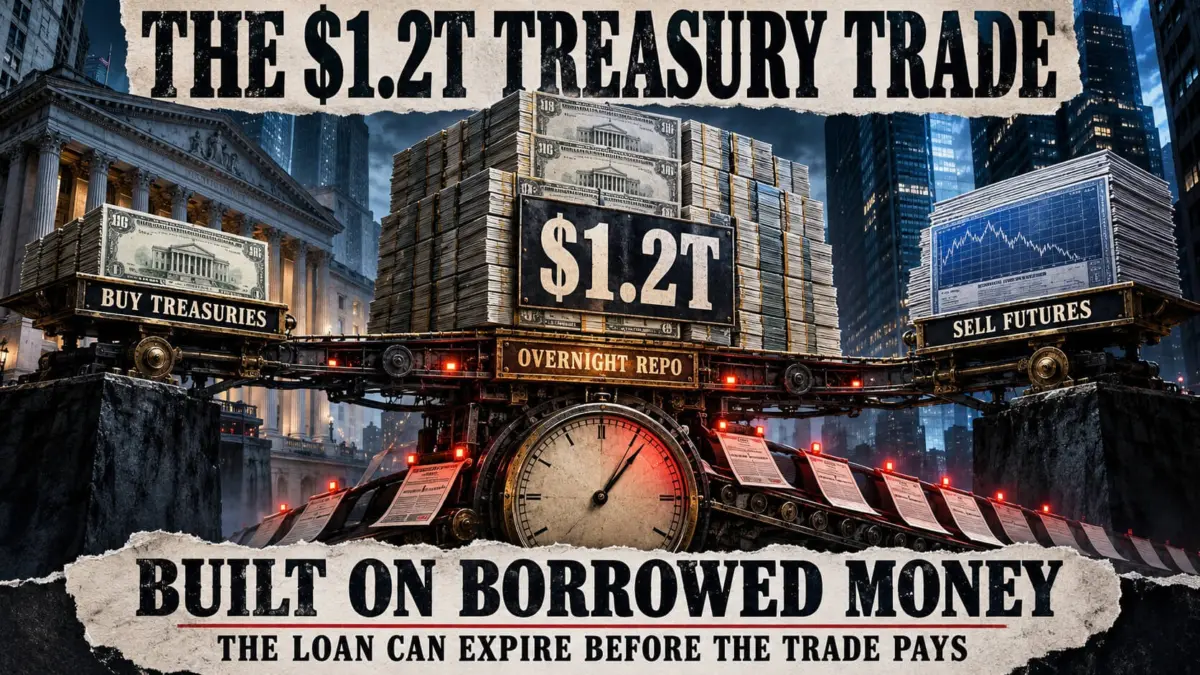
Recent industry data suggests that positions tied to this complex arbitrage mechanism have contracted notably over the past year. According to reports published by Morgan Stanley in late September, aggregate positions in the basis trade have fallen by approximately 20% down to roughly $1.2 trillion. While the contraction sounds dramatic, major financial institutions at the time found little evidence of widespread, systemic market stress directly attributable to the wind-down, indicating that a shrinking trade does not automatically portend an imminent market blow-up.
Even so, the sheer scale of the capital involved means that shifts in the basis trade carry implications that reach far beyond the standard bond trading desk. The strategy relies on massive amounts of borrowed money to capture microscopic pricing inefficiencies, creating an intricate web of financial dependencies between hedge funds, overnight lending markets, and the United States government’s sprawling debt issuance.
Hedge funds love small profits when it’s someone else’s money
To understand the mechanics of the cash-futures basis trade, one must look at how institutional investors interact with the US government debt market. Companies can effectively own a mountain of US government debt without taking on directional bets that long-term bond prices will rise. Instead, hedge funds execute a dual-sided maneuver: they buy Treasury securities in the cash market and simultaneously sell corresponding futures contracts against them to capture a tiny pricing gap.
This strategy requires borrowing the vast majority of the purchase money to make the overall return worthwhile. The US government receives another reliable buyer for its continuous issuance of debt, and that buyer’s interest lasts precisely as long as the trade remains profitable.
The core of the trade involves exploiting the relationship between cash bonds and futures contracts. An investor can purchase a Treasury security outright, or they can trade a futures contract that establishes the terms today for a transaction that will be completed at a later date. The futures contract explicitly specifies which securities can be delivered against it upon maturity, thereby linking their prices without making them identical.
When futures contracts become sufficiently expensive relative to an eligible underlying bond, a hedge fund will step in to buy the bond while selling the futures. Market participants seeking exposure to the broader bond market through contracts supply the other side of the transaction, leaving the hedge fund holding the actual physical securities.
Selling the futures serves as a structural hedge. If prevailing bond prices fall, the short futures position can earn money that offsets a substantial portion of the capital loss on the physical bond. The primary goal of the fund is to collect the pricing gap as the contract steadily approaches its delivery date, all while heavily insulating itself from the broader market’s directional volatility.
To pay for the underlying bond purchase, funds routinely utilize the repurchase agreement market, commonly known as repo. In a repo transaction, the fund sells the security for immediate cash and simultaneously agrees to buy it back at a slightly later date at a marginally higher price. Economically speaking, this arrangement functions precisely like a short-term loan secured by the bond itself.
Because much of this financing is conducted on an overnight basis, the fund must continuously renew or replace its financing arrangements to keep the complex position alive. This is where the inherent vulnerability of the trade reveals itself.
Consider an illustrative $100 million position generating a net return of just 0.2% annually from the strategy, calculated after accounting for estimated financing and trading costs. That modest percentage yields $200,000 in gross profit. However, that figure transforms into an attractive 4% return on equity if the hedge fund has committed only $5 million of its own capital to the venture, funding the remaining $95 million through short-term borrowing.
The financial vulnerability emerges when borrowing costs shift. If the overnight borrowing expenses on that $95 million increase by a mere 0.2% over the course of the year, the resulting extra interest bill amounts to $190,000. Suddenly, almost the entire expected profit of the strategy has evaporated and been transferred directly to the lender, and this occurs entirely independently of whether the US government maintains its flawless record of debt repayment.
Reports from the Office of Financial Research highlight that accurately evaluating the true profitability of this setup requires factoring in the cost of futures margin, along with the seller’s embedded options regarding which eligible bond to deliver and the exact timing of that delivery. Calculating a realistic return means carefully valuing those delivery rights and rigorously accounting for shifting financing and margin expenses.
When those calculations stop looking attractive to portfolio managers, a fund does not necessarily trigger a crisis. Instead, professional investors can simply choose to let positions expire naturally, declining to replace them as the underlying contracts mature. Institutional asset managers do not require a market emergency to decide they have better, more lucrative uses for their capital.
Being right doesn’t pay today’s bill
The fundamental friction of the cash-futures basis trade lies in timing and liquidity mismatches. Even if a hedge fund’s macro thesis and hedging structure are entirely correct, the fund may simply lack the immediate liquidity required to service the daily cash payments needed to keep the position open.
Suppose a scenario where the physical bond gains value while the short futures position incurs a matching, equivalent loss. In this instance, the futures clearing account can demand an immediate cash payment to cover that loss—a mechanism known as variation margin. Meanwhile, the concurrent gain on the physical bond remains entirely locked up and illiquid within the security itself.
The fund is forced to extract cash out of that asset or scramble to source dollars from elsewhere before the stringent payment deadline arrives. Crypto traders who have experienced holding unrealized gains on one exchange while facing an impending liquidation on another will readily recognize this structural operational challenge: capital trapped in the wrong account will not satisfy an urgent payment demand, and offering theoretical explanations about an underlying hedge will not extend a broker’s payment deadline.
Repo lenders can similarly tighten the screws on short-term borrowers. If a lender provides $98 of financing against $100 worth of bonds, the fund must supply the remaining $2 out of its own pocket, representing a 2% haircut. If market volatility causes that required haircut to double to 4%, the fund must suddenly supply twice as much of its own capital against the exact same collateral, even before factoring in any concurrent margin calls on its futures positions.
When a large cohort of hedge funds is forced to unwind or close out their positions simultaneously, the market dynamics turn aggressive. Funds sell physical bonds into the open market to repay their outstanding loans while aggressively buying back futures contracts to close out their short positions.
Those coordinated, forced trades can violently push bond prices down relative to futures prices, actively harming other funds that are still attempting to hold the exact same positions and rendering their own eventual exits significantly more expensive. This dynamic of forced liquidation is fundamentally distinct from letting trades naturally expire without renewal, though both behaviors ultimately result in a reduction of outstanding market positions. A simple headline contraction figure does not immediately reveal which of these two distinct mechanisms is driving the reduction in total leverage.
Federal Reserve researchers estimated that basis trade positions stood at approximately $830 billion in September 2025, according to research published in June. Because that calculation and Morgan Stanley’s newer estimate of $1.2 trillion utilize different methodological approaches and data collection parameters, treating them as consecutive, direct readings manufactures a comparative trajectory that the underlying data does not robustly support. Furthermore, broader reports tracking hedge-fund Treasury holdings inherently encompass a wide variety of unrelated investment strategies, just as their short futures positions reflect multiple overlapping market objectives.
Someone still has to own the Treasury bonds
A financial ecosystem characterized by fewer leveraged trades dependent on overnight funding can ultimately render the broader market less fragile, provided that the subsequent wave of bond owners brings stable, long-term financing that they can comfortably maintain through periods of financial turbulence. Investors who purchase government debt using fully committed capital do not face the grueling, daily renegotiations with repo lenders that hedge funds must navigate.
At the same time, those natural, un-leveraged buyers may demand more attractive pricing because they are acquiring the bonds strictly for their long-term income generation. Cheaper bonds inherently offer higher baseline yields, which can successfully attract replacement demand from traditional institutional investors while simultaneously making new government borrowing more expensive for the Treasury Department.
Primary dealers can temporarily absorb and hold bonds on their balance sheets while searching for end-purchasers, but dealer balance sheet capacity also carries a real financial cost and is subject to strict regulatory limits. An orderly transition of the debt away from leveraged funds can therefore leave Washington paying higher interest rates to place its debt, even if the process occurs without triggering a disorderly market breakdown.
Higher repo rates and larger collateral haircuts become acutely concerning if leveraged funds are cornered into selling assets directly into a market devoid of willing buyers. Those underlying financing terms and the actual prices sellers are able to obtain provide a far more accurate reflection of systemic stress than a simple aggregate position total ever could.
Similar analytical restraint applies across other asset classes, including digital assets. Broader balance sheet data from institutional managers illustrates why any single investment strategy cannot stand as a proxy for everything those complex financial firms do.
Connecting strains in the traditional Treasury market to movements in the cryptocurrency sector requires direct evidence that the specific institutions involved are actively liquidating crypto assets or pulling back credit lines, rather than automatically assuming that every corporate cash crunch culminates in a forced Bitcoin sale.
Ultimately, borrowed money is the primary mechanism that makes these funds willing to own vast quantities of government bonds for a risk-adjusted return that would otherwise be far too small to justify the operational effort. When that fragile mathematical calculation ceases to work, letting leveraged positions run off can successfully reduce the financial system’s dangerous reliance on overnight loans. However, the subsequent owners of that debt will likely require a higher yield to take the massive issuance off their hands.