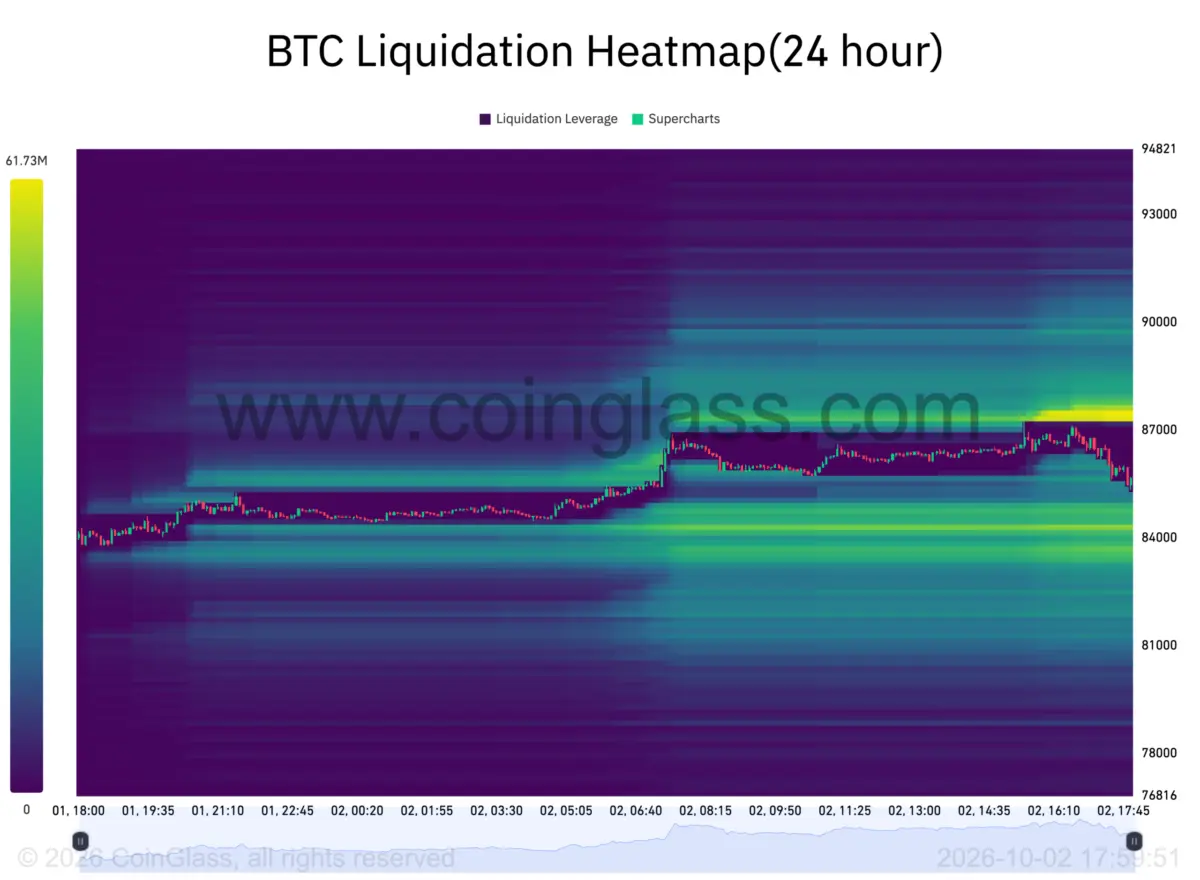
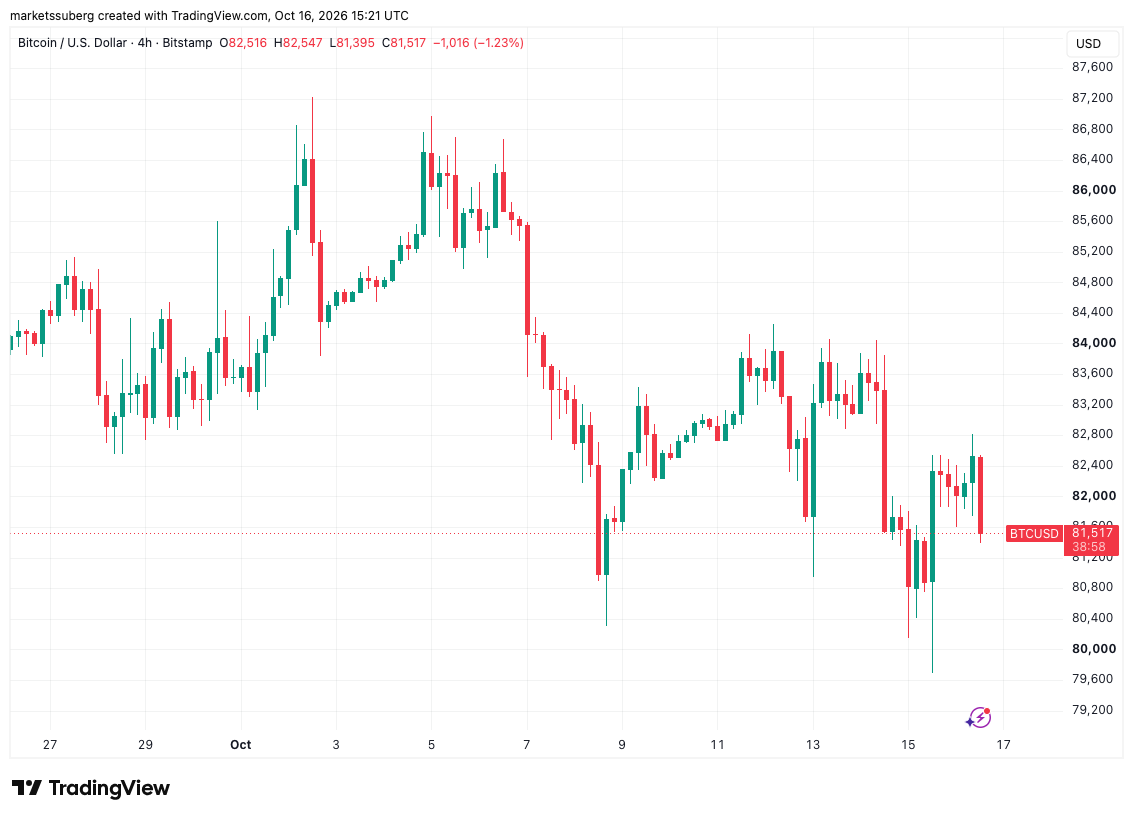
Bitcoin traded close to the $82,000 mark around Friday’s Wall Street opening bell, finding renewed stability as broader cryptocurrency markets recovered alongside a partial rebound in South Korean equities. The premier cryptocurrency managed to hold onto the vast majority of its reclaimed ground after executing a solid technical bounce from the $80,000 threshold during the previous trading session.
Market participants closely monitored a confluence of macroeconomic factors, ranging from shifting monetary policy signals out of the United States Federal Reserve to geopolitical tensions and localized sell-offs in Asian technology sectors. While traditional risk assets experienced mixed fortunes across global exchanges, digital assets demonstrated resilience, digesting recent inflationary pressures and adjusting to evolving expectations regarding central bank interest rates.
Traders See Dovish Edge to Warsh Comments
Data from TradingView illustrated that the BTC/USD trading pair successfully defended its psychological support zones, holding firm after dropping briefly during a broader market correction earlier in the week. The initial downward pressure on digital assets had coincided with a persistent, weeklong sell-off affecting South Korean technology stocks, which sent ripples of caution across international trading desks.
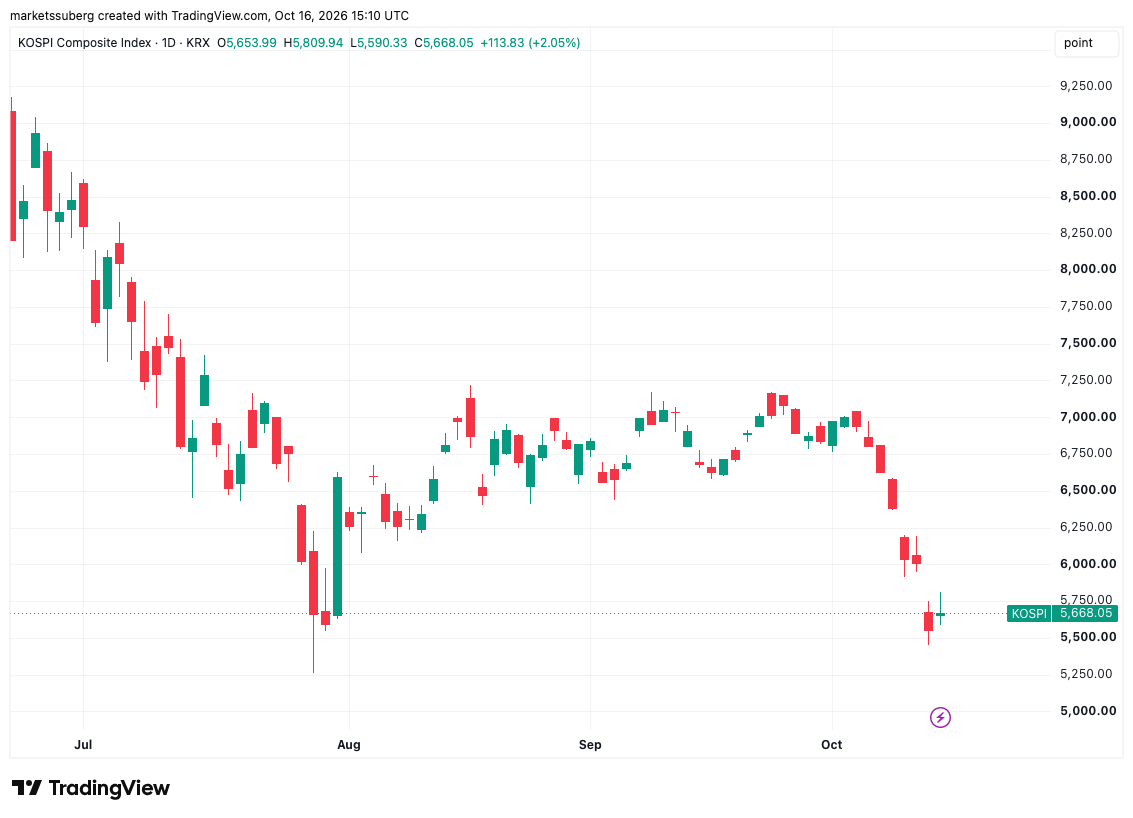
However, Friday’s Asian trading hours offered a welcome degree of relief. The KOSPI Composite Index staged a notable recovery session, closing out the day up 2% at 5,668. Despite the encouraging end-of-week bounce, the regional index still finished the period down 8.3% overall, highlighting underlying volatility in technology-heavy Asian markets.
Meanwhile, United States equities largely avoided the steeper sell-offs seen overseas, though Wall Street indices turned in a mixed performance on Friday. The tech-focused Nasdaq Composite Index drifted down by 0.5%, while the broader S&P 500 managed a modest gain of 0.5%.
Against this mixed backdrop, commentary from Federal Reserve leadership provided investors with a measure of relief. During a high-profile discussion with International Monetary Fund (IMF) Managing Director Kristalina Georgieva, Federal Reserve Chair Kevin Warsh deliberately avoided signaling any immediate intention to pursue further interest rate hikes. When pressed on the trajectory of monetary policy, Warsh maintained a measured stance regarding upcoming central bank deliberations.
"I don’t prejudge meetings. I don’t believe in saying now what I might do at the meetings that we have in the balance of this year," Warsh remarked during the discussion.
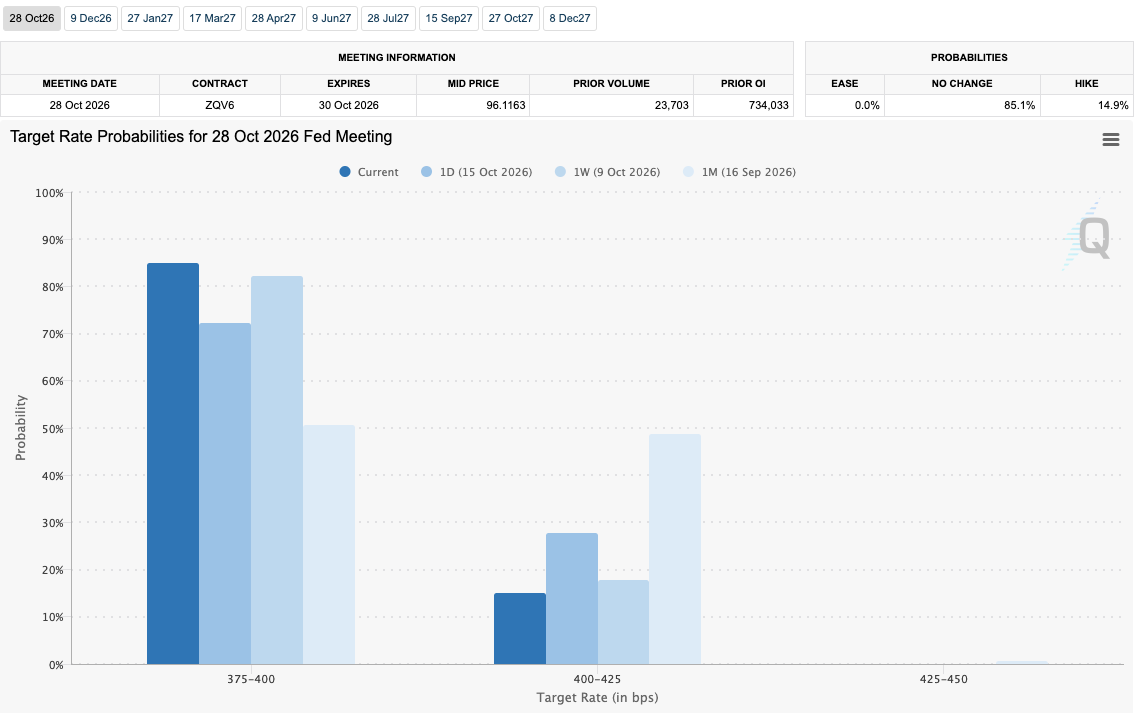
Financial markets quickly interpreted Warsh’s calculated restraint as a dovish signal, pulling back expectations for aggressive monetary tightening. According to data retrieved from CME Group’s FedWatch Tool, the market-implied probability of a 25-basis-point interest rate hike at the upcoming October Federal Open Market Committee meeting dropped sharply to 15%, falling significantly from the 27% probability recorded just one day prior.
Prominent economist Robin Brooks weighed in on the central bank’s shifting tone, suggesting that underlying stress within the artificial intelligence sector—which had heavily influenced the recent sell-off in South Korean markets—might be playing a silent role in shaping the Federal Reserve’s more cautious approach.
"Warsh gave no indication the Fed’s in any hurry to hike, so the October meeting is now pretty much off the table in terms of a hike," Brooks wrote in a recent public note. He further added that "what’s helping the Fed is fears of an AI blow-up, which is making markets more receptive to a dovish message."
US Bond Yields Eye Rebound as Stocks Halt Upside
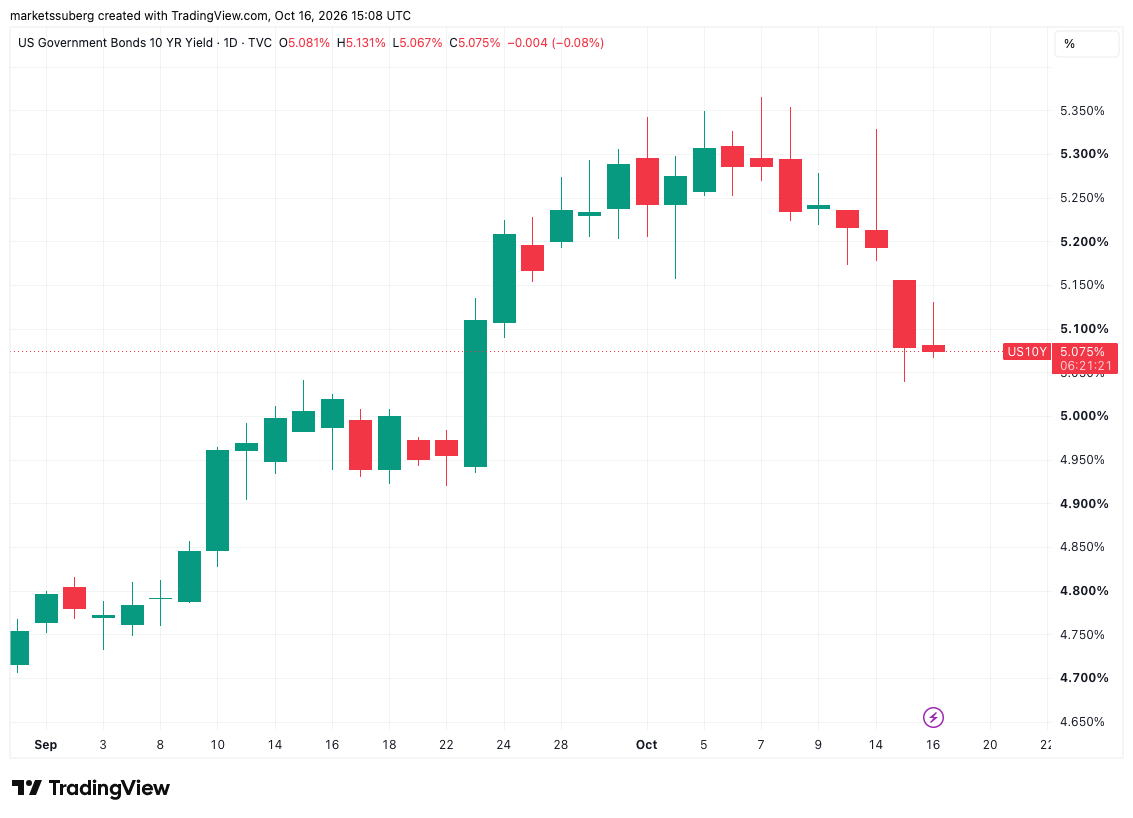
While equity and crypto markets found temporary footing following the Federal Reserve’s perceived pivot, traditional fixed-income markets told a slightly different story. United States Treasury bond yields began pressing upward as stocks steadied, leading some market analysts to suggest that the United States Treasury may eventually find itself caught in a difficult balancing act. Policymakers could soon be forced to choose between actively working to tame a persistent bond market sell-off or maintaining favorable conditions to keep stock market indices in bullish territory.
The benchmark United States 10-year Treasury yield hovered around 5.07% on Friday, having earlier attempted a sharper upward reversal that briefly pushed the yield as high as 5.13%.
Market commentary published by The Kobeissi Letter highlighted that equity market weakness has served as the primary catalyst for bond yield corrections since the month of August. In a detailed social media analysis released earlier in the week, the commentary suggested that global equities may currently be trapped within a paradoxical "bull-bear" market environment.
The analysis argued that without external geopolitical pressures, such as the ongoing conflict involving the United States and Iran, broader stock markets would likely be trading at significantly higher valuations. Furthermore, persistent domestic inflation has continued to drive strong investor demand for hard asset exposure, even as the Federal Reserve initiates a renewed interest rate hike cycle to combat rising consumer prices.
"Even as the S&P 500 hits year number five of its bull market, we believe a steep discount is currently priced into equities," the commentary stated. "This discount has functioned as a ‘stealth’ bear market, suppressing equity valuations in the world’s largest and fastest-growing companies."
The analysis concluded that this compressed market backdrop carries the distinct potential to catalyze a violent, upward relief rally in the S&P 500 if and when those lingering macroeconomic discounts are ultimately priced out of the market by institutional participants. As macroeconomic indicators continue to fluctuate, digital asset traders and traditional equity investors alike will continue weighing incoming central bank commentary, treasury yields, and global geopolitical developments to determine the next major directional move for risk-on assets.