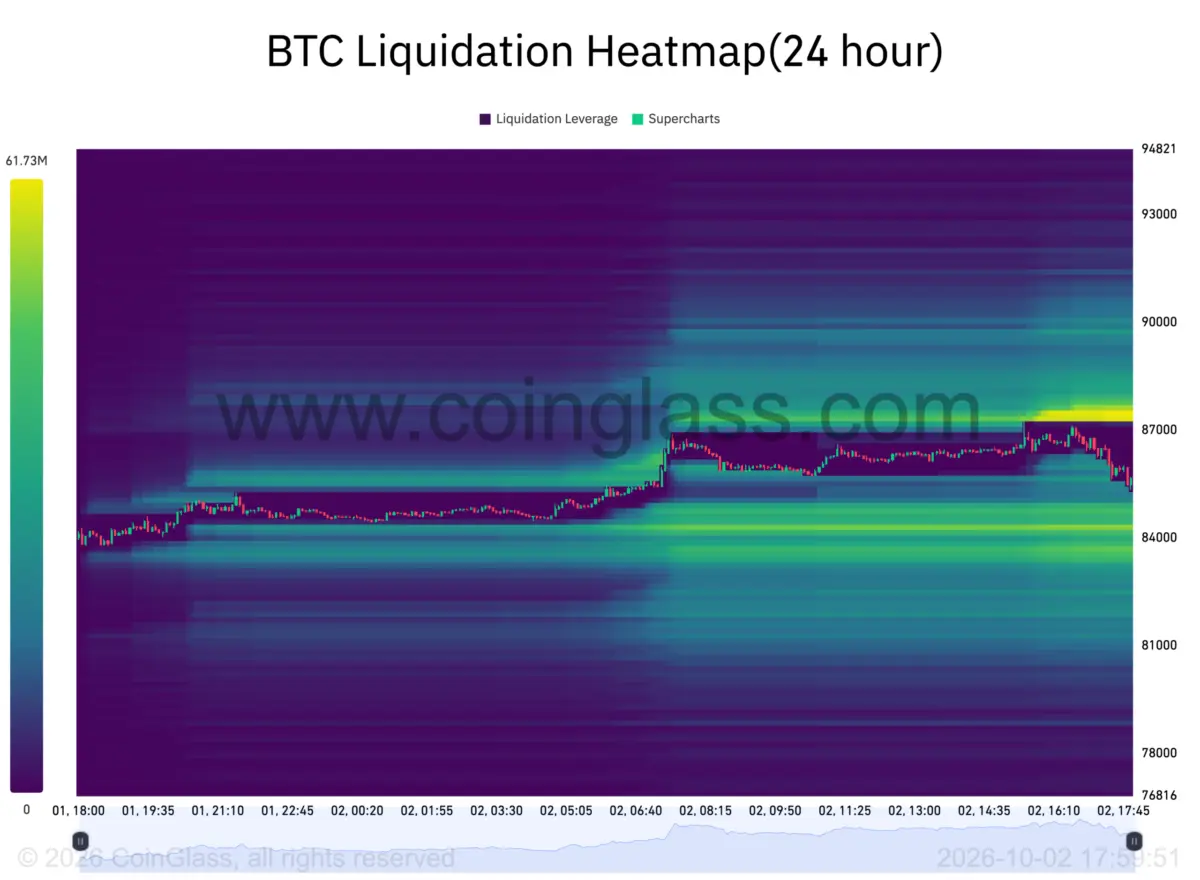
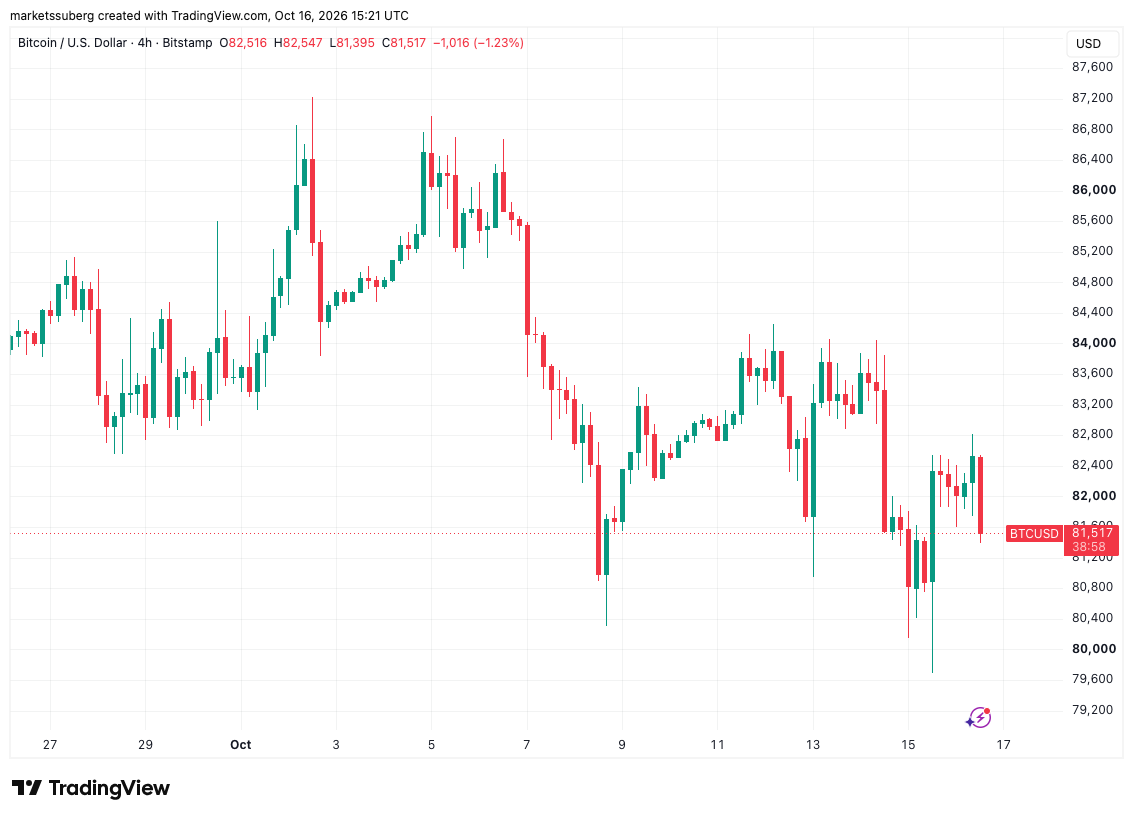
Bitcoin (BTC) traded near the $82,000 threshold as Wall Street opened on Friday, finding stability alongside a broader recovery in international equities, most notably a rebound in South Korean stocks.
The premier cryptocurrency successfully defended crucial technical levels after recovering from a mid-week dip. Market participants closely monitored macroeconomic developments, including comments from Federal Reserve officials and fluctuating bond yields, which continued to influence risk appetite across both traditional and digital asset markets.
Traders See Dovish Edge to Warsh Comments
Data from TradingView indicated that the BTC/USD trading pair managed to hold the vast majority of its reclaimed ground following a sharp downside volatility event that saw prices bounce firmly off the $80,000 support level on Thursday.
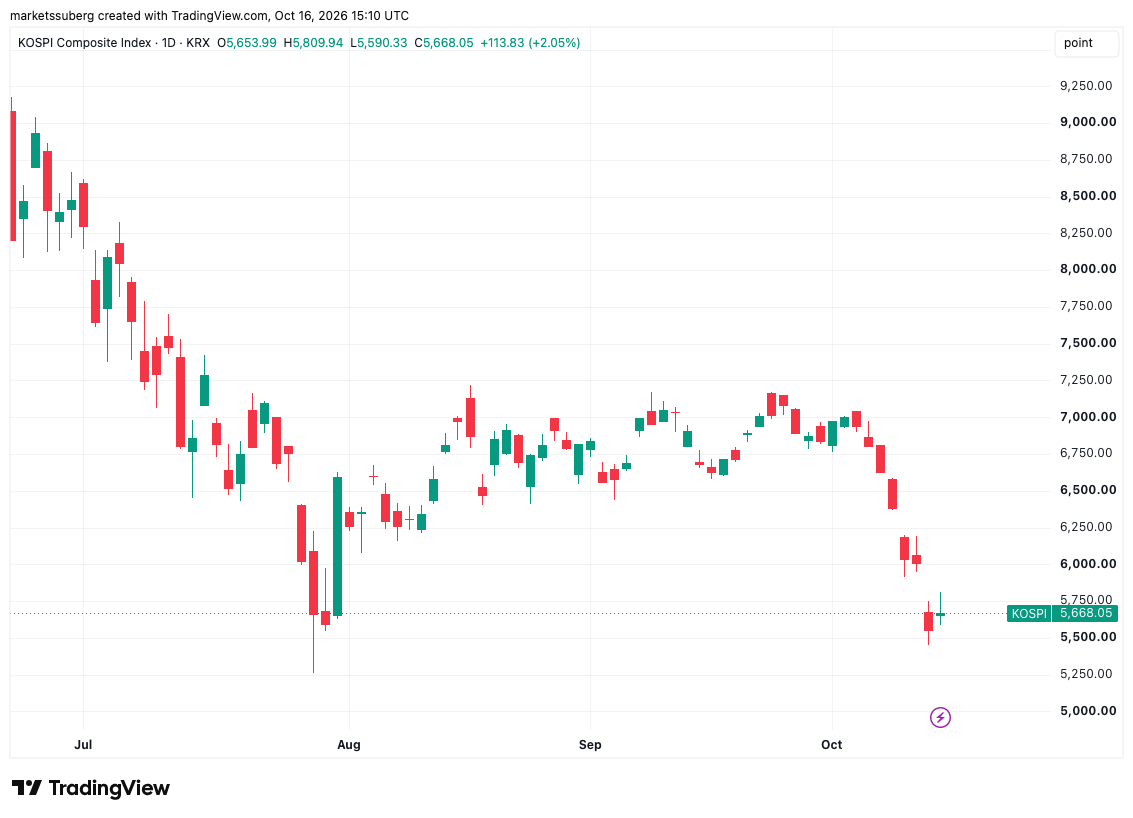
The preceding downward pressure in the cryptocurrency market had mirrored a weeklong sell-off concentrated within South Korean technology stocks. However, relief arrived during Friday’s Asian trading session. The KOSPI Composite Index managed to close the day up 2%, settling at 5,668, although the index still finished the week with an 8.3% net loss.
Meanwhile, United States equities largely managed to sidestep the heavier downturn seen in Asian markets, though Wall Street indices turned in a mixed performance on Friday. The tech-heavy Nasdaq Composite Index slipped by 0.5%, while the broader S&P 500 managed a modest gain of 0.5%.
Against this backdrop of fluctuating equity valuations, Federal Reserve Chair Kevin Warsh provided investors with a degree of psychological relief during a high-profile discussion with International Monetary Fund (IMF) Managing Director Kristalina Georgieva. Crucially, Warsh avoided making any explicit remarks hinting at further interest rate hikes during the remainder of the calendar year.
"I don’t prejudge meetings. I don’t believe in saying now what I might do at the meetings that we have in the balance of this year," Warsh stated during the exchange.
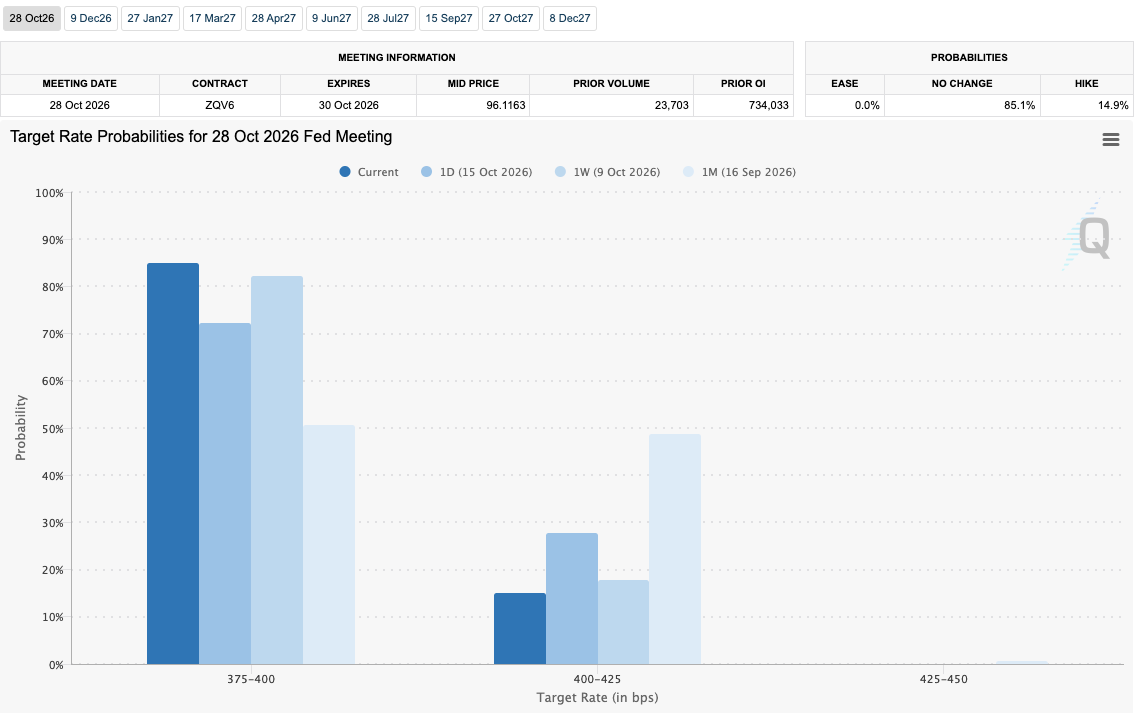
Financial markets quickly interpreted his neutral tone as carrying a dovish undercurrent regarding the trajectory of monetary policy. Updated metrics from CME Group’s FedWatch Tool illustrated a sharp shift in market expectations. The implied probability of a 25-basis-point interest rate hike occurring at the upcoming October Federal Open Market Committee (FOMC) meeting dropped precipitously to 15%, down significantly from 27% just one day prior.
Prominent economist Robin Brooks suggested that underlying stress within the artificial intelligence (AI) sector—which served as a primary catalyst for the recent sell-off in South Korean markets—may be influencing the Federal Reserve chair’s measured approach.
"Warsh gave no indication the Fed’s in any hurry to hike, so the October meeting is now pretty much off the table in terms of a hike," Brooks wrote in a public commentary note. He added that broader anxieties regarding potential corrections in the technology sector are indirectly assisting the central bank by making investors far more receptive to a dovish policy message. "What’s helping the Fed is fears of an AI blow-up, which is making markets more receptive to a dovish message," Brooks noted.
US Bond Yields Eye Rebound as Stocks Halt Upside
Even as equities and digital assets found temporary footing, movement in the fixed-income market introduced new variables for macroeconomic strategists. United States Treasury bond yields began climbing as stocks attempted to stabilize, reviving longstanding debates over whether the US Treasury and the Federal Reserve may eventually be forced to choose between actively cooling an aggressive bond market sell-off and maintaining upward momentum in risk assets.
The yield on the benchmark US 10-year Treasury note stood at 5.07% on Friday, having earlier attempted a more aggressive upward reversal that briefly pushed the rate as high as 5.13%.
Market commentary from analysts at The Kobeissi Letter highlighted that broader equity market weakness has historically served as the primary source of relief and correction for surging bond yields since August. In a detailed social media analysis published earlier in the week, the commentary suggested that equities might currently be trapped within a paradoxical "bull-bear" market dynamic.
According to the analysis, ongoing geopolitical tensions, including references to a US-Iran conflict, have weighed heavily on investor sentiment; without these external pressures, traditional stock indices would likely be trading at significantly higher valuations. Furthermore, persistent domestic inflation metrics have continued to drive sustained investor demand for tangible asset exposure—even as the central bank navigates the complexities of a renewed rate-hike cycle.
"Even as the S&P 500 hits year #5 of its bull market, we believe a steep discount is currently priced into equities. This discount has functioned as a ‘stealth’ bear market, suppressing equity valuations in the world’s largest and fastest-growing companies," the commentary concluded. The analysis added that this peculiar macroeconomic backdrop carries the potential to catalyze a sharp, violent relief rally in the S&P 500 if and when those prevailing risk factors are ultimately priced out by the broader market.