Recent price gains in Bitcoin (BTC) do not yet reflect a robust influx of fresh capital entering the digital asset market, according to comprehensive onchain analysis. While the leading cryptocurrency continues to test key psychological and technical resistance levels, market researchers emphasize that current price momentum is being driven largely by existing participants rather than external institutional or retail expansion.
In the latest edition of its regular weekly newsletter, The Week Onchain, prominent crypto research platform Glassnode highlighted that seasoned market participants are currently backing the lion’s share of Bitcoin’s recent upside attempts. The findings shed light on the mechanics behind Bitcoin’s valuation growth, pointing to a distinct divergence between newly introduced capital and overall network capitalization metrics.
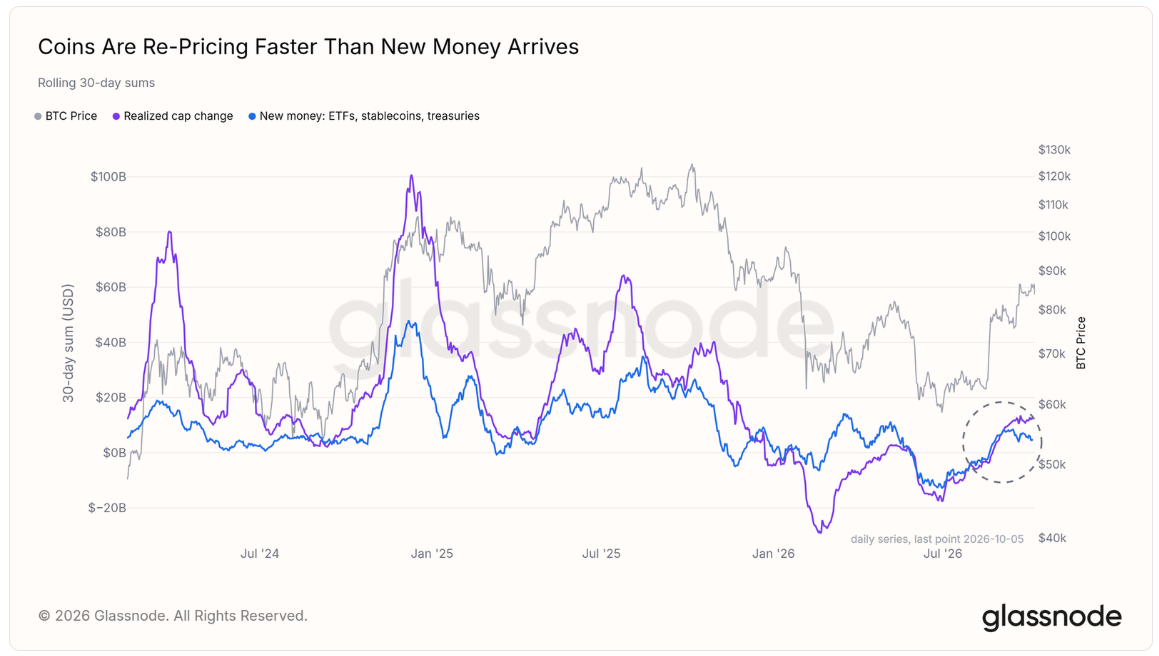
According to Glassnode, "new money" inflows into the Bitcoin ecosystem—encompassing purchases by corporate treasuries, broader stablecoin growth, and net inflows into United States-based spot Bitcoin exchange-traded funds (ETFs)—totaled approximately $4.9 billion during the 30-day period leading up to October 5.
However, over that exact same timeframe, Bitcoin’s realized cap grew by a staggering $12.8 billion, representing more than twice the volume of identified fresh capital inflows. The realized cap is a widely respected onchain metric that values each individual coin in circulation at the exact price it was last moved on the blockchain, offering a more nuanced view of capital distribution than simple market capitalization.
"New money therefore covers less than two fifths of that rise. The rest is coins changing hands at higher prices among money already in the market," Glassnode noted in its publication.
Accompanying historical data illustrates that recent rallies in the BTC/USD trading pair have exhibited a similar structural divergence ever since the landmark launch of US spot Bitcoin ETFs in January 2024. Nevertheless, macro and market conditions differ visibly at this juncture, with incoming liquidity remaining relatively modest when weighed against short-term realized-cap gains.
"The rallies of 2024 and 2025 showed a similar mix, but on far larger inflows," Glassnode added, underlining the dependence of the current market cycle. "Until those inflows pick up, the move depends on existing holders paying more."
Newer Investor Profit-Taking Surged at $85,000
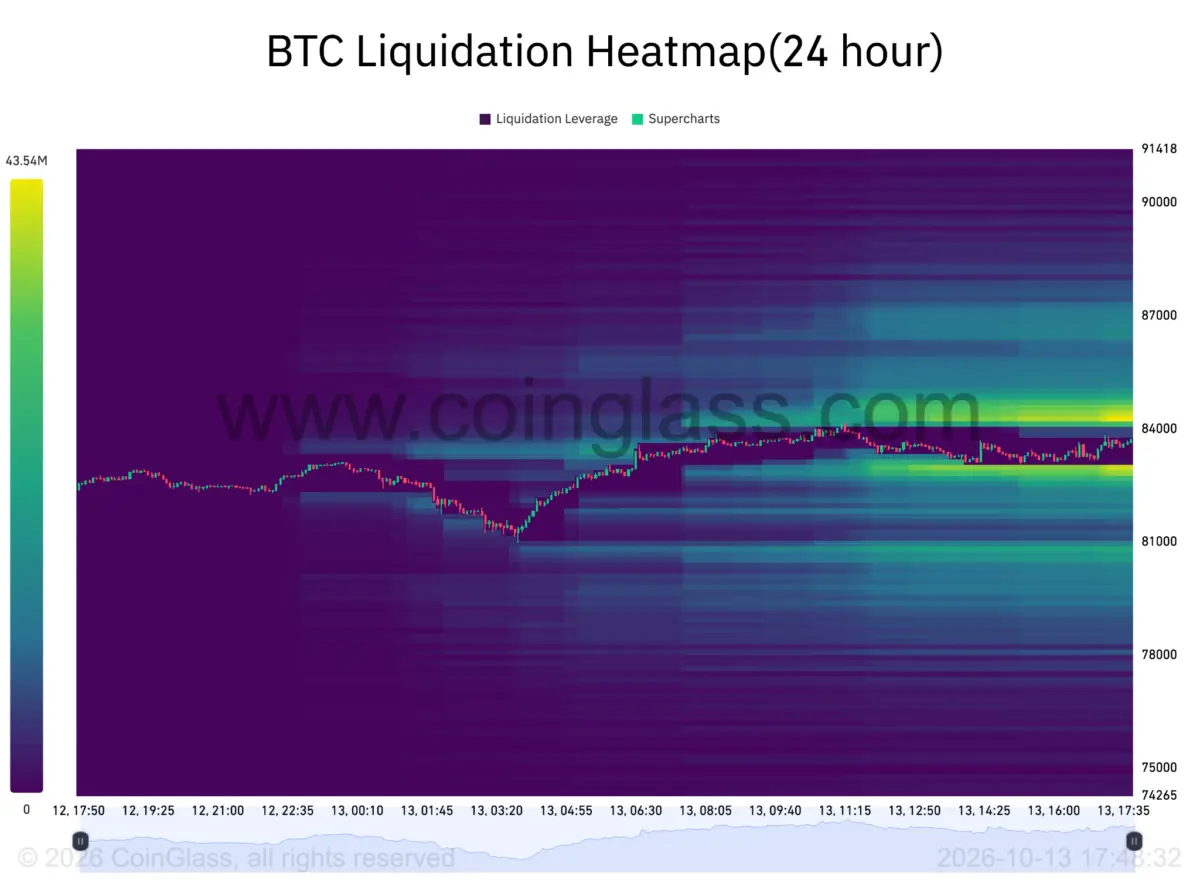
The friction between stagnant external inflows and aggressive internal trading activity has played out vividly on exchange order books in recent weeks. Since September 21, Bitcoin has made four distinct attempts to break through the stubborn $87,000 resistance ceiling. Each of these breakout attempts ultimately faltered as buyers encountered thickening overhead ask liquidity on major centralized exchange order books. Consequently, the BTC/USD pair hovered near the $83,000 mark, logging a modest 1% decline on a month-to-date basis.
This sideways consolidation and resistance test coincided with a broader macroeconomic backdrop, which included downward pressure on risk assets and a brief slide to an October low amid resurgent bond sell-offs driven by geopolitical nerves in the Middle East.
Amid this choppy price action, Glassnode highlighted a sharp escalation in profit-taking behavior among recent market participants. This wave of realization occurred notably over the weekend when Bitcoin achieved its first weekly candle close above the $85,000 threshold since January.
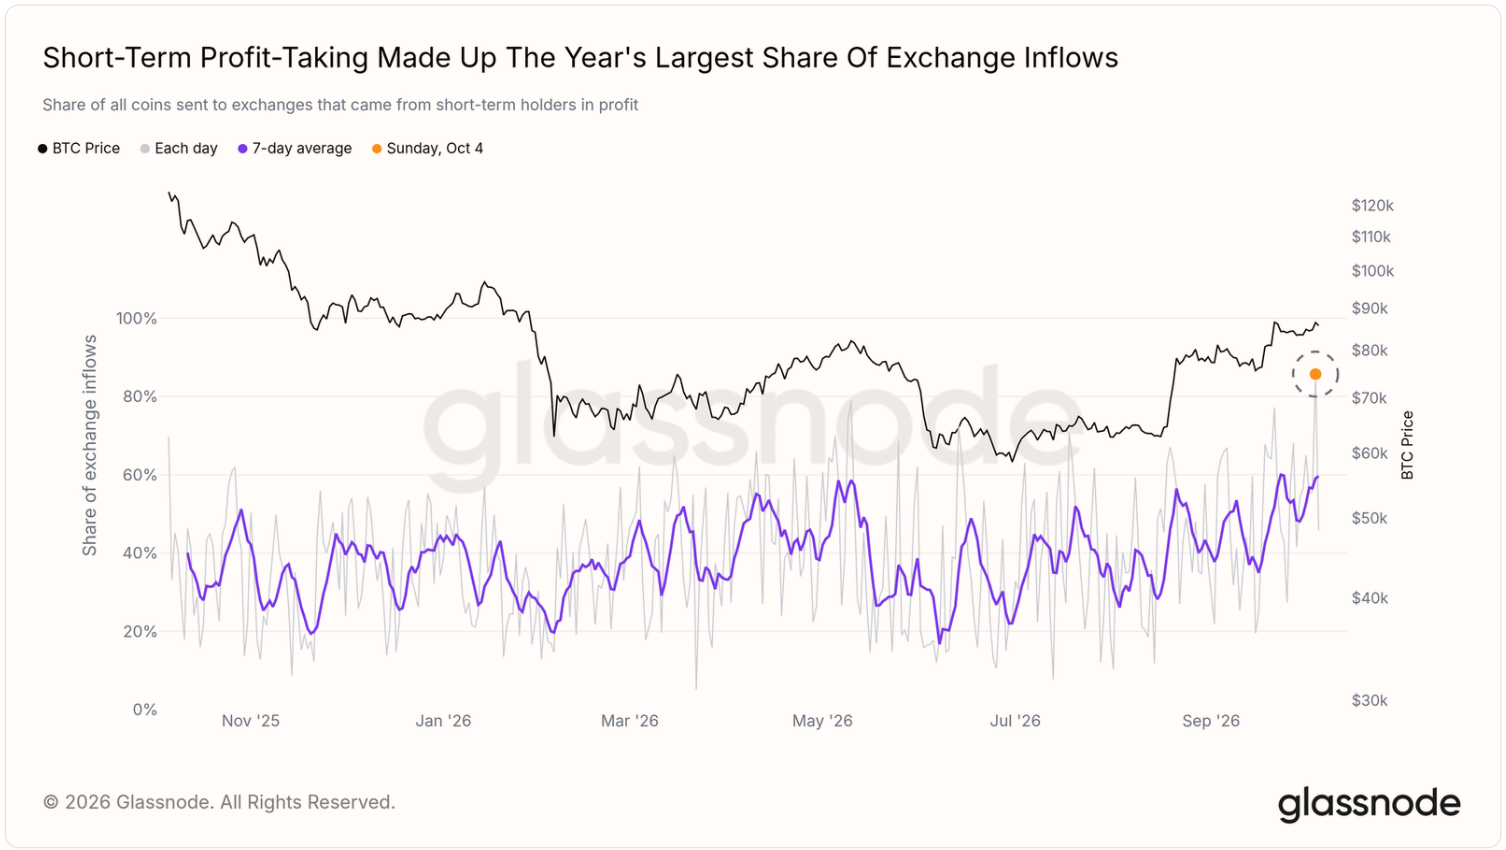
"Of all the coins sent to exchanges that day, about 86% came from short-term holders, those holding for less than 155 days, moving coins at a profit. That is the highest share of any day in the past year; on a typical day it is under two fifths," the research platform detailed.
Short-term holders (STHs) are historically recognized within onchain analytics as being significantly more sensitive to short-term price fluctuations and macroeconomic sentiment than long-term investors or "hodlers." Despite their propensity to lock in gains during localized price spikes, this cohort remains collectively in a state of net profit. Data compiled by crypto analytics provider CryptoQuant indicates that the aggregate cost basis—commonly referred to as the realized price—for short-term holders sits at approximately $78,250.
As the market navigates the final quarter of the year, analysts continue to monitor whether incoming capital flows from corporate treasuries and spot ETFs will accelerate sufficiently to absorb ongoing profit-taking, or if Bitcoin’s trajectory will remain tethered to the purchasing power and conviction of investors already entrenched within the ecosystem.