The dream of capturing risk-free profits from price discrepancies across crypto exchanges appears to be largely an illusion, at least when it comes to tokenized equities. Recent execution studies and blockchain data analyses highlight that while tokens tracking Nvidia shares can trade at varying prices across different issuers and venues, attempting to profit by buying the cheaper version and selling the more expensive one leaves virtually no room for actual gains once execution realities are factored in.
Tokenized equities have grown increasingly popular as traders look for ways to bridge traditional financial assets with the around-the-clock liquidity of blockchain networks. Products tracking major equities like Nvidia allow participants to gain economic exposure without holding traditional brokerage accounts. However, the decentralized and fragmented nature of these offerings introduces complexities that traditional arbitrageurs must navigate carefully.
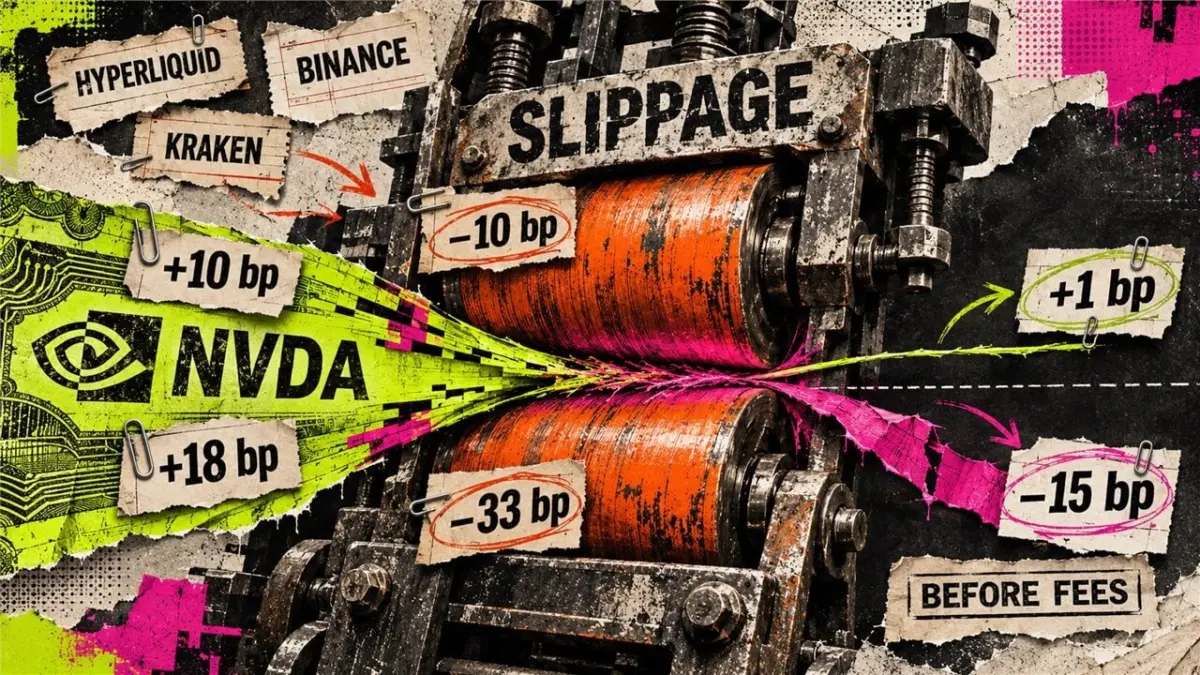
According to two modeled comparisons published by data provider Coin Metrics on November 3, visible price gaps between different tokenized Nvidia assets shrink dramatically by the time orders actually reach the market. The execution study analyzed $1,000 modeled comparisons running from June through November 2, 2026, revealing that entry and exit slippage routinely wipe out most or all of the gross price differentials before accounting for trading fees.
In the first modeled comparison, Coin Metrics evaluated buying Hyperliquid NVDAx against selling Binance NVDAb. This setup initially printed a gross price gap of 10 basis points. However, after factoring in 10 basis points of combined entry and exit slippage, the remaining profit margin shrank to just a single basis point before trading fees.
The second scenario proved even less forgiving. When modeling a trade that bought Hyperliquid NVDAx and sold Kraken NVDAx, an initial gross gap of 18 basis points faced a heavy 33 basis points of entry and exit slippage. This resulted in a negative 15-basis-point gap before trading fees were even applied.
These findings underscore a fundamental challenge in digital asset markets: theoretical price gaps seen on order book screens frequently evaporate under real-world execution conditions. For an arbitrage strategy to succeed, a trader must not only identify a price disparity but also ensure they are comparing identical share exposure, possess the specific asset required to execute the sale on the expensive side, and qualify for the exact routing needed to settle the trade.
Adding to the complexity, the underlying tokenized-equity framework known as xStocks announced NVDAx/USDC spot trading on HyperCore back on August 10, operating separately from equity perpetuals. Moving these spot tokens to or from HyperEVM requires a process of wrapping and bridging. Consequently, venue labels on charts alone do not automatically establish that a clean transfer route exists for every observation within a given historical sample.
One Stock, Different Routes and Complex Mechanics
A separate dataset released by blockchain analytics firm Bitquery further demonstrates why clean-looking price comparisons can be deceiving. In a correction published on November 1, Bitquery normalized its tracking Nvidia tokens per underlying share and adjusted how dividend treatments are factored into the equations.
Across Bitquery’s public-pool sample spanning from September 15 to October 13, pairwise median daily gaps among the four most actively traded versions of the token rounded to no more than 0.12%. The widest price pair identified in the sample reached 0.1225%, which rounded to 0.12%.
Explaining the mechanics behind these valuations, Kraken’s multiplier guidelines show that dividend reinvestment can actively increase the share exposure represented in a user’s xStock balance while the actual number of on-chain tokens remains completely unchanged. For wrapped xStocks, the issuer explicitly notes that token prices must be adjusted dynamically using its designated multiplier.
Furthermore, Bitquery pointed out that its tracked Nvidia tokens operate on separate smart contract architectures without any direct on-chain bridge or issuer-supported swap mechanism between them. This means that purchasing the cheaper product on one venue does not supply the specific token required to fulfill the sale on another, effectively breaking the traditional arbitrage loop.
Trading costs across different venues also eat into any theoretical margins. Kraken’s Pro spot order book features a fee schedule that lists a 10-basis-point taker fee alongside a two-basis-point maker rebate. Purchases made directly through applications using US dollars or USDG typically carry no direct trading fee, though they may incorporate an underlying spread, while conversions involving xStocks carry a 1% fee.
Meanwhile, accessing the issuer’s primary-market documentation involves strict compliance hurdles, including mandatory onboarding, rigorous identity verification, and anti-money laundering checks, alongside the requirement to use whitelisted wallets. The issuer’s cash Market Flow setup enforces a $5,000 minimum transaction size, operates 24 hours a day, five days a week, and currently lists its issuance fees at zero.
Jurisdictional limitations further restrict who can participate in these markets. Kraken explicitly excludes US persons, as well as customers residing in the United Kingdom, Canada, and Australia, from accessing xStocks. While compatible-wallet withdrawals are fully supported, direct transfers back into a traditional brokerage account are not permitted.
Crucially, the issuer classifies xStocks strictly as tracker certificates designed to provide economic exposure rather than direct share ownership or underlying voting rights. Ultimately, any usable margin for traders depends entirely on executable prices for matching exposure, the combined costs of both legs of a trade, and the operational capability to deliver or sell the specific instrument in question.