French members of parliament have advanced a controversial legislative proposal that would alter how digital asset transactions are taxed, introducing a tax event for specific crypto-to-crypto swaps while simultaneously blocking extended relief for historical trading losses.
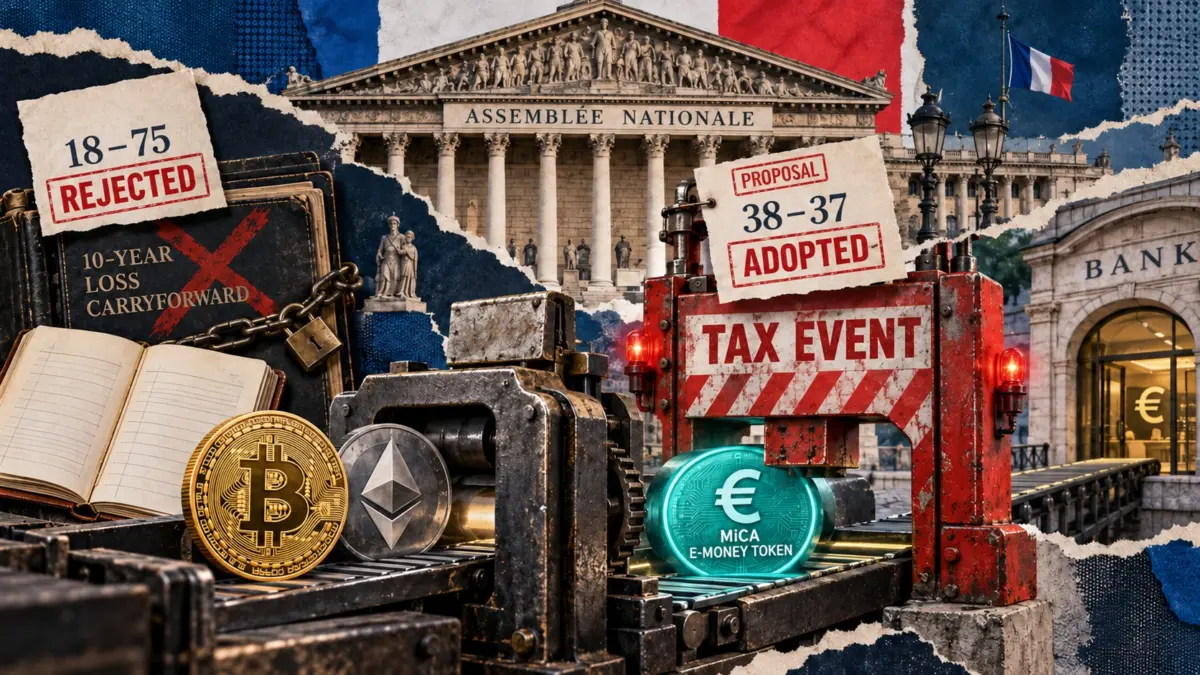
During the first-reading votes on October 16, the National Assembly narrowly approved an amendment to the 2027 finance bill that targets swaps involving certain stablecoins. The decision marks a significant shift in France’s regulatory and tax landscape for digital asset investors, pulling the timeline for tax recognition forward even when individuals convert their holdings without cashing out into traditional fiat currency. At the same time, lawmakers decisively voted down a separate measure that would have established a ten-year carryforward window for accumulated crypto losses, leaving current restrictions firmly in place.
The initial budget deliberations and subsequent provisional texts place the stablecoin provision squarely within Article 4 octies. If the broader finance bill successfully navigates the remaining legislative hurdles and receives final enactment, the new tax framework is slated to take effect on January 1, 2027.
A Tax Event Before Cash-Out Includes Stablecoins
Under the current legal framework governing private digital asset investors in France, standard crypto-to-crypto exchanges typically benefit from a tax deferral mechanism. As long as a trade does not involve a cash balancing payment—commonly known as a soulte—holders can rotate their exposure between different digital assets without triggering an immediate, taxable capital gain event in the year the exchange occurs. This deferral has long provided flexibility for investors navigating volatile market cycles, allowing them to adjust their portfolios without constantly calculating and paying short-term tax liabilities to tax authorities.

Amendment I-3898 disrupts this established deferral mechanism by removing protections when a holder receives specific regulated assets, namely MiCA e-money tokens or related rights. Originating from the European Union’s sweeping Markets in Crypto-Assets regulation, e-money tokens are formally defined as crypto-assets that seek to maintain a stable value by referencing the official currency of a single jurisdiction, effectively operating as fiat-pegged stablecoins within the digital ecosystem.
The implications of this policy shift are substantial for everyday market participants. For instance, if an investor holding appreciated Bitcoin or Ethereum decides to mitigate market downside by converting those assets into a qualifying stablecoin to shelter value, that strategic portfolio adjustment would immediately trigger a taxable capital gain. This liability would arise despite the proceeds remaining entirely within the digital asset ecosystem and never touching a traditional bank account or converting into physical euros.
The mechanism for calculating these gains focuses on the surplus value above the original acquisition cost, accounting for properly documented transaction fees. To streamline this process, the proposed legislation looks to replace portfolio-wide cost allocation methods with a more localized basis for disposed assets, utilizing a weighted-average acquisition cost for assets of the same kind that were purchased at varying price points. Furthermore, taxable swaps would reset the acquisition basis for the newly received assets, whereas deferred transactions would carry the original basis forward.
For holdings acquired prior to the projected 2027 implementation date, taxpayers would retain the option to use documented actual acquisition costs or irrevocably allocate their existing portfolio acquisition cost across all holdings based on their respective market valuations as of December 31.
Rejection of Ten-Year Loss Carryforward Leaves Traders Exposed
While the narrow approval of the stablecoin tax provision increases potential tax burdens for active traders, the National Assembly concurrently rejected a separate legislative effort that aimed to offer broader tax relief for market participants experiencing downturns.
Amendment I-3653 sought to introduce a ten-year carryforward period for unused qualifying crypto losses, a reform that proponents argued would bring digital asset taxation closer in line with traditional financial instruments and equities. However, lawmakers firmly rebuffed the measure, ensuring that the existing framework governing losses remains entirely unchanged.
Under current guidelines enforced by France’s tax authority, individuals are permitted to offset crypto losses against crypto gains realized exclusively within the same tax year. Crucially, any net losses remaining at the end of the tax cycle cannot be carried forward into subsequent years, nor can they be utilized to offset capital gains generated across entirely different asset categories, such as real estate or traditional securities.
The combination of these legislative actions creates a challenging environment for French digital asset investors. Because the stablecoin swap tax was advanced while the loss carryforward reform was defeated, traders who face immediate tax liabilities on stablecoin conversions will remain unable to offset those gains against net losses accumulated during prior tax years.
As the 2027 finance bill continues its progression through the legislative process, the ultimate fate of the stablecoin provision rests on the final enacted text. Market participants and tax professionals alike are closely monitoring the budget’s evolution to determine how the regulatory adjustments will reshape investment strategies across the French digital asset sector.