Decentralized finance lending giant Aave has officially adjusted its interest rate model parameters for Tether’s USDT on its Ethereum Core market. The protocol has lowered the utilization threshold—commonly referred to as the kink—at which borrowing rates begin to climb steeply. This structural adjustment is designed to make loans more expensive earlier in the utilization cycle as overall pool liquidity tightens.
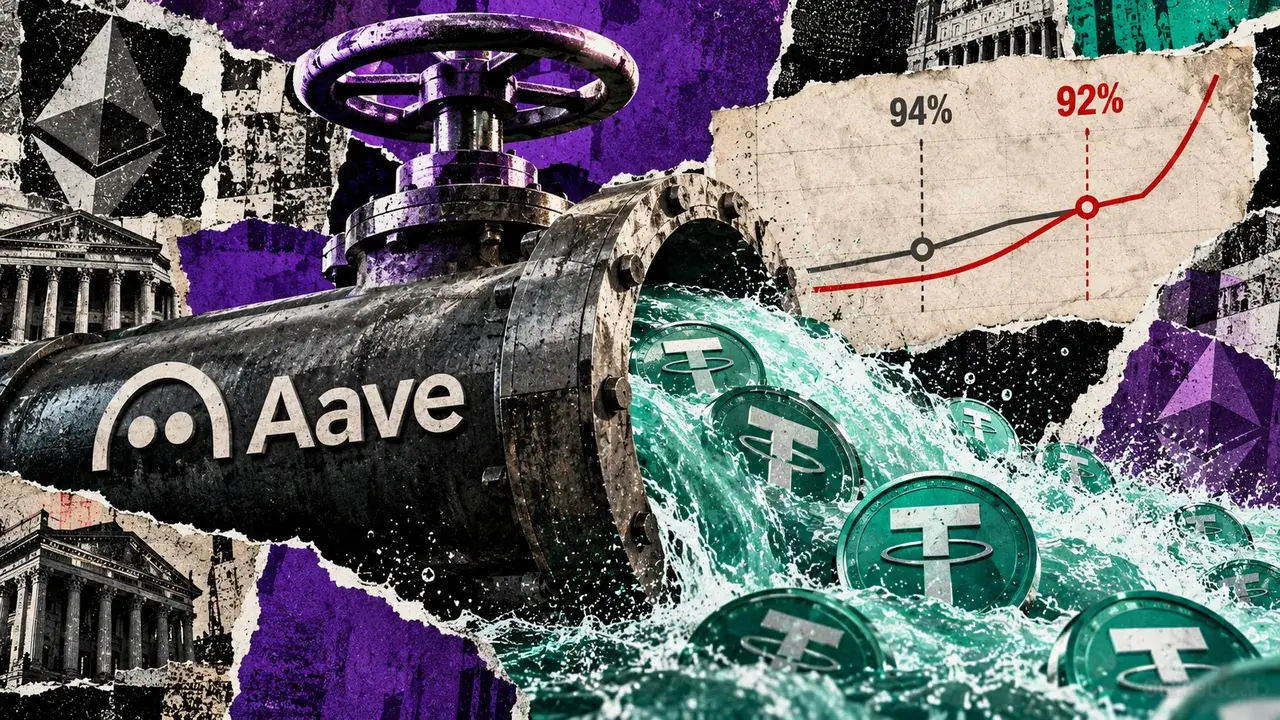
The modification was executed on Oct. 21 at Ethereum block 26,241,799, directly following a formal risk recommendation published on Oct. 20 by decentralized finance risk service provider LlamaRisk. Under the previous parameter settings, the optimal utilization ratio sat at 94%, representing the share of borrowed pool liquidity before penalty-level interest rates kicked in. With the new implementation, that threshold has been lowered to 92%.
While borrowers retain the technical ability to push utilization past this newly established 92% ceiling, the associated borrowing costs escalate much more sharply once that line is crossed. The primary trade-off for liquidity lenders is an earlier introduction of upward pressure on borrowers, which in turn helps preserve essential withdrawal headroom within the pool. The intended cash cushion remains accessible to be borrowed or withdrawn, but the protocol’s underlying economic incentives now encourage responsible pool utilization well before liquidity runs critically thin.
The Price of Earlier Withdrawal Headroom
Aave relies on a sophisticated two-slope interest rate model to govern its lending pools. This model increases borrowing rates in a gradual, linear fashion up to an optimal utilization point, or kink. Once utilization surpasses that optimal point, the rate climbs much more aggressively between the kink and full 100% utilization. By lowering the kink from 94% to 92%, the protocol effectively shifts the steeper, more expensive segment of the interest rate curve forward, compelling borrowers to face higher costs earlier when demand for capital surges.
According to on-chain data for the deployed USDT parameters recorded at the Oct. 23 block, the updated configuration features a 92% optimal usage ratio, a zero base rate, a 4.5% first slope, and a 10% second slope. These exact settings fix the borrowing rate at the kink to 4.5% Annual Percentage Rate (APR), while driving the maximum rate at 100% full utilization up to 14.5% APR.
Comparing the old and new curves at identical utilization levels highlights the immediate cost difference introduced by the change. At a hypothetical 94% utilization rate, the prior curve sat precisely at its kink, charging borrowers 4.5% APR. Under the newly implemented curve, however, that exact same 94% utilization sits two percentage points deep into the eight-point range residing above the lowered kink.
Calculating this conditional comparison involves taking the base 4.5% rate at the kink and adding the product of the 10% second slope multiplied by two-eighths, resulting in a 7% APR. This calculation represents a conditional comparison at identical utilization rates, independent of the observed 4.23% borrowing APR recorded in the live market on Oct. 23.
To put the financial impact into perspective for market participants, consider a constant 1 million USDT loan. A 2.5% rate gap between the old and new models would translate to an additional 25,000 USDT in simple annual interest over the course of a full year, provided that both modeled rates and the underlying principal remain completely unchanged throughout that period.
Despite the steeper curve, the 92% threshold does not impose a strict ban on borrowing above that level, nor does the curve’s 14.5% endpoint guarantee that lenders will invariably find cash available for immediate withdrawal.
In its Oct. 20 recommendation report, LlamaRisk noted a total supply of 2,892.2 million USDT in the pool. Assuming that aggregate supply remains entirely fixed, a reserve operating at the older 94% utilization rate would leave 6% of the pool unborrowed, whereas a 92% utilization rate leaves a slightly higher buffer of 8% unborrowed.
When translated into absolute token amounts based on that fixed supply, these percentages correspond to 173.53 million USDT and 231.38 million USDT of unborrowed liquidity, respectively. The difference between these two figures amounts to roughly 57.84 million USDT in additional modeled unborrowed liquidity at the threshold. This variance simply illustrates the difference between two distinct modeled operating points evaluated on the exact same supplied balance.
LlamaRisk also reported approximately 417 million USDT already sitting idle during its initial recommendation when overall market utilization hovered comfortably below either kink. However, the updated rate parameters fundamentally change the economic terms under which active borrowers consume available liquidity. For this larger modeled buffer to successfully manifest as actual, physical cash within the pool, users must react dynamically through standard market cash flows.
As external funding grows increasingly expensive, individual borrowers may choose to repay their outstanding loans, while liquidity suppliers might find the newly enhanced interest rates attractive enough to deposit additional USDT into the market. Alternatively, borrowers can simply absorb the higher costs, while suppliers may decide to withdraw their capital before any fresh inflows arrive. The revised interest rate curve inherently encourages these behavioral responses without dictating their exact size or timing.
Cash Still Controls a Supplier’s Exit
Examining the hard on-chain data from a subsequent operational snapshot provides a clearer picture of the reserve’s health. At block 26,254,517, timestamped on Oct. 23 at 09:45:59 UTC, the Aave reserve held approximately 2.9 billion USDT in total outstanding supplier claims alongside 2.5 billion USDT in active variable debt. Concurrently, the physical USDT held directly within the underlying aToken contract stood at approximately 391.4 million tokens.
To understand how the protocol evaluates these metrics, it is helpful to distinguish between physical supplier claims, the reserve’s physical token balance, and its internal virtual accounting balance. The virtual accounting balance serves as a specialized input utilized directly by the protocol’s interest-rate strategy contract. By dividing total variable debt by the sum of debt plus that virtual balance, the protocol’s underlying borrow utilization is calculated at approximately 86.45%, which safely rests below the newly enacted 92% threshold. Meanwhile, physical cash measures the actual tokens securely held in custody, while the virtual figure dictates the mathematical pricing calculations.
That same Oct. 23 snapshot recorded a variable borrowing APR of approximately 4.23% alongside a supplier liquidity APR of 3.29%. It is important to note that the cash balance observed on Oct. 23 is a later market observation and is entirely separate from LlamaRisk’s Oct. 20 predictive model, meaning it does not directly establish a direct causal effect of the rate change on subsequent deposits, repayments, or withdrawals.
The protocol’s internal strategy calculates the supplier liquidity rate directly from the overarching borrowing rate and the specific share of liquidity being actively utilized, adjusted downward by the established reserve factor. During the Oct. 23 snapshot, that reserve factor was maintained at 10%, effectively allocating a specific portion of the generated borrowing interest directly to the decentralized protocol treasury.
Consequently, a higher borrowing rate can improve the returns offered to liquidity suppliers, helping compensate them adequately for keeping their funds locked within the pool. Nevertheless, accrued interest is entirely distinct from physical underlying tokens becoming available for immediate withdrawal. Real cash must physically be present in the contract when a supplier initiates an exit.
Aave’s official withdrawal documentation makes this operational condition explicit: liquidity suppliers are only permitted to withdraw against capital that is genuinely available and unborrowed. Furthermore, a supplier who is actively utilizing their deposits as collateral to back an existing loan may also be required to repay portions of their borrowings or deposit additional collateral to preserve the overall health and safety of their position before any withdrawal can be successfully processed.
The cash reserves held within lending pools serve an operational purpose distinct from secondary financial backstops like the GHO conversion inventory or Umbrella deficit backstops. Ultimately, the true operational test for the protocol remains how incoming deposits and loan repayments stack up against ongoing borrowing activity and user withdrawals as overall market utilization fluctuates.
By shifting the optimal utilization kink down to 92%, Aave has ensured that borrowing costs respond much earlier to tightening market liquidity. Whether individual suppliers can execute immediate withdrawals still heavily depends on the actual cash remaining inside the pool and, for those whose deposits secure active loans, the ongoing health of their individual positions.