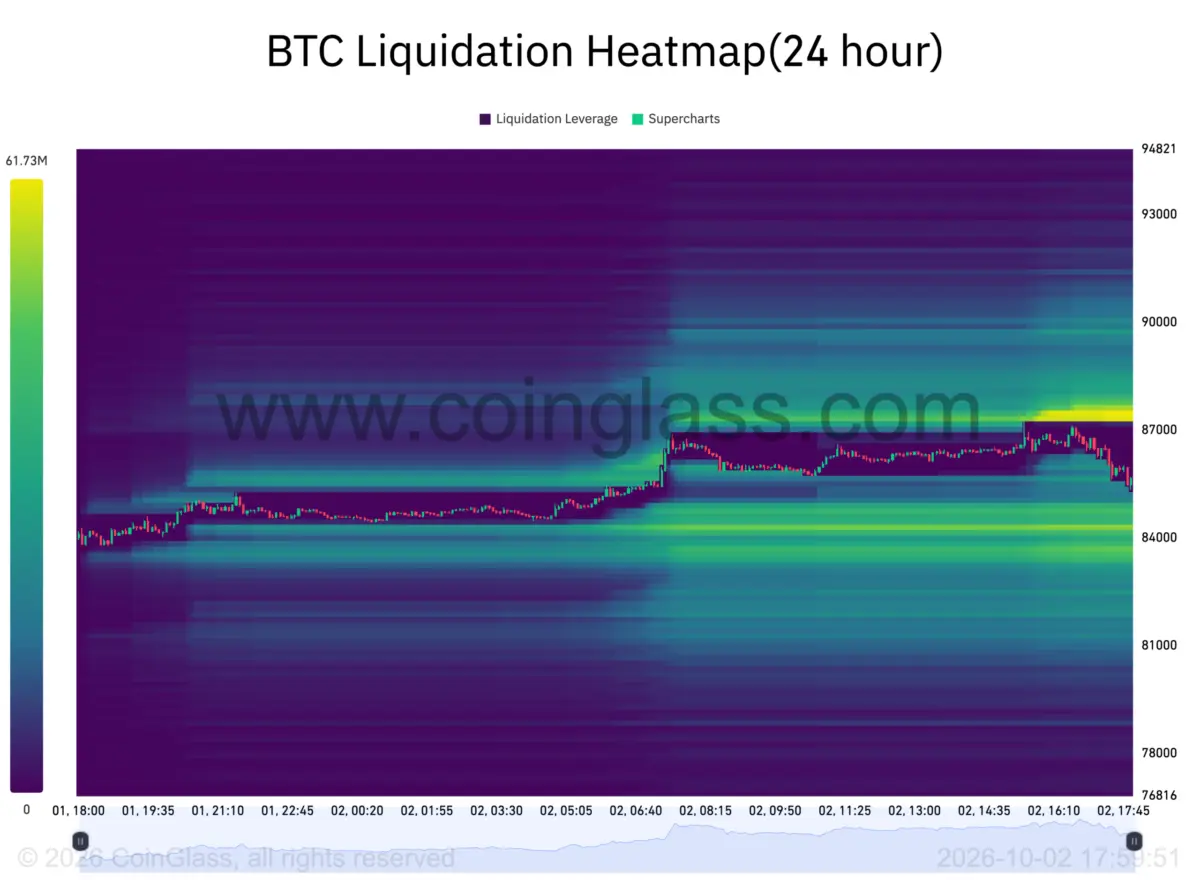
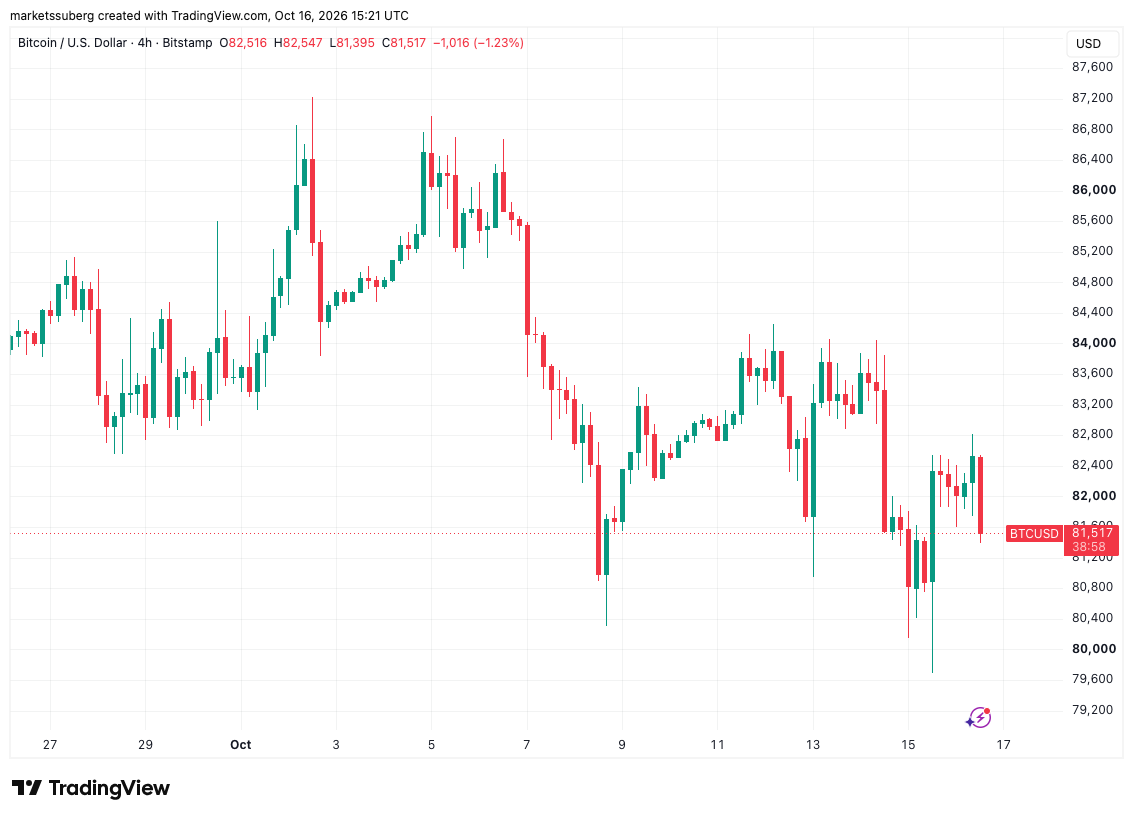
Bitcoin traded near $82,000 around Wall Street’s opening bell as cryptocurrency markets showed signs of stabilization, finding support alongside a notable rebound in South Korean equities.
According to market data from TradingView, the world’s leading cryptocurrency by market capitalization managed to hold the vast majority of its reclaimed ground after staging a sharp technical rebound from the $80,000 threshold during Thursday’s trading sessions. The preceding downward pressure on crypto assets had largely mirrored a bruising weeklong sell-off across South Korean technology stocks, which had rattled global risk sentiment.
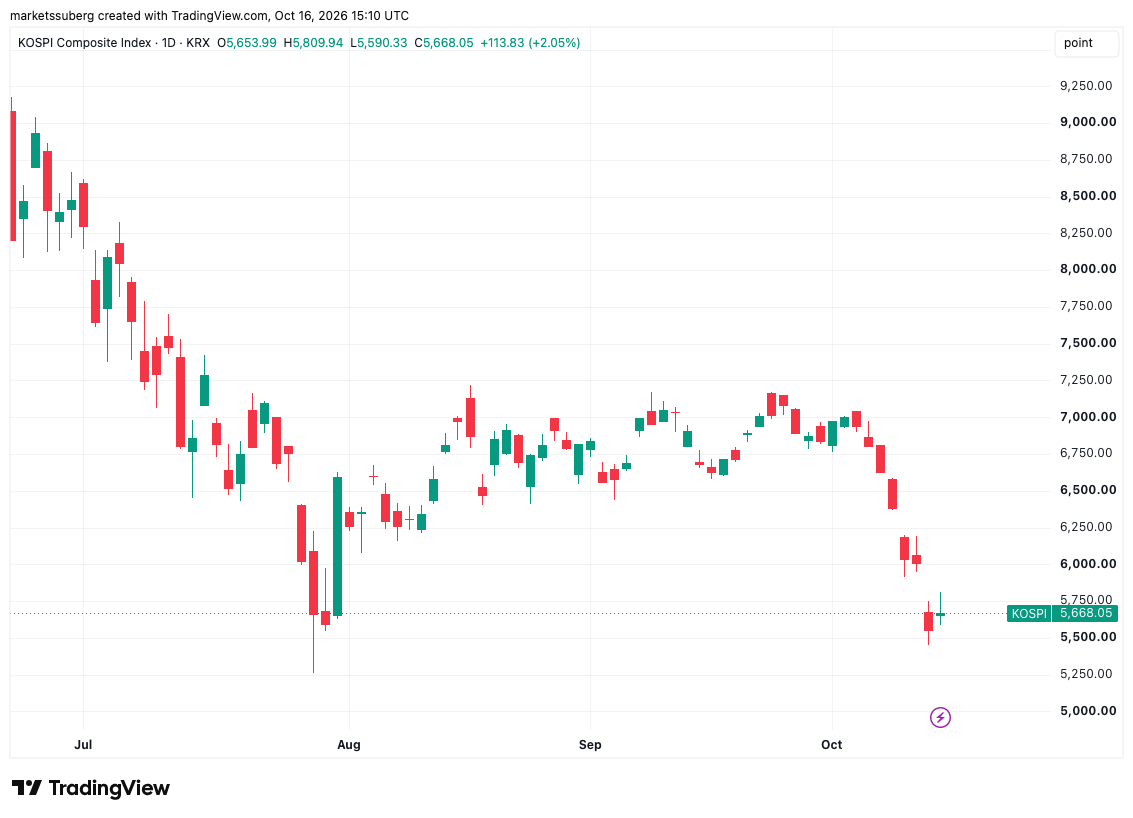
However, the late-week Asian trading session offered a degree of relief to investors. The KOSPI Composite Index managed to close out the session at 5,668, marking a 2% recovery on the day, though the index still finished the weekly period down by some 8.3%.
Meanwhile, United States equities largely managed to sidestep the broader contagion of the Asian market sell-off, though Wall Street indices turned in a mixed performance on Friday. The tech-heavy Nasdaq Composite Index drifted downward by 0.5%, while the broader S&P 500 managed a modest gain of 0.5% as investors parsed conflicting macroeconomic signals.
Traders See Dovish Edge to Federal Reserve Commentary
Providing a tailwind for risk-on assets, Federal Reserve Chair Kevin Warsh offered investors a measure of relief during a high-profile discussion with International Monetary Fund (IMF) Managing Director Kristalina Georgieva. During their dialogue, Warsh noticeably avoided making any hawkish remarks or mentioning potential further interest-rate hikes, adopting a measured stance that financial markets quickly dissected.
"I don’t prejudge meetings. I don’t believe in saying now what I might do at the meetings that we have in the balance of this year," Warsh stated during the event.
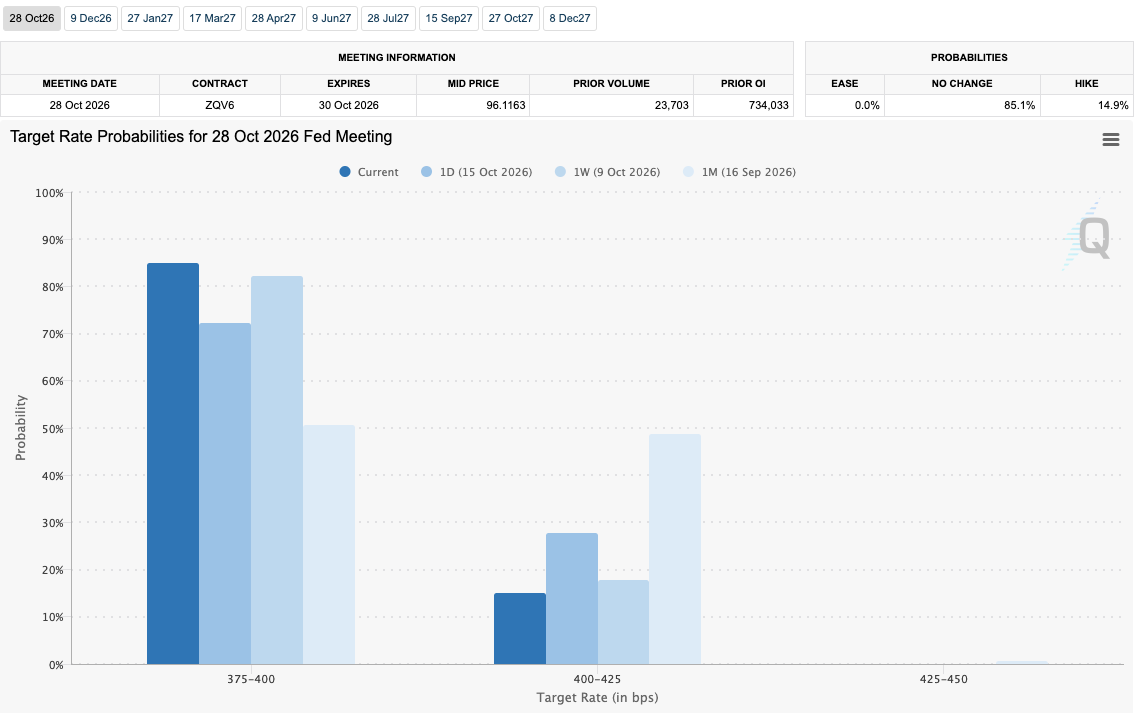
Market participants and currency traders quickly interpreted Warsh’s deliberate tone as a subtle dovish signal regarding the trajectory of future interest rates. This sentiment shift was rapidly reflected in derivatives and interest-rate futures data. According to the CME Group’s FedWatch Tool, the implied probability of the Federal Reserve enacting a 25-basis-point rate hike at its upcoming October Federal Open Market Committee (FOMC) meeting dropped sharply to 15%, down significantly from 27% just one day prior.
Macroeconomic observers suggested that underlying stresses in specific sectors may be influencing the central bank’s cautious communication strategy. Economist Robin Brooks pointed toward recent turbulence and stress within the artificial intelligence sector—a segment widely viewed as a primary catalyst behind the recent sell-off in South Korean technology shares—as a potential factor shaping the Federal Reserve chair’s aloof and flexible approach.
"Warsh gave no indication the Fed’s in any hurry to hike, so the October meeting is now pretty much off the table in terms of a hike," Brooks wrote in a detailed commentary published on his blog. He added a broader observation regarding current market psychology: "What’s helping the Fed is fears of an AI blow-up, which is making markets more receptive to a dovish message."
US Bond Yields Eye Rebound as Stocks Halt Upside
Away from the immediate spotlight on central bank messaging and cryptocurrency price action, traditional fixed-income markets displayed shifting dynamics. United States Treasury bond yields began edging upward as equities steadied, prompting renewed discussions among financial analysts regarding whether the US Treasury may eventually be forced into a difficult balancing act between taming an ongoing bond market sell-off and maintaining the underlying bullish structure of broader stock markets.
The benchmark US 10-year Treasury yield hovered around 5.07% on Friday, having earlier attempted a more aggressive upward reversal that briefly pushed the yield as high as 5.13%.
Market commentary from institutional analysis sources, including The Kobeissi Letter, highlighted that general weakness in equities has served as the primary source of temporary bond-yield corrections since August. In a detailed social media analysis published earlier in the week, commentators suggested that equities might currently be trapped within a paradoxical "bull-bear" market environment.
The analysis argued that without geopolitical pressures, such as the ongoing US-Iran conflict, global stock indices would likely be trading significantly higher. Furthermore, persistent domestic inflation metrics have continued to drive intense investor demand for hard asset and equity exposure, even as the central bank navigates the parameters of its monetary policy path.
"Even as the S&P 500 hits year number five of its bull market, we believe a steep discount is currently priced into equities," the analysis noted. "This discount has functioned as a ‘stealth’ bear market, suppressing equity valuations in the world’s largest and fastest-growing companies."
The commentary concluded by emphasizing that this suppressed valuation backdrop holds the underlying capacity to catalyze a sharp, aggressive rally in the S&P 500 if and when those macroeconomic and geopolitical factors are ultimately priced out of the broader market structure.