Researchers at the Bank for International Settlements (BIS) have published a comprehensive working paper highlighting deep complexities and discrepancies in how onchain cryptocurrency data is measured, analyzed, and interpreted. According to the study, estimates of Bitcoin onchain transfer values can vary by as much as sixfold depending entirely on the specific methodology used to measure transactions.
The finding focuses specifically on onchain Bitcoin transfer values, rather than speculative trading volume recorded on centralized cryptocurrency exchanges. This massive sixfold gap reflects fundamental differences between various measurement techniques, including how change outputs and other transfers back to the original sender are handled, aggregated, and interpreted by data analytics platforms.
The underlying data discrepancy stems largely from Bitcoin’s unique unspent transaction output (UTXO) accounting structure. When users spend Bitcoin on the blockchain, unspent funds are frequently returned to the sender as change. Under certain analytical frameworks, these change outputs can be counted as entirely separate transactions or distinct economic transfers, even though they merely represent funds returning to the original owner rather than being transferred to a different party.
"Metrics such as transaction volumes, market capitalisation and total value locked often suggest a degree of accuracy that is not supported by the nature of the underlying data," the researchers wrote in the BIS working paper, pointing out a potential illusion of precision in standard crypto analytics.
This measurement problem extends well beyond daily transfer values, influencing how the overall market evaluates Bitcoin’s macro standing. The researchers discovered that conventional market capitalization metrics have at times been calculated as up to four times higher than realized capitalization. Realized capitalization applies a different analytical lens by valuing each individual coin at the precise market price when it was last moved on the blockchain, stripping away lost coins and long-term dormant holdings from the headline figure.
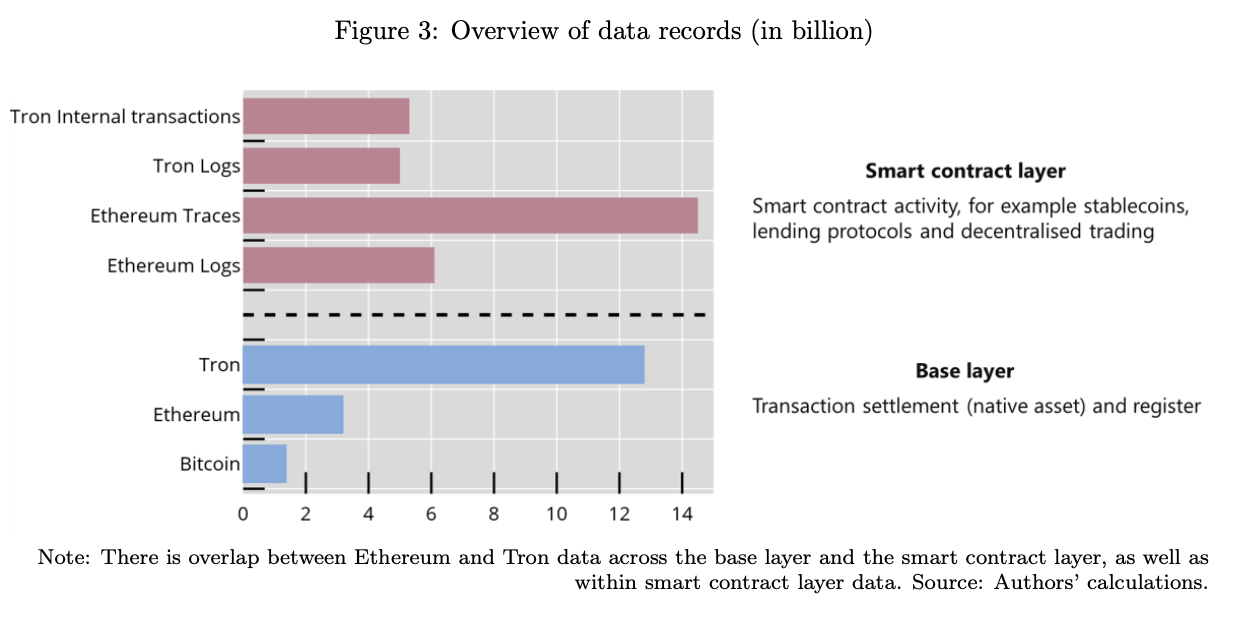
The study, which examined an immense dataset of 100 billion blockchain records spanning Bitcoin, Ethereum, and Tron, demonstrates that similar measurement and categorization challenges are systemic across the broader digital asset ecosystem.
Ethereum and stablecoins present additional challenges
While Bitcoin’s UTXO model introduces specific hurdles related to change outputs, Ethereum presents a completely separate set of analytical challenges primarily driven by the proliferation of complex smart contracts and decentralized finance (DeFi) applications.
Of approximately 67.5 million active smart contracts examined during the research period, about 54 million could not be easily categorized or labeled using the standardized classifications established within the study. This vast expanse of unclassified smart contract activity illustrates the difficulty of attributing clear economic intent to automated onchain operations.
Furthermore, interpreting stablecoin activity introduces another layer of nuance, as identical digital assets often serve entirely different utility purposes depending on the underlying blockchain network they operate on. For instance, the study found that Tether (USDT) circulating on the Ethereum network was much more closely linked to sophisticated DeFi activity, yield farming, and lending protocols. Conversely, USDT operating on the Tron network was predominantly associated with peer-to-peer payment-like functions and store-of-value use cases.
These network-specific behavioral differences were particularly stark when examining smart contract holdings. The share of USDT held directly by smart contracts on Ethereum exceeded 20% in 2022, compared with a meager 1% on the Tron network. Because stablecoins exhibit such vastly different use cases across distinct blockchains, the researchers warned that simply aggregating USDT transfer activity across multiple networks can heavily conflate entirely different types of economic activity, ultimately obscuring how stablecoins are actually being utilized by the global economy.
Ultimately, the BIS researchers concluded that traditional onchain indicators should be treated by regulators, economists, and market participants as "noisy approximations rather than direct measures of economic activity."
Visa filters stablecoin data to reflect economic activity
Recognizing these inherent data distortions, some financial institutions and analytics providers have already begun implementing advanced filtering mechanisms to distinguish between raw, unadjusted blockchain activity and tailored measures intended to accurately represent true economic value.
Visa’s Onchain Analytics dashboard, which is powered by data infrastructure from Allium Labs, provides a clear example of this approach. The dashboard prominently displays both total and adjusted stablecoin transaction volumes side-by-side to give users a clearer picture of actual market usage.
According to Visa, its adjusted methodology is specifically designed to strip away potential data distortions originating from high-frequency trading algorithms, automated bots, cross-chain bridge routing, and internal exchange operational transactions.
The Visa analytics dashboard currently illustrates the scale of this filtering process, showing roughly $6.4 trillion in total stablecoin transaction volume across the blockchain networks it tracks over a recent 30-day window, compared with a significantly lower $313.1 billion in adjusted volume.