“Tokenization is coming to America,” declared Robinhood chief executive Vlad Tenev after the United States Securities and Exchange Commission announced its landmark Innovation Exemption. The broader financial markets appeared to look quite kindly upon the development, responding with robust enthusiasm across major digital assets. Bitcoin (BTC) and Ether (ETH) surged by more than 10% in the immediate aftermath of the announcement, while Uniswap’s UNI token—representing a protocol increasingly viewed as prime real estate for potential tokenized stock trading—gained more than 30% in the days that followed.
While the securities regulator has indeed greenlit a pathway for tokenized stocks in the United States, industry observers note that the devil lies in the details. A vast majority of the existing stock tokens currently circulating in the digital asset economy fall well outside the strict boundaries of the commission’s new regulatory framework.
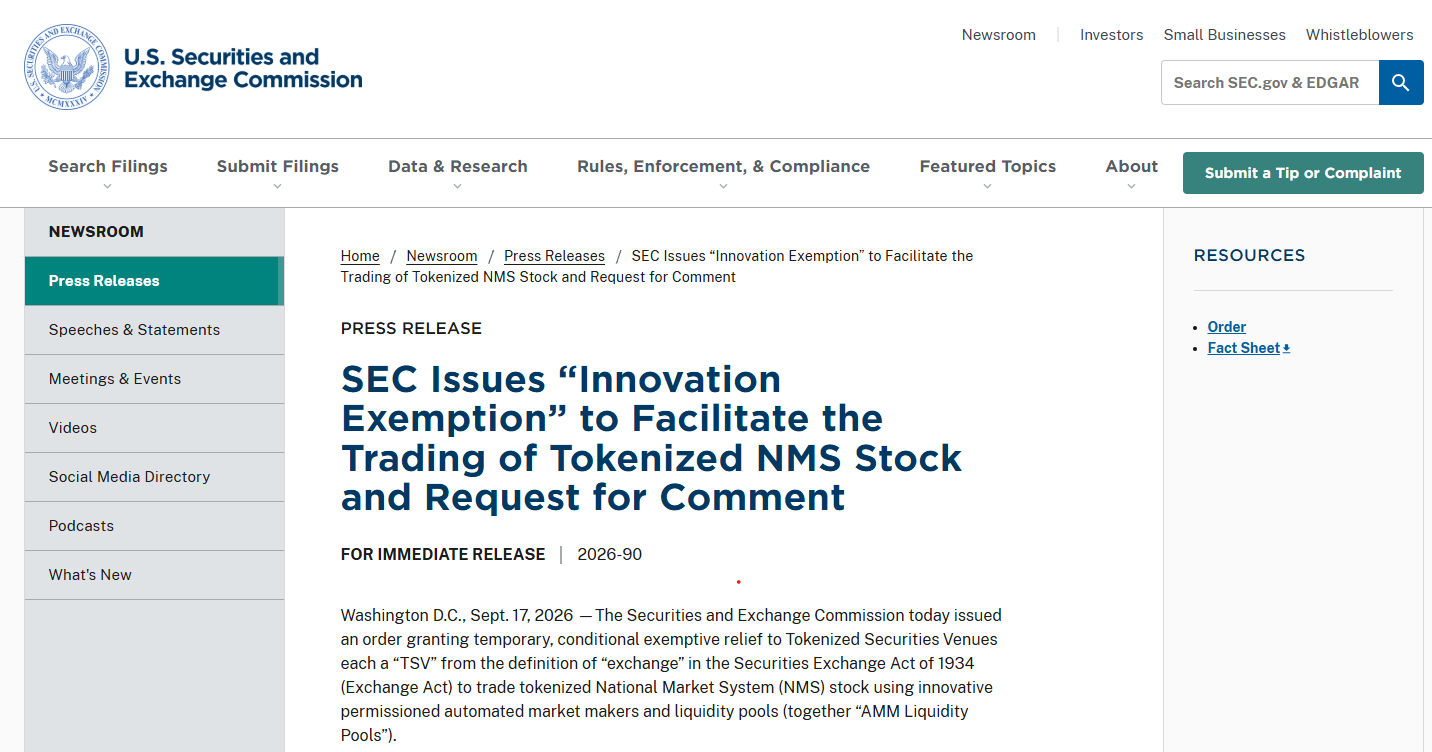
The regulatory body’s new five-year Innovation Exemption creates a formalized path for certain trading venues to facilitate the exchange of tokenized National Market System (NMS) stocks directly onchain without needing to register as a traditional national securities exchange. Furthermore, it allows third parties to tokenize equities, but this activity is strictly confined to a very specific set of conditions. Under the mandate, the resulting tokens must grant holders the exact same “rights and privileges” as the underlying shares, and the designated trading venues are required to implement permissioned user access and liquidity pools.
Not all tokenized stocks are created equal in the eyes of regulators. A digital token can easily mimic the appearance of a share and closely track its price movement without actually conveying the foundational shareholder rights of that share. Under the updated regulatory framework, any product fitting that description is classified as a synthetic stock, and it remains entirely non-compliant.
This regulatory reality means that some of the digital asset industry’s biggest players may already possess a structural head start, while others will inevitably find themselves forced to play catch-up. As Peter Curley, head of global regulatory affairs at Ondo Finance, noted when discussing the implications of the regulatory shift, not every existing strategy will fit the mold immediately, but the decisive action taken by the agency is what truly matters. Curley emphasized that the significance lies in the SEC taking concrete initiative rather than waiting indefinitely for Congress to complete comprehensive legislative action.
The SEC’s Tokenization Lane Is Narrow
The SEC order issued on September 17 grants certain trading venues temporary regulatory relief from the heavy burden of registering as traditional exchanges when they facilitate the trading of tokenized NMS stocks through permissioned Automated Market Maker (AMM) liquidity pools.
In practical terms, the federal agency has successfully carved out a defined lane for onchain stock trading. However, it is a remarkably specific lane, making the design and legal structure of the token just as important as the operational compliance of the trading venue itself.
To qualify fully under the exemption, a tokenized stock must ensure that token holders receive the exact same dividend distributions and voting rights as those attached to the underlying traditional security. While a third party is permitted to tokenize a stock without maintaining a direct affiliation with the original corporate issuer, the issuer is granted a specific opportunity to review and potentially reject the token before it is allowed to trade publicly.
This requirement effectively rules out synthetic exposure models, which delivers problematic news for existing offerings such as Robinhood’s Stock Tokens and Kraken’s xStocks in their current operational structures.
During the rollout, SEC Commissioner Hester Peirce stressed that the temporary exemption is purposefully tailored to accommodate one particular operational model rather than endorsing every conceivable method of trading tokenized securities. Nevertheless, she indicated that the commission remains open to considering alternative structures outside of the standard Tokenized Security Venture framework.
The Products Closest to the SEC’s Model
Certain market participants are already positioned quite close to the specific model envisioned by the SEC. Coinbase’s suite of stock tokens, for instance, sits comfortably in that general ballpark.
Earlier in September, Coinbase chief executive Brian Armstrong stated publicly that his company had successfully “set the standard” with its tokenized equities. He pointed out that these products are neither synthetic instruments nor debt obligations, but rather “real fully-backed securities, redeemable for the underlying shares, with dividends integrated,” alongside voting rights that are slated to arrive soon.
Despite this alignment, Coinbase’s current tokenized stock offerings are primarily targeted at non-US customers, and its core exchange infrastructure is traditionally engineered around a central limit order book rather than the permissioned AMM liquidity pools specified by the SEC exemption. However, given that Coinbase operates the Base blockchain network, the company retains significant architectural flexibility to adapt its offerings moving forward.
Meanwhile, Ondo Finance launched its own tokenized US securities offerings earlier in the year, utilizing a structure where the underlying shares are held securely in traditional institutional custody while the digital token explicitly represents the investor’s legal entitlement onchain.
Ondo also acquired Oasis Pro, a corporate entity that includes an SEC-registered broker-dealer, an Alternative Trading System (ATS), and a transfer agent. This combination provides the firm with comprehensive infrastructure bridging both traditional financial markets and the onchain ecosystem.
Curley observed that the SEC exemption explicitly favors the exact model that his firm has already proven out—one that is custodial, entitlement-based, and ensures real shareholder rights along with corporate actions passing seamlessly through to the end token holder. Even so, he cautioned that the firm is not operating under the assumption that all subsequent products will automatically clear regulatory hurdles without thorough review.
Both Coinbase and Ondo currently possess critical pieces of the technological and regulatory infrastructure that the SEC appears to desire. While neither company can safely assume its existing setup qualifies for the exemption without some operational fine-tuning, they likely face far less structural rebuilding than many of their industry competitors.
Uniswap’s Permissioned Pools Could Open the Door
Because the SEC exemption is meticulously designed around permissioned AMM liquidity pools, the development appears to present a notable opportunity for decentralized finance protocols like Uniswap.
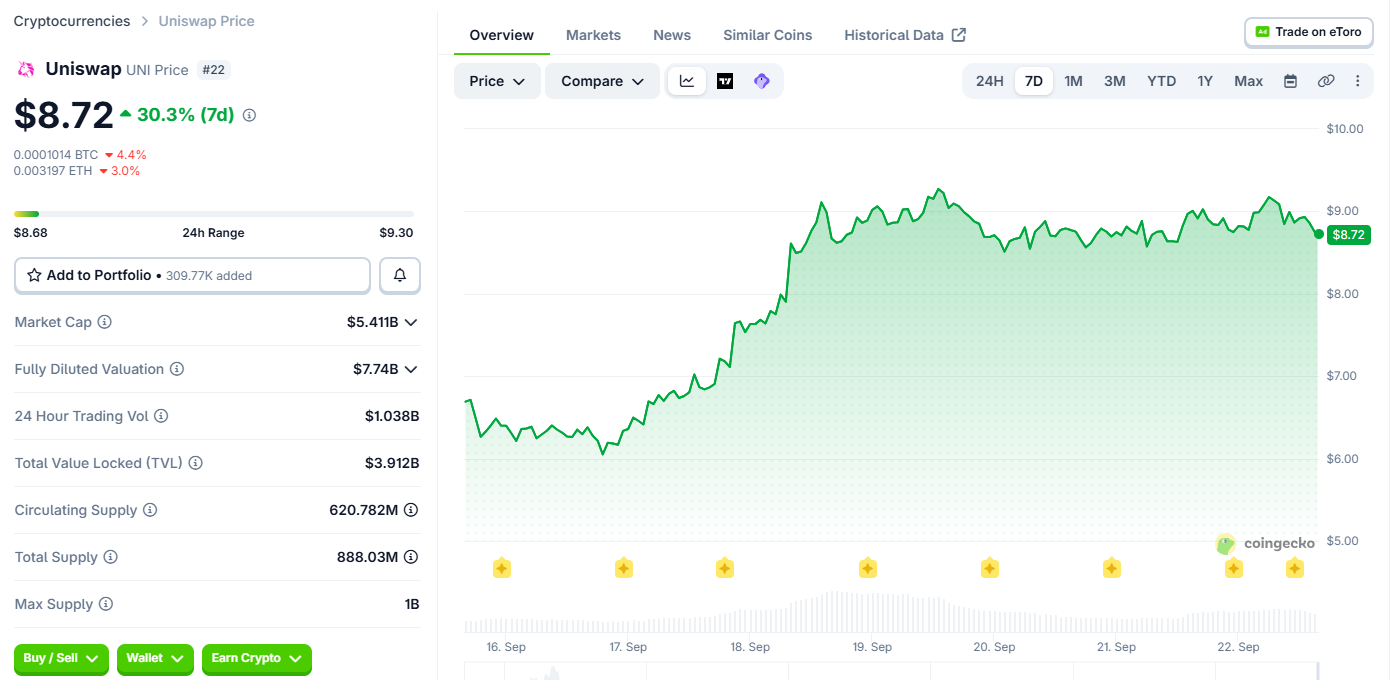
The protocol officially introduced Permissioned Pools as part of its v4 upgrade cycle, a feature specifically engineered to allow regulated assets to trade seamlessly through AMMs while enforcing compliance checks directly onchain.
While the implementation of this feature does not automatically transform Uniswap itself into a compliant trading venue under the SEC order, its v4 infrastructure could easily be utilized by specialized operators looking to build one. Because these permissioned pools give issuers granular control over who is permitted to trade or provide liquidity, the technical framework aligns closely with the regulatory requirements outlined by the commission.
Permissioned access of this nature typically requires strict adherence to Know Your Customer (KYC) verification protocols, robust record-keeping practices, public notices, and comprehensive transaction transparency.
If this decentralized technical infrastructure can be successfully bridged with the traditional shareholder rights and regulatory compliance mechanisms required for United States securities trading, Uniswap possesses an underlying framework that could well be adapted to fit the SEC’s newly established model.
Robinhood Has the Users, But Not the Right Product
Robinhood already boasts approximately 200 distinct stock tokens actively trading on its proprietary Robinhood Chain. Tenev has previously described this network as one-to-one backed and fully compatible with decentralized finance composability.
However, Jaewon Kim, head of research at Four Pillars, pointed out that the restrictive parameters of the SEC’s order explicitly exclude synthetic exposure. This exclusion effectively rules out prominent products such as Robinhood’s Stock Tokens and Kraken’s xStocks in their present formats.
Robinhood’s Stock Tokens are legally structured as tokenized debt securities issued by Robinhood Assets (Jersey) Limited. Consequently, they provide economic exposure mirroring the underlying equities, but they do not convey direct legal or beneficial ownership rights to the holders. Furthermore, these tokens are not registered under United States federal securities laws and remain unavailable to US persons.
Nevertheless, while Robinhood’s existing retail product does not neatly conform to the newly minted SEC guidelines, the company’s massive user distribution network and sophisticated blockchain infrastructure could provide it with a massive competitive advantage if management decides to adapt the product model to meet the updated regulatory requirements.
Kraken’s xStocks face a similar hurdle. Although they are fully backed by underlying equities, they similarly fail to grant holders the exact rights associated with conventional shares. Mere backing by physical shares, by itself, is not sufficient to qualify for the narrow scope of this specific exemption.
Bryan Choe, head of research and operations at digital asset market intelligence platform RWA.xyz, noted that while the majority of existing tokenized equity products are currently third-party sponsored, that dynamic is poised to shift dramatically over the coming year.
Expecting a significant transition toward issuer-sponsored models across the sector, Choe noted that the regulatory exemption effectively aligns token issuers directly with the original stock issuers, which could help establish greater operational balance across different issuance methodologies.
Five Years to Prove Tokenized Stocks Are Actually Better
The SEC has explicitly characterized the new exemption as a temporary measure. Chairman Paul Atkins emphasized that the five-year evaluation period will provide the broader financial market with ample breathing room to innovate and develop safely while the commission thoughtfully evaluates future rulemaking initiatives.
Beyond the race to determine which specific financial technology company will successfully launch the first fully compliant trading venue, the ultimate test for the industry will be whether tokenized stocks can genuinely capture meaningful market share and outpace traditional financial infrastructure.
As Curley highlighted, retail and institutional investors ultimately need to end up with a financial instrument that is demonstrably faster, cheaper, or functionally more useful than a conventional brokerage position. Skeptics have already raised legitimate questions regarding whether fragmented liquidity across various tokenized stock implementations will ultimately deliver competitive pricing or an optimal user experience.
The newly introduced regulatory exemption holds the theoretical potential to unlock continuous 24/7 trading, seamless fractional ownership, accelerated settlement cycles, onchain composability, and immutable shareholder rights. Yet, at the end of the day, these technological advantages will only matter if everyday market participants and institutions find tangible value in utilizing them.