ARLINGTON, Va. — The high-stakes legal battle over the future of prediction markets in the United States has reached a critical juncture, with the leadership of platform giant Kalshi expressing confidence that federal oversight will ultimately prevail over a growing patchwork of state-level challenges.
Speaking Wednesday at the prominent DC Fintech Week event near Washington, Kalshi CEO Tarek Mansour addressed the unfolding jurisdictional war, arguing that the ultimate outcome will not simply decide whether the rapidly expanding industry is regulated by local authorities or a federal watchdog. Instead, Mansour framed the existential clash as a stark choice between allowing federally supervised prediction markets to flourish within the United States or driving the entire multi-billion-dollar ecosystem offshore into unregulated international waters.
"We feel pretty good about where we stand overall," Mansour told attendees during his conference appearance, referencing the pending legal showdown that has captured the attention of traditional finance, federal regulators, and major sports leagues alike.
The controversy centers on event-contracts platforms that allow users to buy and trade contracts based on real-world occurrences, ranging from macroeconomic indicators and political elections to the outcomes of major sporting events. In recent years, prediction markets have experienced explosive growth, drawing massive retail and institutional trading volumes. However, this rapid expansion has collided head-on with state-level gambling and wagering regulators.
A growing coalition of U.S. states has aggressively challenged Kalshi and competing prediction market platforms in court. These state regulators argue that event contracts tied to athletic competitions and other outcomes amount to illegal sports wagering that circumvents local laws and properly belongs under the strict authority of state gambling commissions.
In response, Kalshi—alongside its primary federal regulator, the Commodity Futures Trading Commission (CFTC)—has mounted a vigorous defense in federal courts. Both the exchange and the federal agency maintain that the CFTC serves as the appropriate and sole regulatory watchdog for prediction markets, classifying the instruments as legitimate financial derivatives rather than traditional localized gambling.
The legal dispute has steadily escalated through the American judicial system, winding its way through multiple federal appellate courts. Thus far, the circuit courts have delivered a mixed and deeply divided set of opinions. While one major federal ruling sided squarely with Kalshi and the CFTC, two subsequent appellate decisions have backed the view of the states.
The widening circuit split has created intense legal uncertainty for the nascent industry, prompting New Jersey to formally petition the U.S. Supreme Court to take up the case and settle the jurisdictional dispute once and for all. As the high court weighs whether to grant certiorari, influential stakeholders and heavy hitters have lined up to submit amicus briefs and make their positions known. Among the prominent objectors joining the pushback against prediction markets is the National Football League, highlighting the immense commercial and legal friction generated by sports-related event contracts.
Despite the mounting legal pressure and the involvement of powerful sports institutions, Mansour remains defiant about the legitimacy of prediction markets and their economic footprint. He forcefully rejected the narrative advanced by state regulators and sports leagues that sports-based contracts lack the broad economic consequences required to justify status as federally regulated financial instruments.
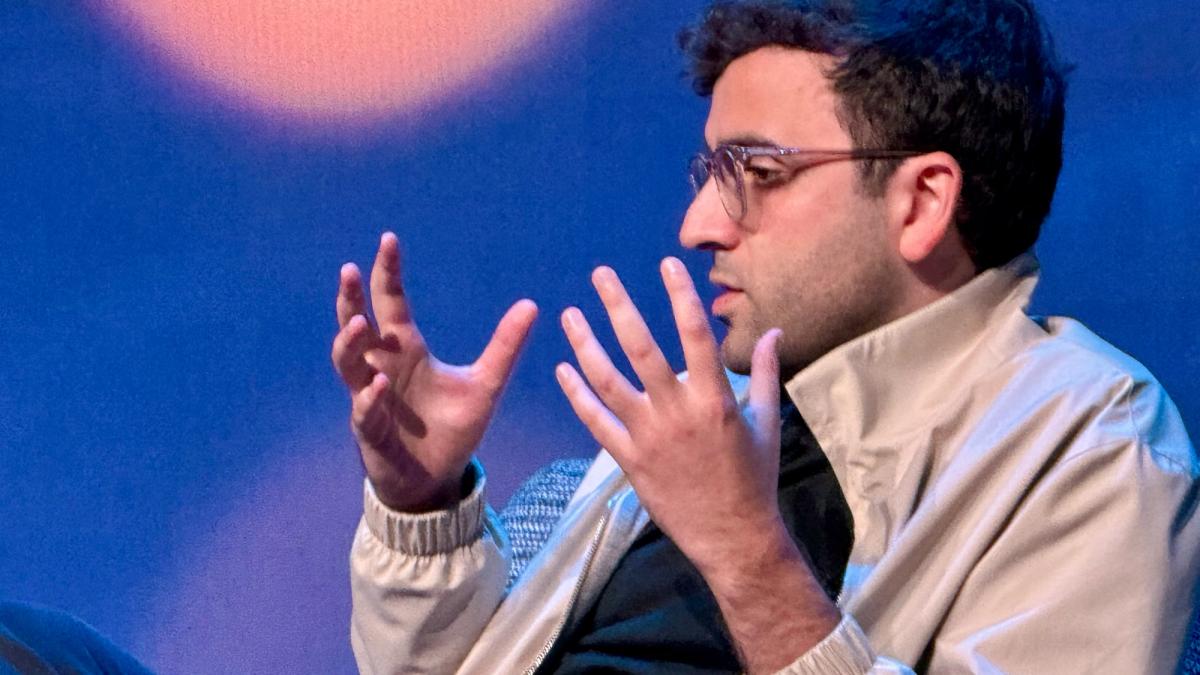
"The notion that sports does not have economic consequence is ludicrous," Mansour said, pointing to the massive commercial ecosystems, multi-billion-dollar broadcasting rights, and widespread economic impacts tied directly to the athletic industry.
Mansour emphasized that the current legal battle represents a fundamental fork in the road for American financial innovation. "It’s not a choice of state versus federal market," he warned the audience in Arlington. "It’s a choice of whether prediction markets exist in the U.S. or whether they go offshore."
Defending the foundational architecture of his platform, Mansour explained that he has carefully considered Kalshi’s regulatory relationship and statutory standing since the company’s inception. He argued that the platform’s financial products fit naturally and elegantly within long-standing federal definitions of a commodity.
Furthermore, Mansour praised the statutory design of the Commodity Exchange Act, describing it as a "truly beautiful statute" that was purposefully crafted with the flexibility to adapt to changing economic realities. Historically, the legislation allowed the U.S. regulatory framework to gracefully transition from overseeing physical agricultural futures to capturing modern markets like oil and metals, and eventually to governing less tangible financial products such as swaps and complex derivatives. In Mansour’s view, prediction markets are simply the next natural evolutionary step in this legislative lineage.
Beyond the ongoing regulatory and judicial battles, Mansour used his appearance at DC Fintech Week to address recent public scrutiny regarding trading activity on his platform. Over the past month, observers and critics on social media raised questions regarding unusually high and repetitive trading volumes in bitcoin and ether perpetual-futures markets hosted on Kalshi.
Data analyses published in September highlighted that specific, recurring trade sizes dominated a significant portion of the platform’s crypto-related volume, sparking speculation and intense debate across online forums. Addressing the chatter directly, Mansour dismissed the online controversy, remarking that "there’s a lot of crazy" circulating on the social media platform X, formerly known as Twitter.
Reiterating explanations previously provided by the company, Mansour pointed out that the questioned activity stemmed from routine, fixed-size institutional orders executed by professional market makers. He maintained that such structured liquidity provisioning is a standard and healthy feature of modern electronic financial exchanges, rather than an indication of artificial or manipulative volume.
As the legal battle over prediction market oversight barrels toward a potential showdown at the Supreme Court, Kalshi’s leadership remains steadfast. With the future of federally regulated event contracts hanging in the balance, Mansour and his legal team are betting that the federal judiciary will ultimately uphold the CFTC’s authority, preserving a pathway for domestic financial innovation rather than forcing the industry into foreign jurisdictions.