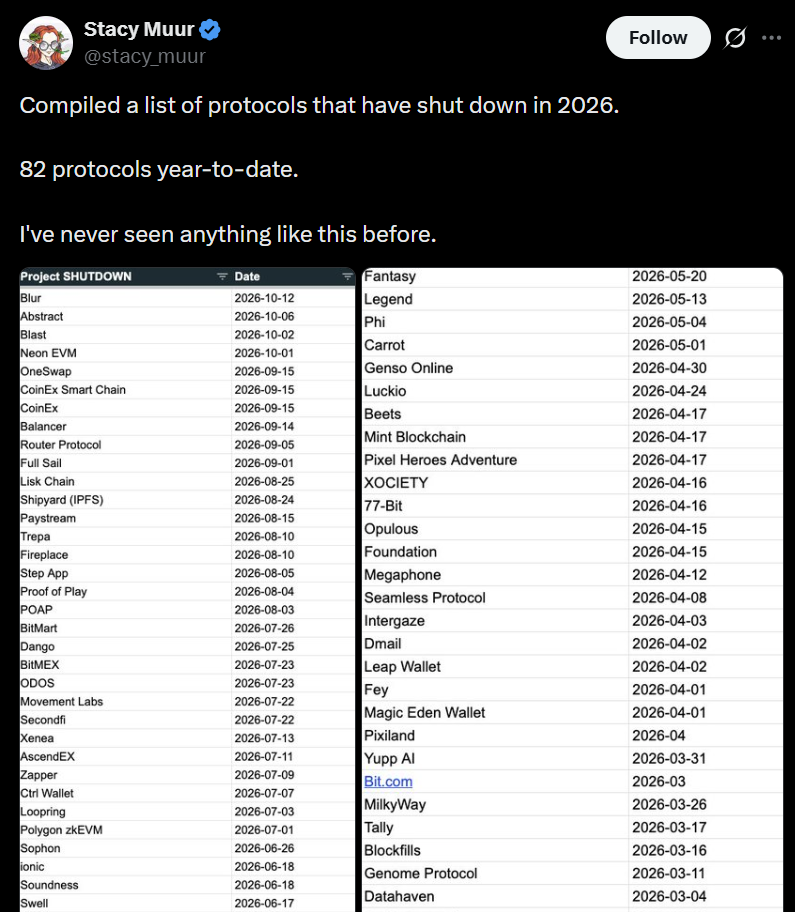
The decentralized finance, blockchain infrastructure, and Web3 gaming sectors are facing an unprecedented wave of business closures, casting a long shadow over the long-term financial sustainability of the digital asset industry. According to data compiled and published by prominent crypto researcher Stacy Muur, no fewer than 82 distinct digital asset projects and protocols have officially shut down or announced plans to wind down their operations in 2026 alone.
Muur shared the comprehensive list on X, highlighting high-profile names such as Balancer, Radiant Capital, Neon EVM, and Step Finance, alongside dozens of other lesser-known networks and applications. Describing the sheer scale of the closures, Muur noted that the volume and pace of the shutdowns are completely unlike anything she had previously witnessed across her years of tracking the industry.
This sweeping contraction follows a brutal and prolonged bear market. The broader digital asset economy has struggled to regain consistent momentum after a dramatic market correction earlier in the year. Bitcoin, the flagship cryptocurrency, retreated sharply from its October 2025 record high above $126,000, plunging below the $60,000 threshold earlier this year. This steep descent added immense financial strain to startups, protocols, and decentralized autonomous organizations already grappling with the fundamental difficulties of attracting active users, retaining liquidity, and generating sustainable, recurring revenue streams.
Among the most prominent casualties of this challenging economic environment is the Ethereum Layer-2 network Blast. Earlier this month, the project announced it would wind down its operations after internal assessments revealed there was no credible path to economic viability. The decision represented a stunning reversal of fortune for a network that had previously captured the imagination of the market, attracting more than $2 billion in total value locked in user deposits during its height. Despite massive initial capital inflows and high-profile backing, Blast ultimately buckled under the weight of operational costs that vastly outpaced its revenue generation.
Other projects have met their ends through a combination of external security crises and internal operational failures. Step Finance was forced to shutter its operations in February following a catastrophic treasury breach that drained critical resources and crippled its ongoing development. Similarly, the decentralized finance lending protocol Radiant Capital announced in June that it would officially wind down operations after exhausting all avenues to recover from a debilitating 2024 exploit that undermined user trust and depleted its financial reserves. Meanwhile, Satori Finance, a derivative platform that enjoyed backing from major industry player Coinbase, ceased operations after its leadership concluded that ongoing platform revenue could no longer support the expenses of running the business.
The widespread nature of these failures is further corroborated by independent data. Research published by DeFiLlama in August identified a staggering 100 crypto projects that had publicly announced closures over the course of 2026, which included 40 separate shutdowns in the preceding 90-day window alone. These findings point to an underlying structural issue: a vast majority of Web3 initiatives have continuously struggled to bridge the gap between speculative hype and genuine economic utility, failing to secure a loyal user base or build viable monetization models capable of withstanding broader market downturns.
Why are so many crypto projects shutting down?
A deeper analysis of the factors driving these closures points to a few recurring themes across the digital asset landscape. According to findings highlighted by DeFiLlama, the single most commonly cited reason for project failures is a fundamental lack of product-market fit. Many teams built sophisticated technological architectures without confirming whether there was genuine, long-term demand for their services outside of speculative token incentives.
Following product-market fit issues, projects frequently cited rapidly depleted funding reserves, insufficient organic revenue, and strategic decisions by founding teams to pivot entirely to alternative products or sectors. Perhaps most tellingly, the data reveals that substantial financial backing offered little to no assurance of long-term survival. The cohort of failed projects identified in recent studies collectively raised approximately $1 billion in venture capital and funding rounds while generating $250 million in cumulative protocol fees. Notably, nine of these shuttered projects had each raised more than $50 million, proving that large war chests could not save businesses that failed to achieve self-sustaining unit economics.
These closures are occurring against the backdrop of a shifting investment landscape characterized by extreme concentration. While overall venture capital funding saw a modest rise during the first half of 2026 compared to the previous year, the total number of individual deals dropped by a sharp 80%. This indicates that investors are increasingly funneling larger amounts of capital into a much smaller, highly vetted circle of established projects, starving early-stage and mid-tier protocols of the runway they need to survive. At the same time, consolidation is accelerating rapidly, with mergers and acquisitions reaching 87 transactions by the time of the report—representing a 65% increase over the previous year as struggling protocols seek buyouts or strategic absorptions to avoid total collapse.