Ethereum’s staking ecosystem witnessed a fascinating divergence during the month of October, challenging simple assumptions about how capital flows into and out of the network’s consensus layer. Data compiled by CryptoKeyhole, an analytics provider and Ethereum node operator, reveals that while more Ether left the staking system through exits and requested withdrawals than arrived via new deposits, the actual amount of active stake securing the network still managed to grow.
Between October 1 and October 30, the network recorded 1,400,947 ETH deposited by users. Over the exact same period, the platform paid out 1,511,710 ETH in its principal-withdrawn category, resulting in a net outflow of 110,763 ETH. Despite this negative net flow across the staking boundary, the effective stake of active validators rose from 35.82% to 36.09% of the total ETH supply.
This statistical divergence is crucial for investors and market analysts who often interpret a rising staked share as a straightforward indicator of fresh market demand or a tightening of liquid supply. The data shows that while more ETH can simultaneously count toward securing Ethereum, the broader pool of ETH held on its consensus layer can shrink at the same time. Understanding this nuance requires a closer look at how Ethereum’s underlying staking mechanics, queues, and reward structures operate independently of simple daily deposit and withdrawal tallies.
How Ethereum Staking Balances Diverged
The comprehensive comparison relies on CryptoKeyhole’s daily staking-share series and supply data spanning the 30 complete UTC days of October, measured from the market close on September 30 to the close on October 30. Active stake represents the effective balance of validators actively participating in consensus, meaning the specific amount that contributes directly to their network weight. Conversely, the broader consensus-layer measure encompasses much more, including queued deposits, validators waiting to activate or awaiting payment after exiting, and balances that exceed the baseline effective amount.
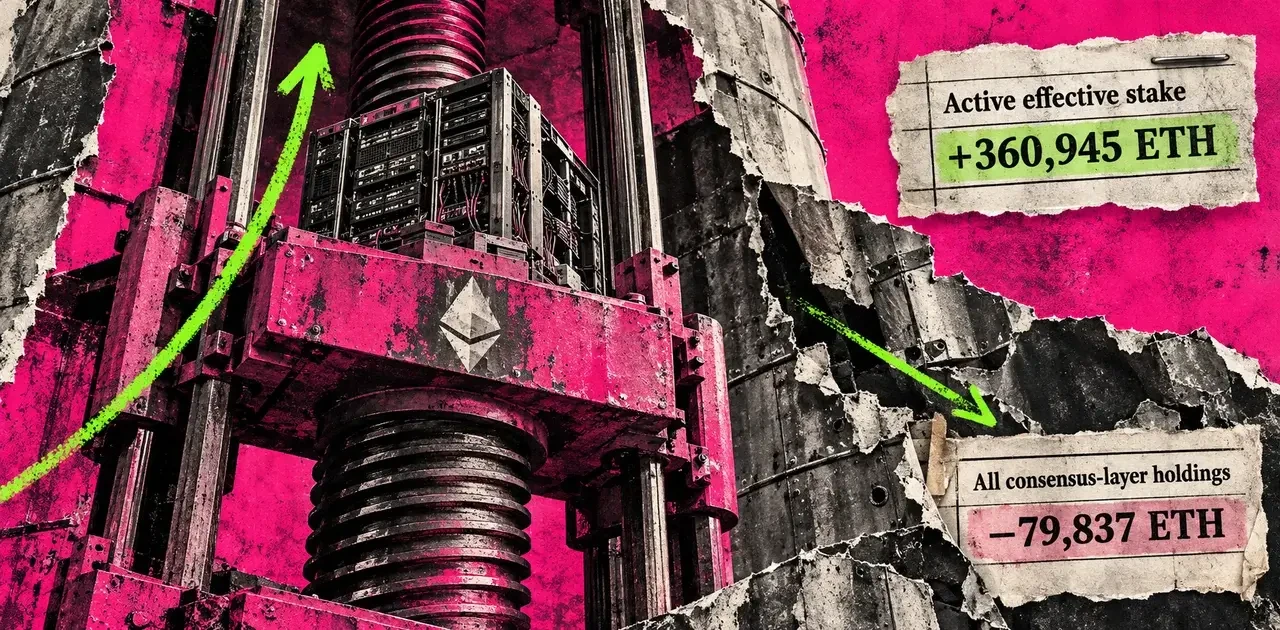
To understand the scale of these movements, multiplying the provider’s published daily shares by its corresponding supply figures yields approximate balances for the month. Active effective stake stood at approximately 43,737,996 ETH at the close of September, growing to 44,098,941 ETH by the end of October, marking an increase of roughly 360,945 ETH. In contrast, all consensus-layer holdings combined fell from 45,584,361 ETH down to 45,504,524 ETH, reflecting a net reduction of 79,837 ETH.
This means the combined balance of consensus holdings outside the active effective tally contracted significantly, dropping by 440,782 ETH from 1,846,365 ETH to 1,405,583 ETH. This contraction was more than enough to accommodate both the rise in active stake and the drop in total consensus holdings.
Importantly, a shrinking total ETH supply does not explain why the active share increased during this period. According to CryptoKeyhole’s supply series, the overall circulating and total supply actually increased by about 86,137 ETH across those monthly closes. Furthermore, the broader consensus-layer share of the total supply fell from 37.336% to 37.245%, highlighting a clear split between total consensus holdings and the active validator subset.
The flow measures tracked by analytics providers count deposit requests embedded within each day’s blocks, capturing both deposits intended for brand-new validators and top-ups for existing ones. However, submitting a request does not mean the capital instantly becomes active effective stake. Ethereum’s strict pending-deposit processing and activation rules impose mandatory waiting periods and separate procedural steps before newly committed capital can actually contribute to network consensus.
Consequently, previously deposited ETH can seamlessly transition to active status during any given month without requiring another deposit or a contemporaneous spot purchase on the open market. Conversely, a deposit made on the first day of October can easily remain trapped in the activation queue well beyond the end of the month.
Withdrawals introduce a similar temporal disconnect. A validator completely stops contributing active stake the moment it initiates an exit, long before its remaining balance is eventually paid out to its designated withdrawal address. Therefore, a payment successfully completed in late October often reflects an operational exit that impacted active stake much earlier in the timeline.
How Rewards and Payment Timing Change Active Stake
Beyond external deposits, internal network rewards play a pivotal role in shifting active stake without requiring any fresh capital influx. Under Ethereum’s design, compounding validators can automatically retain their staking rewards to raise their effective balances up to a maximum cap of 2,048 ETH. Meanwhile, legacy validators adhere to a rigid 32 ETH effective balance cap and automatically sweep any excess rewards. Whole-ETH balance adjustments and an operational buffer further separate the raw rewards earned from the actual effective stake added to the ledger.
CryptoKeyhole specifically excludes automatic excess-balance reward sweeps from its principal-withdrawn category. However, it does include full balances paid to fully exited validators as well as partial withdrawals requested directly from the execution layer. Because these payouts frequently contain accumulated rewards earned over months of operation, the term "principal" functions more as a broad category label rather than a strict mathematical calculation of original external deposits.
Consolidations also require specialized accounting that complicates straightforward analyses. These network mechanisms allow existing stake to be consolidated into fewer active validators rather than constituting new external deposits from market participants. Intermediate adjustments in active balances and any residual subsequent withdrawals can heavily influence relevant tallies without representing fresh buying pressure or retail capital inflows.
Activation and payment timing collectively explain why these distinct metrics frequently diverge. Aggregate balance changes alone fail to neatly allocate the 360,945 ETH increase among competing factors like queue activation, reward compounding, consolidation effects, and other routine effective-balance adjustments.
Furthermore, the 110,763 ETH flow deficit measures entirely different underlying components than the net change observed across the full consensus ledger. The ledger change inherently includes rewards net of penalties and automatic payouts, meaning these macroeconomic aggregates alone cannot fully reconcile the two datasets without deep contextual understanding.
A Deep Entry Queue Still Represents Earlier Commitments
The persistent entry backlog provides another distinct pool of ETH that analysts must carefully separate from day-to-day new deposits. CryptoKeyhole’s closing queue data shows that the volume of ETH awaiting entry fell from 1,578,359 ETH on September 30 to 1,226,570 ETH on October 30, marking a substantial decline of 351,789 ETH.
This decline, however, should not be interpreted as a direct measurement of immediate activations. Continuous new requests, network processing capacity, and internal queue movements constantly alter the balance along the way. Similarly, a steep drop in the exit queue does not automatically mean that the entirety of that volume was paid out to users within the same calendar month.
Looking closely at subsequent epochs, CryptoKeyhole reported 1,104,862 ETH awaiting entry at a finalized epoch timestamped November 2, estimating an average wait time of roughly 19.7 days for a new deposit to be fully credited. While this later snapshot provides vital context for understanding the broader backlog, the core October comparison remains anchored to the closed-day balances.
Even a completely emptied exit queue leaves subsequent payout steps intact. CryptoKeyhole noted a 27.3-hour withdrawability delay following a validator’s exit, which is then followed by actual payment distributed during a withdrawal sweep. Its last complete sweep cycle took 7.1 days, though historical durations do not serve as guaranteed waiting times for every individual validator.
These operational realities underscore a fundamental truth about Ethereum’s technical architecture: a staking queue, an active validator balance, and a completed payment represent entirely different points within the exact same continuous process. At the receiving end, Ethereum’s established withdrawal rules credit funds directly to a specified execution-layer address, but the arrival of that payment alone establishes neither an immediate exchange deposit nor a market sale.