Pump.fun, a leading Solana-based token launchpad, continues to generate millions of dollars in protocol revenue from relentless memecoin trading, even as the vast majority of established tokens struggle to recover from steep market losses.
According to data from DefiLlama, the platform produced approximately $18.6 million in protocol revenue over the seven days leading up to Oct. 7. This financial success for the underlying infrastructure stands in sharp contrast to a broader market study conducted by Talos, which revealed that 81% of a selected group of memecoins have plummeted by at least 90% from their all-time highs. Furthermore, the study noted that meaningful recoveries from such deep collapses remain exceptionally rare across the ecosystem.
This stark divergence highlights a central fault line in the modern memecoin economy. Trading activity across Pump.fun can enrich the platform, support structured PUMP buybacks, or reward select users through various incentive programs, but it does so without necessarily helping individual holders whose tokens have lost their underlying demand.
To understand the scale of the downturn for token holders, the Talos study examined 150 memecoins for survival analysis and 151 assets for return comparisons. Each evaluated asset was required to have pricing data available on at least one centralized exchange. Because securing a centralized exchange listing is already a marker of relative success, analysts point out that these findings likely understate the true failure rate across the much larger universe of launchpad coins that never secure exchange listings.
Even within this comparatively strong cohort of tokens, the losses were severe. The median token peaked roughly 17 days after exchange trading officially began. Talos defined a market collapse as a catastrophic 95% decline from that eventual peak and estimated a median timeframe of about 370 days between reaching the all-time high and hitting that downward threshold.
Only a small fraction of these collapsed tokens ever managed to revisit their previous highs, while just five of the 151 coins in the return sample remained above their first-day trading price. In a separate Talos analysis focusing on major Solana-era memecoins, active wallet addresses holding balances of at least $1 had dropped to no more than 7% of their respective peak levels.
This prevailing pattern suggests that market attention frequently moves on to the next speculative wave rather than returning to repair older, depreciated positions. Talos found that roughly two-thirds of the Solana-era memecoins it tracked never staged a meaningful second rally following their initial speculative run.
For an individual trader, this creates an economic reality that is entirely different from the structural position Pump.fun itself occupies.
Memecoin churn keeps Pump earning
Pump’s underlying revenue model depends directly on continuous transaction volume occurring somewhere across its ecosystem. Crucially, it does not require any older token to recover its lost value in order for the protocol to remain profitable.
A trader who sells one fading coin and immediately rotates capital into another newly launched asset generates yet another fee-producing transaction for the platform. New token launches, rapid rotations between competing assets, and recurring speculative bursts can therefore sustain robust platform income even while earlier buyers remain heavily underwater on their initial investments.
DefiLlama data showed that traders paid about $52.5 million in total transaction fees over the seven days through Oct. 7, with approximately $18.64 million of that sum accruing directly to the protocol. Looking at a slightly broader window, platform fees totaled about $184.5 million over 30 days, while protocol revenue reached roughly $60.7 million.
Who ultimately benefits from this high-velocity economic activity depends entirely on how the generated capital flows through the ecosystem.
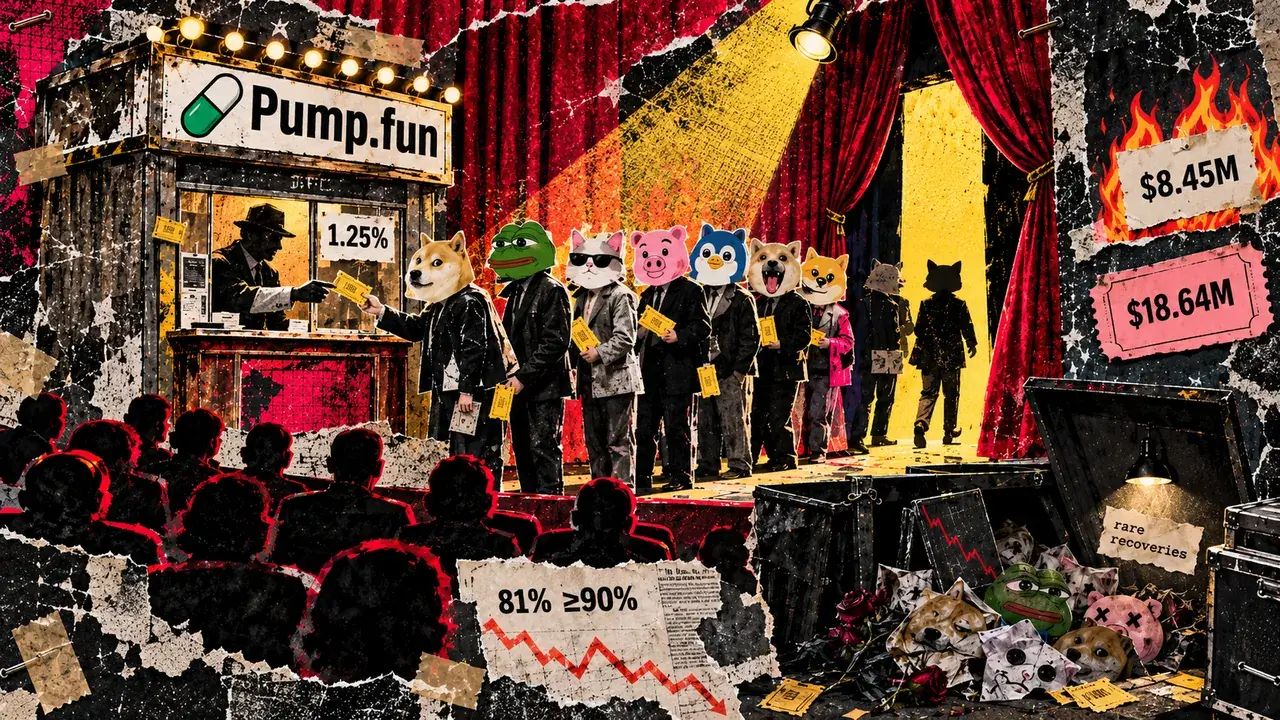
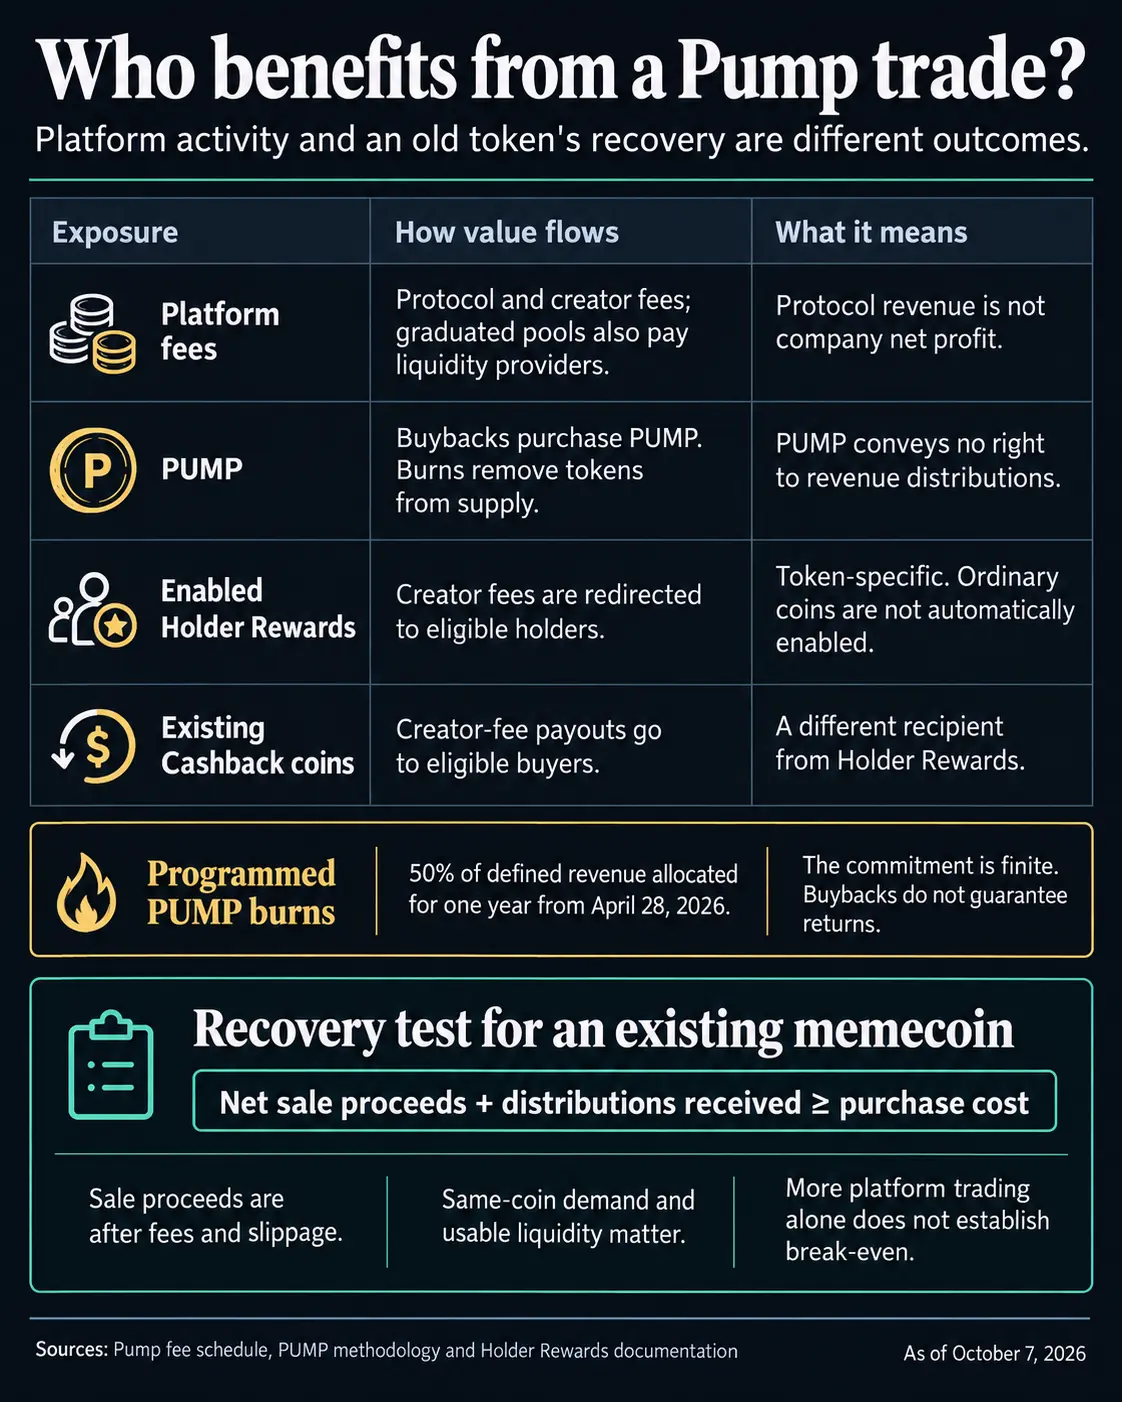
Pump’s fee structure distributes portions of trading income among the protocol itself, token creators, and various liquidity-related recipients. Its native PUMP token also maintains a direct economic route through systematic buybacks and token burns, giving the asset direct exposure to activity across the wider platform infrastructure.
DefiLlama recorded approximately $8.45 million worth of PUMP token burns over a seven-day period, and $27.29 million over a 30-day window. Pump has formally committed a portion of its designated revenue to buying back and burning PUMP tokens over a one-year period that began in April.
However, this systemic mechanism does very little directly for someone holding a separate, unrelated memecoin. For those retail investors, any hope of recovery still depends heavily on demand returning to the specific asset they own, the presence of sufficient market liquidity to execute a sale, and distributions large enough to offset losses incurred by the token itself.
Despite these holder challenges, Pump.fun maintains that it is steadily widening the share of platform economics that directly reach active users.
Alon Cohen, co-founder of the memecoin launchpad, noted that more than 140,000 users collectively received about $4.46 million over a recent 24-hour period. This distribution included $730,000 in Holder Rewards, $330,000 in Callout Rewards, and $3.4 million distributed as creator fees.
"In time, Pump.fun will vastly outperform the social media industry in user payouts and rewards," Cohen stated.
These payouts support Pump’s ongoing argument that the platform is increasingly distributing trading economics outward rather than retaining all value at the protocol level. However, the three distinct reward categories target different participants in the ecosystem.
Creator fees directly benefit the individuals behind the creation of specific tokens. Callout Rewards compensate eligible promoters or external contributors for driving attention. Meanwhile, Holder Rewards apply exclusively to participating coins and do not automatically reach every single person holding a Pump-launched asset.
This distinction becomes critically important when token losses are weighed directly against distributed rewards. A token holder can receive periodic distributions and still suffer a net loss if the underlying coin’s market value falls at a much faster rate. Similarly, a token creator can generate substantial trading fees even as the buyers who entered near the peak suffer deep drawdowns.
PUMP token holders face an entirely separate market equation. Buybacks create artificial demand while burns reduce circulating supply, but the token still carries its own distinct market risk and does not grant holders a contractual claim on Pump.fun’s corporate revenue. Furthermore, scheduled token unlocks can introduce new supply into the market even as ongoing burns work to remove tokens from circulation.
The underlying economics therefore diverge sharply as speculation moves through the platform. Pump can earn revenue from aggregate trading volume, PUMP can capture a portion of that activity through structured buybacks, and selected creators or holders can receive fee distributions. None of these mechanisms, however, guarantees recovery for the average investor waiting for buyers to return to an older, neglected memecoin.
This economic gap is expected to become even more pronounced as Pump continues to expand its various reward programs.
If future distributions grow large enough to materially compensate holders for declining token values, they could fundamentally alter the financial calculus of staying invested long after the initial speculative rush has faded. Conversely, if trading activity continues migrating toward brand-new launches faster than rewards can accumulate in older ones, Pump may succeed in perpetually converting user churn into protocol revenue while many of the traders supplying that activity remain unable to exit their original positions at break-even.