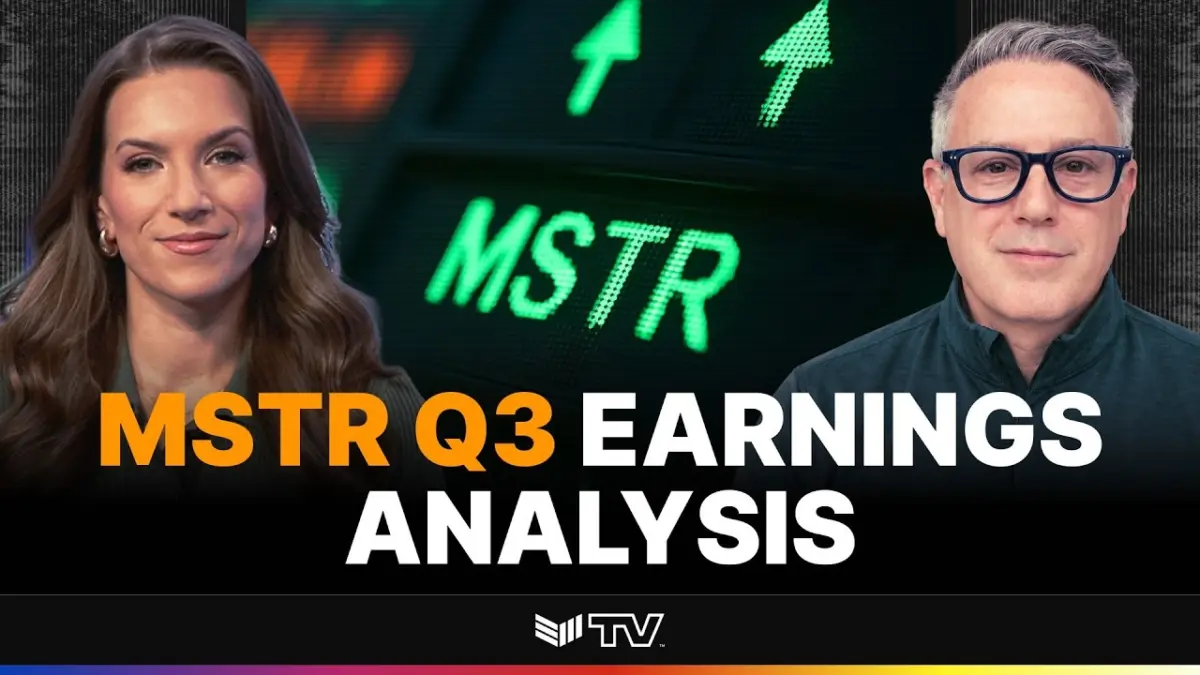
Log Scale Investments CEO Mike Flaum recently sat down with Bitcoin Magazine TV for an extensive discussion exploring the evolving landscape of corporate Bitcoin treasuries, innovative capital structures, and the broader macro environment shaping the digital asset economy. During the interview, Flaum provided deep insights into several critical developments within the Bitcoin financial ecosystem, including Strategy’s corporate maneuvers, the mechanics of daily dividends, the introduction of Strive’s SATS, and how Bitcoin-backed preferred securities compare to traditional United States Treasury bonds for retirement-age investors.
The conversation also tackled complex market mechanics, such as net asset value (mNAV) metrics, the ongoing relevance of the traditional four-year Bitcoin cycle, and why investors should fundamentally separate asset volatility from true financial risk when evaluating long-term prospects.
Strategy’s Stretch and the Return to Par
A central theme of the discussion focused on Strategy and the operational implications of its financial instruments, specifically examining what it means when Stretch gets back to par. Flaum analyzed how issuing Stretch at the $100 price level can serve as a catalyst for restarting aggressive corporate Bitcoin accumulation. As corporate entities increasingly look for innovative ways to leverage balance sheets without diluting existing equity holders in conventional ways, understanding these financial instruments becomes paramount for market observers.
The conversation shifted toward shareholder approval of daily dividends within Strategy’s corporate framework. Flaum broke down the operational mechanics of how these daily payouts function, drawing fascinating parallels to Bitcoin perpetual futures markets. By comparing corporate distribution mechanisms to derivative market structures, Flaum highlighted how modern financial engineering is beginning to mirror the high-velocity dynamics native to the cryptocurrency trading ecosystem.
This dynamic naturally creates a divergence in market participation, separating opportunistic short-term traders from long-term preferred shareholders. While tactical traders look for immediate yield or arbitrage opportunities surrounding distribution events, long-term capital allocators view these instruments through the lens of sustained digital asset exposure and steady yield generation.
Evaluating Capital Stacks: Strategy Versus Strive’s SATS
The interview also addressed the broader corporate adoption landscape, analyzing Strive’s SATS offering and whether its recent oversubscription represented genuine net-new capital entering the Bitcoin ecosystem. As more financial products emerge, determining whether capital is newly flowing into the asset class or merely rotating within existing market pools remains a critical metric for gauging institutional maturation.
Flaum provided a detailed comparative analysis between Strategy and Strive’s respective capital stacks. By examining how different firms structure their debt, equity, and preferred instruments, viewers gained a clearer picture of how corporate treasuries manage leverage and risk exposure. This structural comparison underscores the diverse approaches companies are taking to maximize their Bitcoin per share metrics while maintaining corporate solvency.
A significant portion of the discussion centered on mNAV—specifically dissecting gross mNAV, enterprise value (EV), and net mNAV calculations. Flaum explained why Strategy’s stock price has occasionally lagged behind the actual value of its underlying Bitcoin holdings, offering clarity on the discounts and premiums that frequently characterize corporate holding companies. Building on this, he explored the concepts of digital credit, capital amplification, and share buybacks as tools for enhancing shareholder value in a volatile macroeconomic climate.
Bitcoin-Backed Preferreds Versus Traditional Treasuries for Retirees
As Bitcoin financialization deepens, products designed for conservative or risk-averse portfolios are beginning to surface. Flaum evaluated the growing proposition of Bitcoin-backed preferred securities as a viable alternative to traditional U.S. Treasury bonds, particularly for retirees and investors seeking predictable income streams without total exposure to unhedged fiat currency devaluation.
This comparison led to a broader philosophical discussion on risk versus volatility. Flaum emphasized the necessity of separating the two concepts, arguing that an asset experiencing high price volatility—such as Bitcoin—does not necessarily carry a high fundamental risk of permanent capital loss, especially over long investment horizons. Conversely, traditional fixed-income instruments like long-term government bonds, while exhibiting lower short-term price fluctuations, carry severe purchasing power risk in an inflationary monetary system.
Macro Dynamics, the Four-Year Cycle, and Long-Term Outlook
The conversation naturally gravitated toward macro market cycles, addressing the perennial question among crypto analysts: Is the Bitcoin four-year cycle dead? Flaum examined historical halving patterns and the shifting dynamics of institutional liquidity to explain why Bitcoin has increasingly demonstrated the tendency to reach new all-time highs ahead of the actual halving event.
Concluding the interview, Flaum reviewed recent institutional projections, including Bitcoin price forecasts from major financial institutions like JPMorgan, while offering his own perspective on Bitcoin’s long-term return profile. Despite short-term market fluctuations and macroeconomic headwinds, Flaum maintained a decisively bullish stance on the structural future of the asset class.