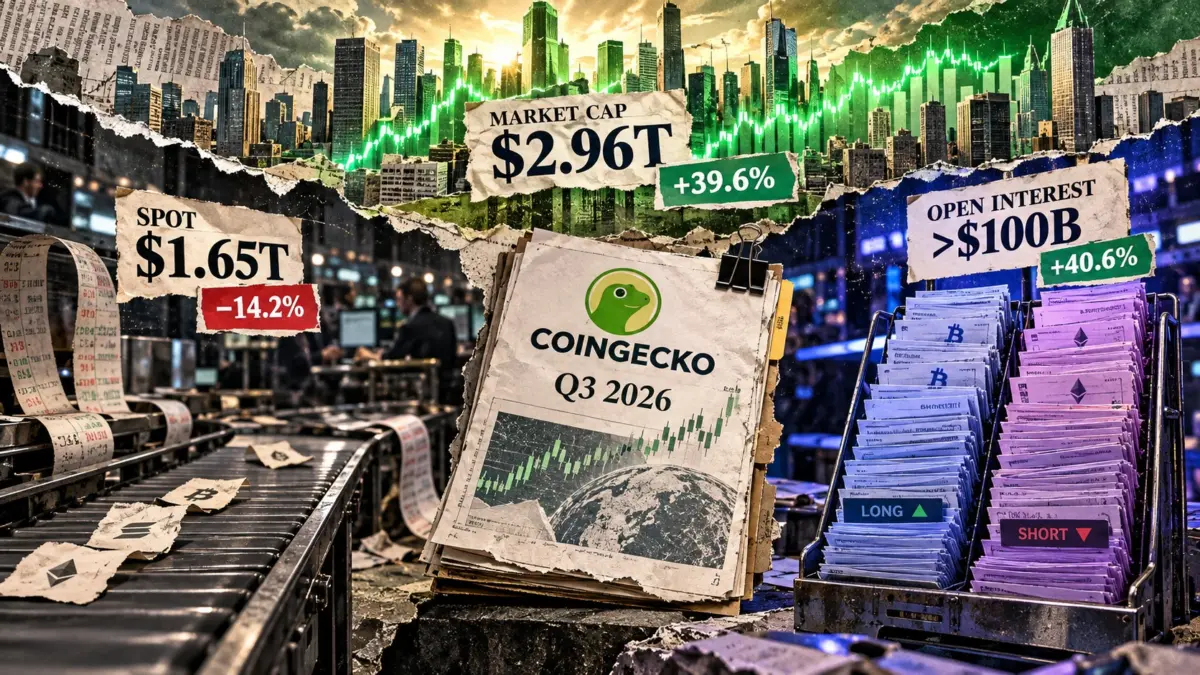
The cryptocurrency market experienced a dramatic resurgence during the third quarter of 2026, punctuated by a massive expansion in overall valuations even as spot trading activity at major centralized exchanges contracted. According to the latest comprehensive industry report published by crypto data aggregator CoinGecko, the total cryptocurrency market capitalization surged by nearly 40% between July and September, closing out the quarter at approximately $2.96 trillion compared to roughly $2.1 trillion at the end of the second quarter.
Despite this impressive $800 billion influx of value across the broader ecosystem, spot trading volumes told a distinctly different story. The top ten spot cryptocurrency exchanges tracked by CoinGecko handled $1.65 trillion in total quarterly turnover during the third quarter. This figure represents a noticeable 14.2% decline from the $1.93 trillion recorded during the second quarter, illustrating a market environment where asset prices appreciated rapidly while immediate, day-to-day spot exchange activity simultaneously cooled.
At the same time, the derivatives market painted a picture of expanding leverage and sustained speculative or hedging interest. The aggregate dollar-denominated open interest across the top ten perpetual futures exchanges climbed significantly, rising 40.6% over the course of the quarter to finish September comfortably above the $100 billion threshold. This divergence highlights a distinct macro trend for Q3 2026: recovering valuations accompanied by lower spot turnover on one hand, and a substantially larger dollar value tied up in outstanding perpetual futures contracts on the other.
Examining individual exchange performances within this shifting landscape, industry giant Binance managed to expand its footprint despite the broader contraction in spot trading. Binance’s market share of the tracked spot volume increased from 38.7% in the second quarter to 42.7% in the third quarter. Conversely, the perpetual futures sector experienced mixed dynamics among major players, with platforms such as KuCoin and Deribit registering declines in open interest even as the aggregate sector-wide figure trended upward.

Understanding the Dynamics of the $100 Billion Open Interest Metric
To properly contextualize the milestone of perpetual open interest crossing the $100 billion mark, market analysts emphasize the fundamental differences between spot turnover and derivatives exposure. Open interest specifically captures the total number of derivative contracts—such as futures or options—that remain active and unclosed at a specific point in time. By contrast, metrics like quarterly spot turnover aggregate every completed transaction over a prolonged three-month period. Consequently, the $1.65 trillion spot figure measures cumulative trading velocity over a quarter, whereas the $100 billion-plus figure describes the snapshot exposure remaining at the very close of September.
Because research platforms like CoinGecko track top-ten exchange cohorts independently for spot markets and derivatives markets, direct capital flows moving dynamically from spot portfolios into leveraged derivatives cannot be definitively traced through these aggregate figures alone. Perpetual futures, which represent a cornerstone of modern crypto derivatives trading, do not feature a scheduled expiration date. Traders maintain these positions indefinitely by keeping sufficient margin, or collateral, in their accounts to prevent liquidation.
Within these markets, every single contract pairs an active buyer with an active seller. As a result, the total outstanding notional value does not inherently indicate a net bullish or bearish market sentiment, nor does it explicitly reveal whether participants are utilizing leverage primarily for speculative positioning or for hedging existing spot holdings.
Data analytics methodologies provided by firms like Coin Metrics further clarify how the notional value of futures contracts is calculated. Futures open interest is fundamentally a product of contract quantity, contract size, and the reference price of the underlying digital asset. For contracts whose standardized size is measured directly in coin units rather than fiat currency, rising underlying asset prices naturally elevate the total dollar-denominated open interest even if the absolute physical quantity of underlying coins held in open contracts remains entirely unchanged.
Consequently, due to these underlying structural variables and asset price appreciation, the reported 40.6% quarterly increase in perpetual open interest cannot by itself establish whether the growth was driven by fresh capital inflows, broader institutional adoption, or shifting trader leverage ratios across the ecosystem.
Reconciling Monthly Momentum with Quarterly Declines
A closer examination of intra-quarter momentum helps explain the apparent paradox of a flourishing overall market coexisting with lower quarterly metrics. In CoinGecko’s broader market-wide series, trading activity exhibited a marked acceleration as the third quarter drew to a close. Specifically, September’s average daily trading volume rebounded to reach $94.8 billion, a sharp recovery from the summer lull observed in July, when average daily volume sat at $57.7 billion.
Despite this robust late-quarter recovery, the full-quarter daily average volume still registered an 8.6% decline, dropping to $70.3 billion compared to $73.3 billion in the second quarter. This series operates independently from the top-10 spot exchange turnover total, yet it effectively demonstrates how a powerful late-quarter surge in momentum could occur simultaneously alongside a modest quarter-over-quarter contraction in aggregate volume.
For the entirety of the third quarter of 2026, the velocity of the valuation rebound clearly outpaced the immediate recovery in overall trading activity. The elevated derivatives totals reflect the higher dollar valuation of positions left open as September came to a close, marking a distinct phase in the market cycle where capital preservation, longer-term positioning, and rising asset prices took precedence over high-frequency spot exchange turnover.