Recent market dynamics on cryptocurrency options exchanges have highlighted a critical lesson for traders managing downside risk: a calm headline volatility index does not necessarily reveal the true cost of protecting a digital asset holding. Between November 12 and November 13, a specific Bitcoin hedging contract utilizing a put option with a $70,000 strike price more than doubled in value when measured in BTC terms. This dramatic repricing occurred even as broader market indicators reported a decline in implied volatility, demonstrating how fixed-strike protection can rapidly become more expensive as the underlying asset price drops.
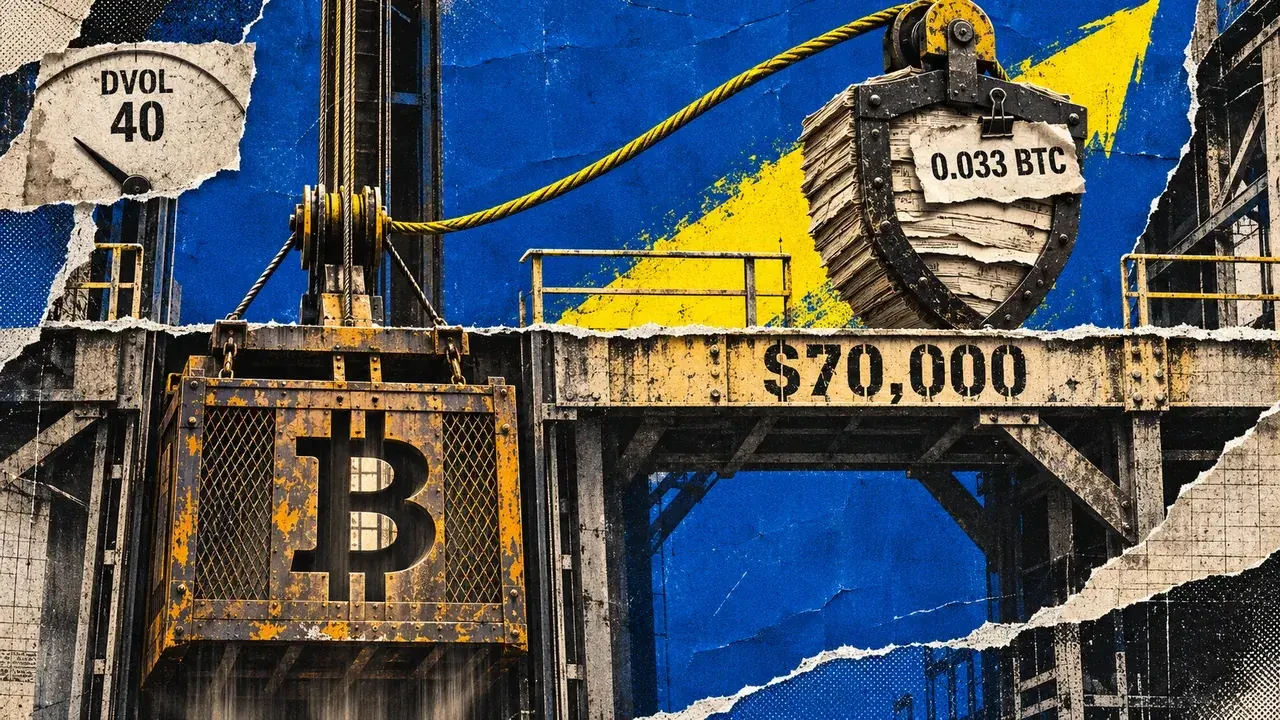
Observations from the Deribit derivatives exchange during this 24-hour window captured a striking divergence between traditional volatility gauges and actual contract execution costs. Specifically, the November 27 put option featuring a $70,000 strike traded at 0.0145 BTC at 11:51 UTC on November 12. Less than 24 hours later, at 10:15 UTC on November 13, the same instrument traded at 0.033 BTC. This represented a substantial increase of 127.6 percent in BTC terms.
Paradoxically, the implied volatility reported for those specific executions moved in the opposite direction, falling from 38.97 percent to 37.67 percent over the same period. This counterintuitive movement underscores the complex mechanics governing options pricing, where multiple variables interact simultaneously to determine the ultimate premium paid by market participants seeking portfolio insurance.
The underlying catalyst for this shift was Bitcoin’s downward price movement. During the interval between the two recorded trades, Bitcoin’s index price dropped from $72,805.71 to $69,320.08. This movement carried the cryptocurrency from a position safely above the fixed strike price to a level below it, transforming the option’s moneyness.
A put option provides its holder with the right to sell the underlying asset at a predetermined strike price, effectively offering protection against market declines below that threshold up until expiration. As the price of Bitcoin falls closer to or below the strike, the fixed protection offered by the contract naturally becomes more intrinsically valuable. This intrinsic value shift can drive up the cost of the option even in the absence of a broader surge in market-wide implied volatility.
Examining the order book further illustrates the prevailing market conditions around that time. For a new buyer entering the market at 10:40:51 UTC on November 13, the contract’s order book reflected a bid of 0.0325 BTC and an ask of 0.0335 BTC. With the Bitcoin index standing at $69,245.85, that prevailing ask translated to approximately $2,319.74 for a single contract before factoring in trading fees. Analysts emphasize that the 127.6 percent increase observed represents a comparison of executed transaction prices in BTC rather than a direct measurement of shifting executable asks across the order book.
A fixed strike changes the Bitcoin hedge bill
The premium associated with a protective put represents the market price of securing downside protection at a specified strike price and expiration date. Implied volatility serves as just one component of that complex pricing formula. Other critical inputs include the current price of the underlying asset, the strike price itself, the forward price of the asset, and the amount of time remaining until expiration. Broader crypto options platforms and industry comparisons consistently highlight how contract design, underlying settlement mechanisms, and execution costs can vary significantly across different trading venues.
Because the two observed executions do not completely isolate how much of the premium change stemmed from each individual pricing input, market observers must account for multiple shifting variables. Furthermore, the contract possessed slightly less time remaining until expiration at the time of the second trade, a factor that normally acts to decay option values unless offset by other stronger market forces.
The currency denomination of the quote introduces another layer of complexity. Deribit’s inverse Bitcoin options are priced directly in BTC, with a single contract representing one Bitcoin. When converting each selected trade at its own contemporaneous index price, the dollar value was approximately $1,055.68 on November 12 and $2,287.56 on November 13. When measured in fiat currency terms, the increase in those dollar equivalents was 116.7 percent, which is notably smaller than the 127.6 percent increase recorded when the contract was priced purely in BTC.
It is also important for market participants to note that holding a $70,000 strike put does not inherently promise a guaranteed net sale price of $70,000. The buyer must pay the BTC premium upfront, and various factors such as trading fees, delivery fees, currency conversion rates, and the specific settlement reference index will ultimately affect the net financial result. At expiration, an in-the-money inverse put settles through an immediately settling inverse futures contract into BTC, achieving the economic equivalent of cash settlement, whereas an out-of-the-money put simply expires worthless.
Market participants often look to broad benchmarks to gauge overall sentiment, such as Deribit’s DVOL index. Deribit defines DVOL as a forward-looking, annualized implied volatility measure spanning a 30-day window, aggregated across various strikes and expirations. However, the specific November 27 put option analyzed in these trades had roughly 14 days remaining until maturity. Relying on a single broad index alongside a shorter-dated contract means evaluating two distinct exposures with different time horizons.
Historical context provides additional perspective on these volatility readings. Analysis from market research sources like CryptoQuant highlights that broader volatility metrics can often remain subdued during significant price corrections compared to historical norms. When Bitcoin experiences pullbacks from its rolling highs, options markets sometimes price in less immediate selloff fear than what has been observed in past market cycles, though these historical comparisons serve more as broad framing tools rather than exact indicators for pricing an individual hedge in real time.
The observations preceded the PPI release window
Timing is another crucial element when evaluating market adjustments. The broader macroeconomic calendar often introduces catalysts that prompt traders to reprice risk ahead of scheduled data releases. For instance, October’s Producer Price Index report was officially scheduled for release on November 13 at 08:30 Eastern time, which corresponds to 13:30 UTC—occurring shortly after the specific market observations and trade executions detailed here. While such scheduled inflation reports provide a clear checkpoint for observing subsequent market repricing, they do not inherently establish a direct cause for earlier intraday movements.
Financial analysts note that a comprehensive before-and-after comparison of hedging costs requires tracking the exact same contract’s bid, ask, and implied volatility alongside its forward price and remaining time to maturity. Extending that analysis across multiple strikes helps separate genuine changes in the cost of acquiring downside protection from broader shifts in volatility pricing, offering a more nuanced view than relying solely on a headline volatility index like DVOL.
For digital asset holders, the immediate practical takeaway from these market movements is already visible in day-to-day trading operations. Maintaining a Bitcoin hedge anchored to a fixed dollar strike can become noticeably more expensive as the price of Bitcoin trends downward, even during periods when the market’s broad volatility gauges remain remarkably calm and subdued.