US wholesale inflation showed signs of cooling in October, yet a complex mix of rising freight prices and firm underlying pressures has complicated the narrative that cheaper energy costs will immediately translate into easier financing conditions for Bitcoin holders. As the premier digital asset continues to trade below the crucial $70,000 threshold, macroeconomic crosscurrents are proving that the relationship between producer input costs and cryptocurrency market liquidity is far from straightforward.
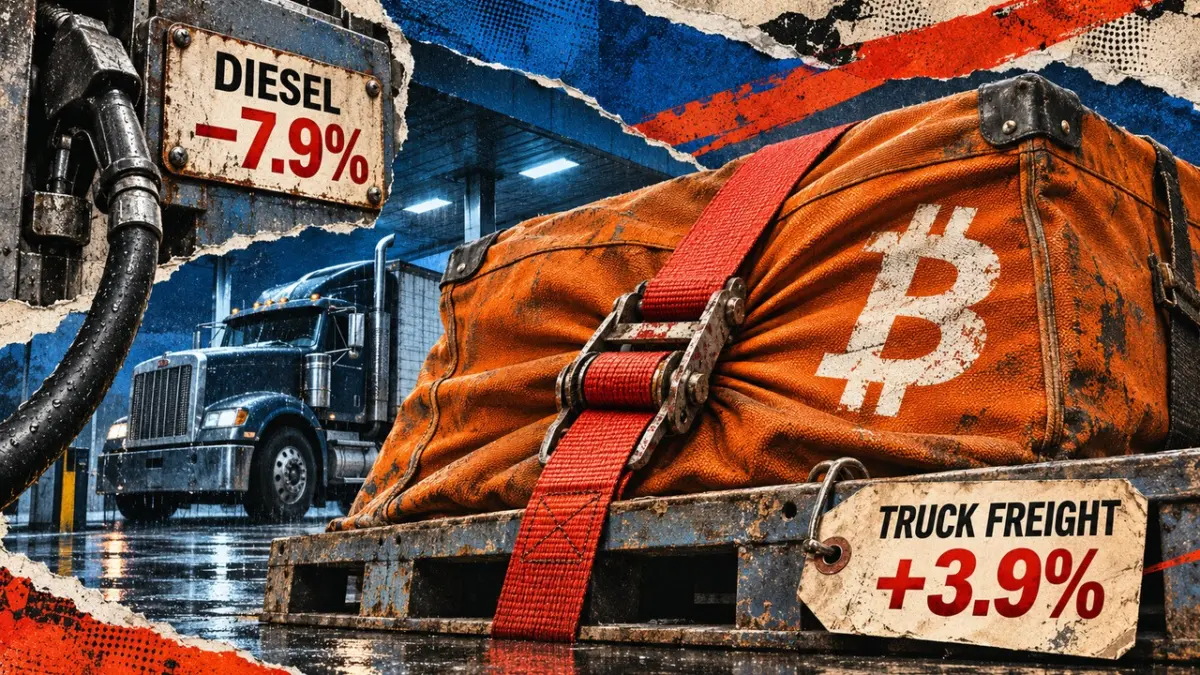
According to the producer-price report released by the Bureau of Labor Statistics on November 13, diesel prices fell by a notable 7.9%. Paradoxically, however, truck freight prices climbed by 3.9% over the same period. While headline wholesale inflation slowed sharply on a monthly basis, the core measure that excludes volatile food, energy, and trade services maintained the exact same monthly pace established back in September, signaling that underlying economic pressures refuse to dissipate quickly.
Final-demand the Producer Price Index (PPI) rose by a seasonally adjusted 0.3% in October. This followed a considerably larger, revised increase of 1.4% in September, initially suggesting a dramatic relief in upstream price pressures. However, a deeper look into the components reveals a more nuanced economic reality. The specific measure excluding food, energy, and trade services advanced by 0.5% for the second consecutive month. On an annual basis, this particular core measure eased slightly to 4.9% from 5%, while the headline annual PPI actually accelerated to 6.5% from 6.3%.
These mixed readings underline a complex assessment of the current economic environment. While certain headline comparisons have undeniably improved, the persistent firmness of underlying monthly pressure demonstrates that inflation has not been entirely tamed. The Bureau of Labor Statistics attributed more than 80% of October’s 0.2% rise in final-demand services prices squarely to truck freight costs. Transportation and warehousing services surged by 2%, directly counterbalancing a 0.1% dip in final-demand energy prices and a 0.5% increase in overall goods prices.
This dynamic illustrates a fascinating economic disconnect where cheaper diesel coexists with higher prices for moving goods across the supply chain. For the time being, the unexpected increase in freight rates undercuts the simplistic assumption that a lower fuel bill immediately translates into cheaper transport and broader logistical relief. At the same time, unprocessed intermediate goods prices fell by 3.1%. Alongside slower monthly headline inflation and the easing annual exclusion measure, this drop provides genuine evidence for a more optimistic macroeconomic interpretation. The central question facing economists and market participants alike is whether this cooling trend will prove to be broad-based and sustained over the coming months.
Changing the Inflation Lens and Assessing Producer Price Dynamics
The Producer Price Index series describes a wide variety of domestic selling prices received by producers, which differs inherently from the Consumer Price Index tracking prices paid directly by consumers, as well as the Federal Reserve’s preferred metric, the Personal Consumption Expenditures (PCE) price index. Although these various economic measures naturally overlap in the broad pressures they attempt to describe, their specific readings are far from interchangeable.
The concurrent movement of falling diesel prices and rising freight charges does not establish a direct cause-and-effect relationship or predictable pass-through timing. Furthermore, analysts must account for the fact that monthly changes are seasonally adjusted while annual changes remain unadjusted, adding another layer of complexity to interpreting what these figures mean for risk assets.
Speaking publicly just prior to the release of that day’s consumer inflation data, Federal Reserve Governor Christopher Waller leaned toward the possibility of further monetary policy tightening through an additional 25-basis-point interest rate increase at the December meeting, provided that economic conditions continued to develop largely as expected. Waller explicitly noted that a more aggressive 50-basis-point increase should also be actively considered if the October core consumer inflation report mirrored the previous two readings of approximately 0.3% or higher.
The subsequent Consumer Price Index report ultimately revealed a 0.4% monthly headline increase alongside a third consecutive 0.3% monthly increase in the measure excluding food and energy. The Federal Reserve’s established framework for monetary policy describes how shifts in the policy rate directly influence short-term interest rates and, by extension, broader financial conditions. When applied to the digital asset ecosystem and Bitcoin specifically, the conditional mechanism suggests that lower financing costs could make borrowed market exposure significantly easier to carry. Furthermore, looser financial conditions historically encourage institutional and retail investors to allocate a higher percentage of capital toward risk-on assets.
The Hurdle for Bitcoin Extends Well Beyond Upstream Price Indexes
Despite these theoretical linkages, the actual route from producer prices to tangible financing relief for cryptocurrency investors remains heavily conditional. Persistent underlying inflation could easily force central bankers to keep monetary policy restrictive even in the face of falling fuel prices. Consequently, any bullish recovery case predicated solely on financing relief requires far more concrete evidence than a temporary decline in diesel costs.
Market sentiment and capital flows have already begun reflecting this cautious stance. Data compiled by Farside Investors for the trading row completed on November 12 documented US Bitcoin exchange-traded fund net outflows totaling $284.1 million, occurring just prior to the official producer price release. While exchange-traded fund flows represent only one specific investment channel within the broader digital asset economy, actual, sustained capital inflows would provide much firmer evidence of institutional buyers returning to the market than purely inflation-based macroeconomic expectations.
Ultimately, a broader cooling trend across both consumer and producer prices, coupled with less restrictive assessments from monetary policymakers and observable relief in financing markets, would significantly strengthen the argument that falling fuel costs are translating into genuine benefits for Bitcoin holders. Sustained inflows into spot cryptocurrency exchange-traded funds would add crucial demand-side evidence to this narrative. Conversely, continued underlying inflation pressure and persistent capital withdrawals from investment products will keep the bullish case subdued, regardless of how inexpensive diesel fuel continues to become.