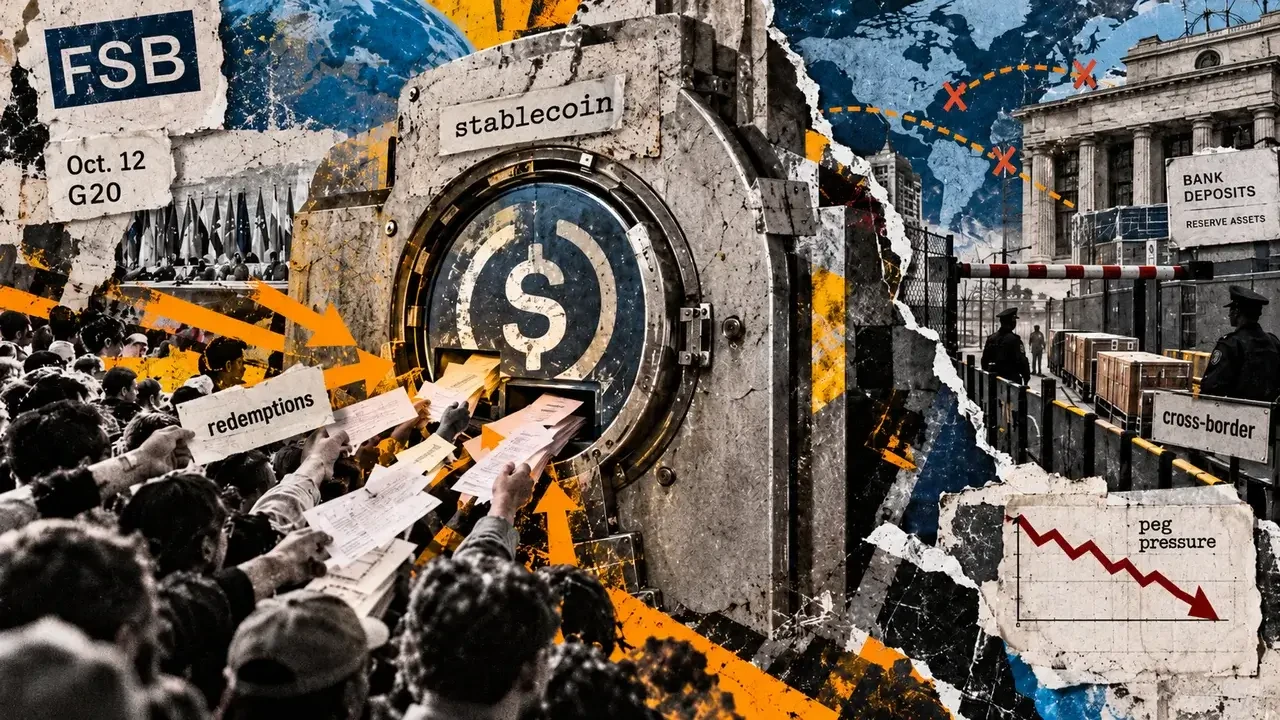
The Financial Stability Board (FSB) has issued a stark warning regarding the structural vulnerabilities of the global stablecoin market, cautioning that digital asset issuers could face severe redemption crises if cross-border reserves become inaccessible during periods of acute market stress.
In a comprehensive report published on Oct. 12, the international financial watchdog highlighted a critical flaw in how multi-entity stablecoin operations are structured. According to the FSB, stablecoin issuers operating through affiliated entities across different jurisdictions could easily struggle to meet concentrated, panic-driven withdrawal demands when a significant portion of their reserve assets is held in entirely different geographic regions.
The timing of the warning is highly strategic, arriving just ahead of an Oct. 15 meeting of G20 finance ministers and central bank governors. Global regulators are currently grappling with the systemic risks posed by an expanding stablecoin economy, which was valued at approximately $300 billion by mid-2026. Market data underscores the dominance of the US dollar within this sector, with roughly 99% of all stablecoin value pegged directly to the American currency.
Addressing the structural deficiencies within the ecosystem, FSB Chair Andrew Bailey emphasized that international regulatory coordination remains severely underdeveloped. Because of this fragmentation, global authorities currently lack mature, standardized arrangements for managing cross-border stablecoin failures or coordinating liquidity interventions during a systemic market shock.
Stablecoin Reserves Face Cross-Border Stress Test
The FSB’s report zeroes in on specific vulnerabilities inherent to stablecoins issued by multiple affiliated companies that share joint liability for the exact same digital token while maintaining segregated pools of reserves. Under these complex operational frameworks, token holders typically retain the flexibility to redeem their digital assets through any participating issuer within the network, regardless of the specific jurisdiction where the stablecoins were originally minted or acquired.
While this operational flexibility functions smoothly during normal market conditions, it introduces acute liquidity mismatches when redemption demand suddenly concentrates in a single jurisdiction. If a massive wave of redemptions hits one regional entity while the majority of the underlying collateral backing those tokens remains locked or held across international borders, a severe friction point emerges.
In theory, moving reserve assets swiftly between affiliated entities could resolve such an imbalance. However, the FSB notes that during a sudden market panic, traditional banking restrictions, cross-border settlement delays, and conflicting national regulatory mandates could severely impede or completely block those critical transfers.
The inherent velocity of digital assets further amplifies these risks. Cryptographic tokens circulate and trade around the clock on a 24/7 basis across global decentralized and centralized exchanges. In stark contrast, the traditional financial assets backing these tokens—such as US Treasury securities, commercial bank deposits, and other institutional money market instruments—remain strictly bound to local financial-market operating hours, banking holidays, and traditional settlement arrangements.
The financial watchdog warned that any noticeable delays in honoring redemption requests could swiftly erode market confidence, pushing holders to panic-sell their stablecoins at deep discounts on secondary markets. Such a cascading loss of confidence could easily destabilize their critical dollar pegs. Furthermore, a sufficiently large market run could quickly spill over into the broader traditional financial system if issuers are forced to liquidate their reserve assets at fire-sale prices or abruptly withdraw substantial deposits from commercial banking partners to meet overwhelming redemption demands.
To contextualize these cross-border complexities, the FSB pointed to recent adjustments made by major industry players. Circle’s European stablecoin arrangements serve as a clear illustration of how cross-border reserve management directly impacts practical redemption procedures. Under its revised redemption policy implemented in September, Circle co-issues its USDC token through a dedicated French entity to serve the European Economic Area, while relying on its primary US entity to handle markets outside the region.
This specific policy framework grants Circle France the legal authority to adjust or defer certain redemption requests during a formally defined stress event, particularly if the two international entities find themselves temporarily unable to complete the necessary reserve rebalancing procedures. These protective measures can include the imposition of temporary redemption limits for European crypto-asset service providers, while striving to legally preserve the fundamental rights of individual holders to redeem their tokens at par.
The FSB clarified that such provisions represent proactive contingency planning rather than an existing liquidity failure. Moreover, these mechanisms operate under Circle’s bespoke jurisdictional redemption rules, which differ substantially from the generalized, unrestricted cross-issuer redemption model evaluated by the global watchdog.
Nevertheless, the regulator’s broader concerns extend deeply into the legal responsibilities and liabilities of affiliated issuers when a stablecoin inevitably faces severe financial distress. The FSB noted that issuers frequently struggle to accurately identify where their circulating tokens are physically held. Because blockchain transactions are pseudonymous by nature, tracing ownership and determining precisely which corporate entity bears the legal responsibility for specific redemption obligations becomes an extraordinarily complex compliance hurdle.
Adding to this institutional uncertainty, stark differences in national insolvency laws across sovereign borders could create chaotic legal disputes over which regional regulator possesses ultimate authority to intervene and how any remaining reserve assets should be distributed among competing creditors and token holders.
These operational vulnerabilities are further compounded by a deeply uneven landscape of regulatory development around the world. The FSB’s 2025 assessment revealed substantial implementation gaps in how various countries have adopted its global stablecoin recommendations. This regulatory arbitrage creates persistent opportunities for agile issuers to strategically structure their multi-jurisdictional operations to exploit differing supervisory requirements.
FSB Seeks Stronger Regulatory Regime
In an effort to mitigate these systemic threats, the financial watchdog is aggressively pushing for the establishment of stronger international information-sharing frameworks. It is calling for much closer regulatory monitoring to track precisely where stablecoins are circulating, where redemptions are actively occurring, and where underlying reserve assets are physically deposited.
Beyond enhanced monitoring, the FSB wants national regulators to conduct rigorous assessments of secondary-market liquidity depths. It also urges authorities to develop more coordinated, cross-border approaches to handling potential stablecoin distress or corporate insolvency before a localized crisis escalates into a global contagion.
However, regulators face significant, persistent information gaps that complicate these oversight ambitions. The FSB acknowledged that blockchain analytics providers frequently rely on disparate methodologies and proprietary metrics to estimate stablecoin activity. Consequently, reliably establishing the true geographic locations of token holders and mapping complex cross-border transactions remains an immense technical challenge.
The proposed policy measures build directly upon the foundational recommendations issued by the FSB in 2023. Importantly, these guidelines remain non-binding, leaving national regulatory authorities entirely responsible for enacting and enforcing any substantial legislative or supervisory changes within their respective jurisdictions.
During the G20 meetings, international financial officials are slated to review the FSB’s detailed findings as part of broader discussions centered on safeguarding global financial stability. While the watchdog has outlined a necessary roadmap for future work concerning cross-border monitoring, inter-agency information sharing, and comprehensive crisis planning, it has not yet established a definitive timetable for implementing common international procedures to govern the failure of a major multi-jurisdictional stablecoin issuer.